


About Brian DeChesare
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.
When a company “capitalizes” its R&D, it lists the initial spending as a cash outflow on the Cash Flow Statement and then “amortizes” it over time on the Income Statement, over a period such as 5 years, shifting the tax deductions to future periods; this treatment may be more accurate, but it has practical problems that limit its real-life usage.
Capitalized R&D Tutorial
Capitalized R&D Definition: When a company “capitalizes” its R&D, it lists the initial spending as a cash outflow on the Cash Flow Statement and then “amortizes” it over time on the Income Statement, over a period such as 5 years, shifting the tax deductions to future periods; this treatment may be more accurate, but it has practical problems that limit its real-life usage.
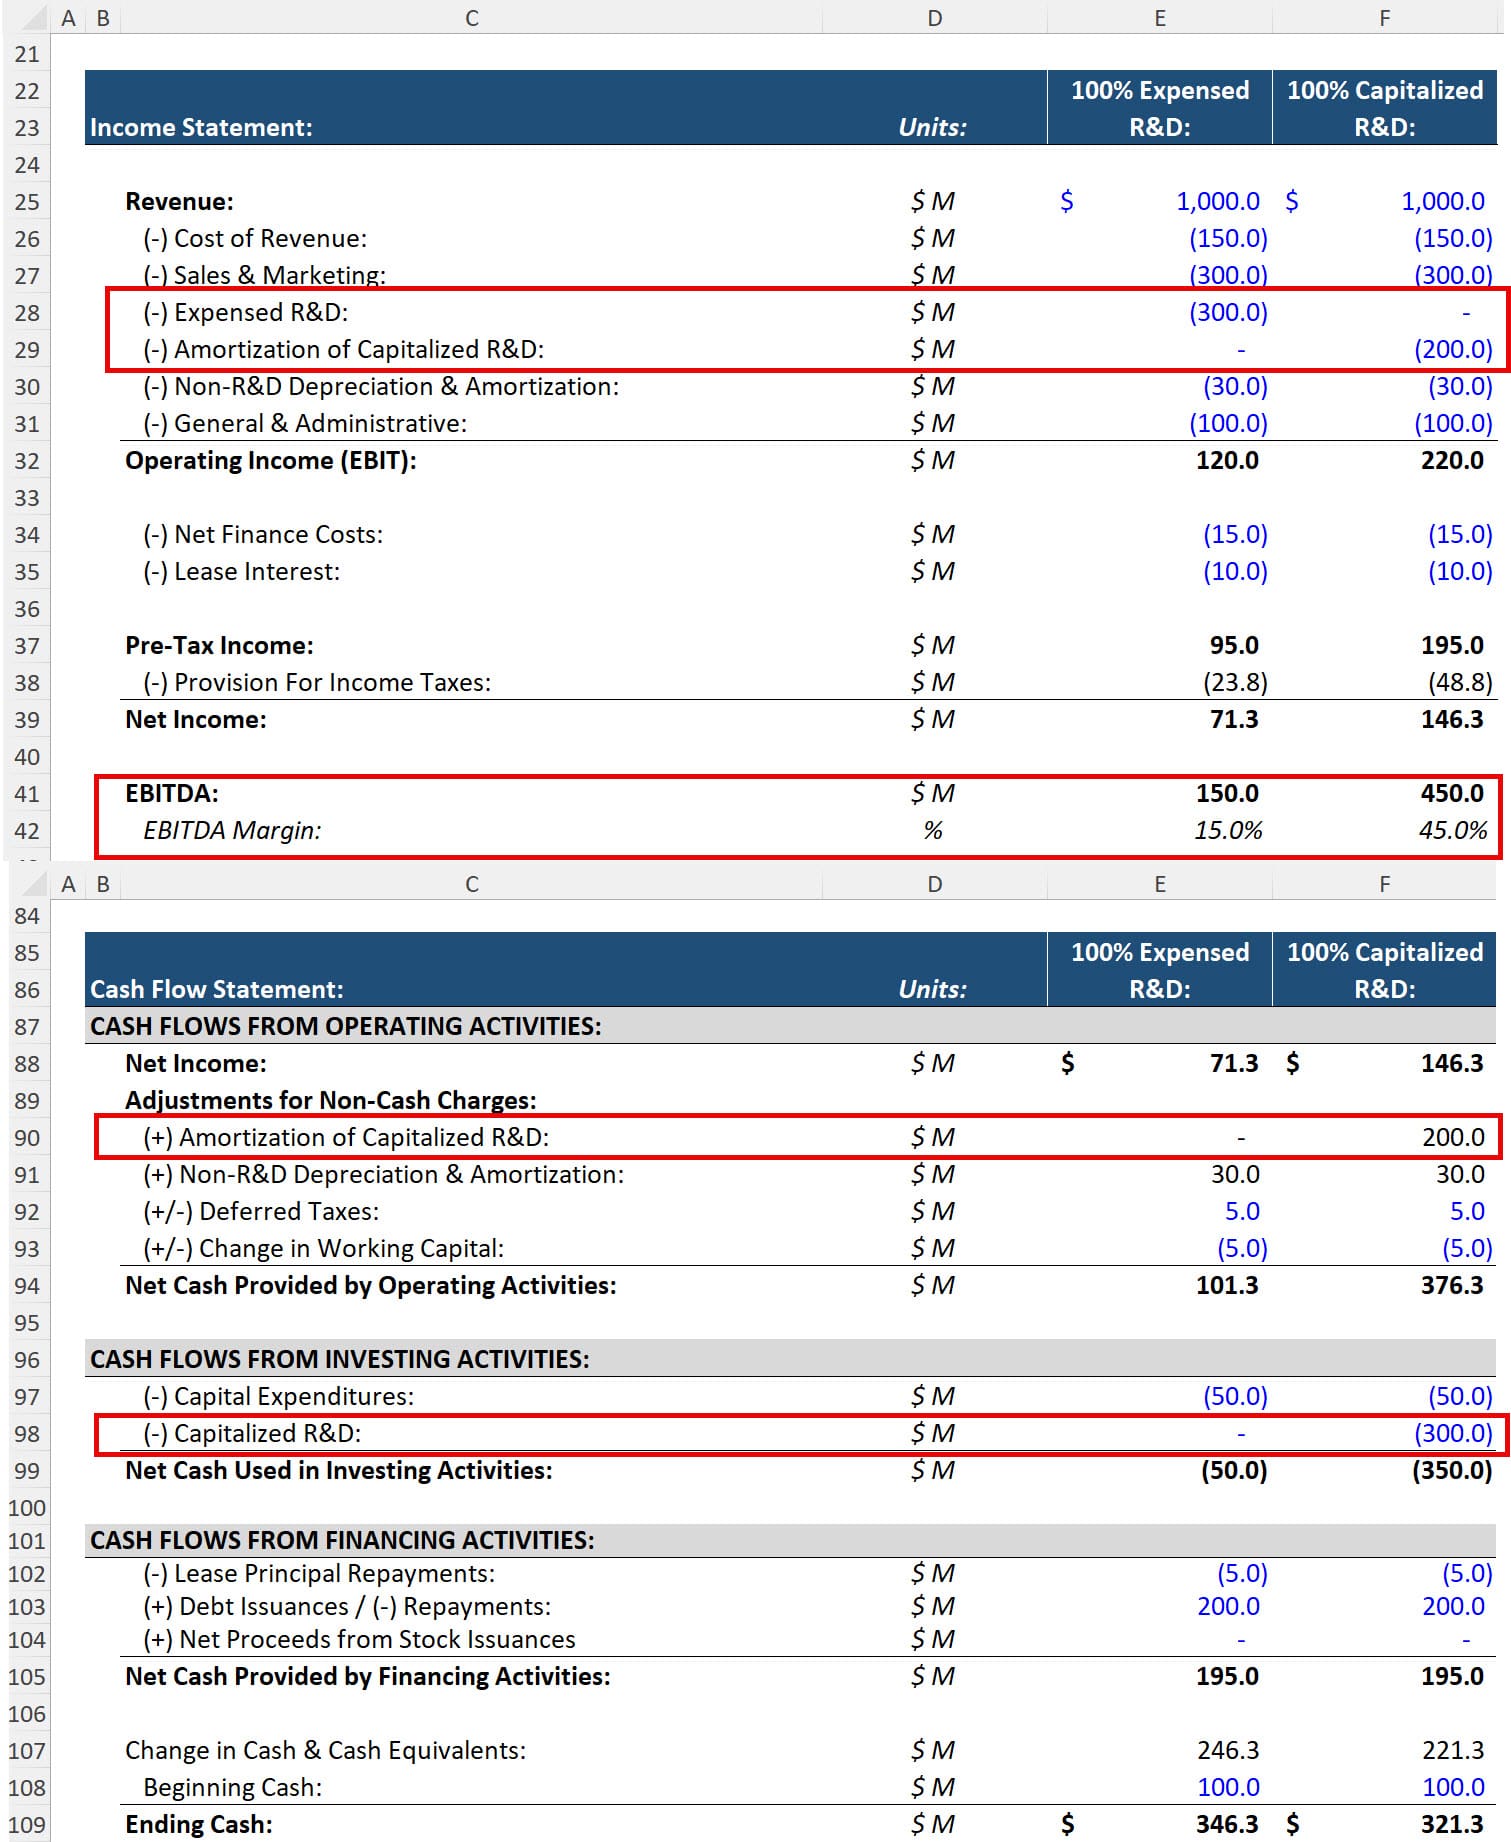
Under IFRS, capitalized R&D is much more common and has been encouraged for a long time; the controversy centers on U.S.-based companies due to changes in U.S. GAAP and the tax code.
Many sources, such as Professor Damodaran at NYU, recommend that when you project and value companies, you should adjust their financial statements by capitalizing their R&D spending.
They argue that it better reflects the nature of research & development: It’s intended to create valuable products that generate revenue over many years.
This reasoning is theoretically correct, but capitalizing R&D creates many practical problems with comparability and valuation multiples, which is why we recommend against it.
If a company is already capitalizing some of its R&D – as in the Xero examples below – then you can certainly continue this in the forecasts.
But if you want to make this adjustment yourself, it’s very difficult to define the “useful life” of R&D spending and the portion that qualifies for capitalization.
The rise of AI tools and companies spending small fortunes on tokens has made this problem even worse because it’s questionable to capitalize this type of spending.
After all, many of these “vibe-coded” tools may not even last a year, many are experimental, and many are used for internal purposes rather than client-facing products.
ASU 2025-06 prescribes rules around whether software costs should be capitalized or expensed, but you need significant disclosures to apply them properly.
So, we recommend following the company’s existing, internal treatment when building forecasts and valuations.
To illustrate the main concepts, we’ll use an example from our Twitter / X leveraged buyout model in the Private Equity Modeling course.
At the time Elon Musk executed his buyout of Twitter, U.S.-based tech firms had to capitalize their domestic R&D spending for cash-tax purposes.
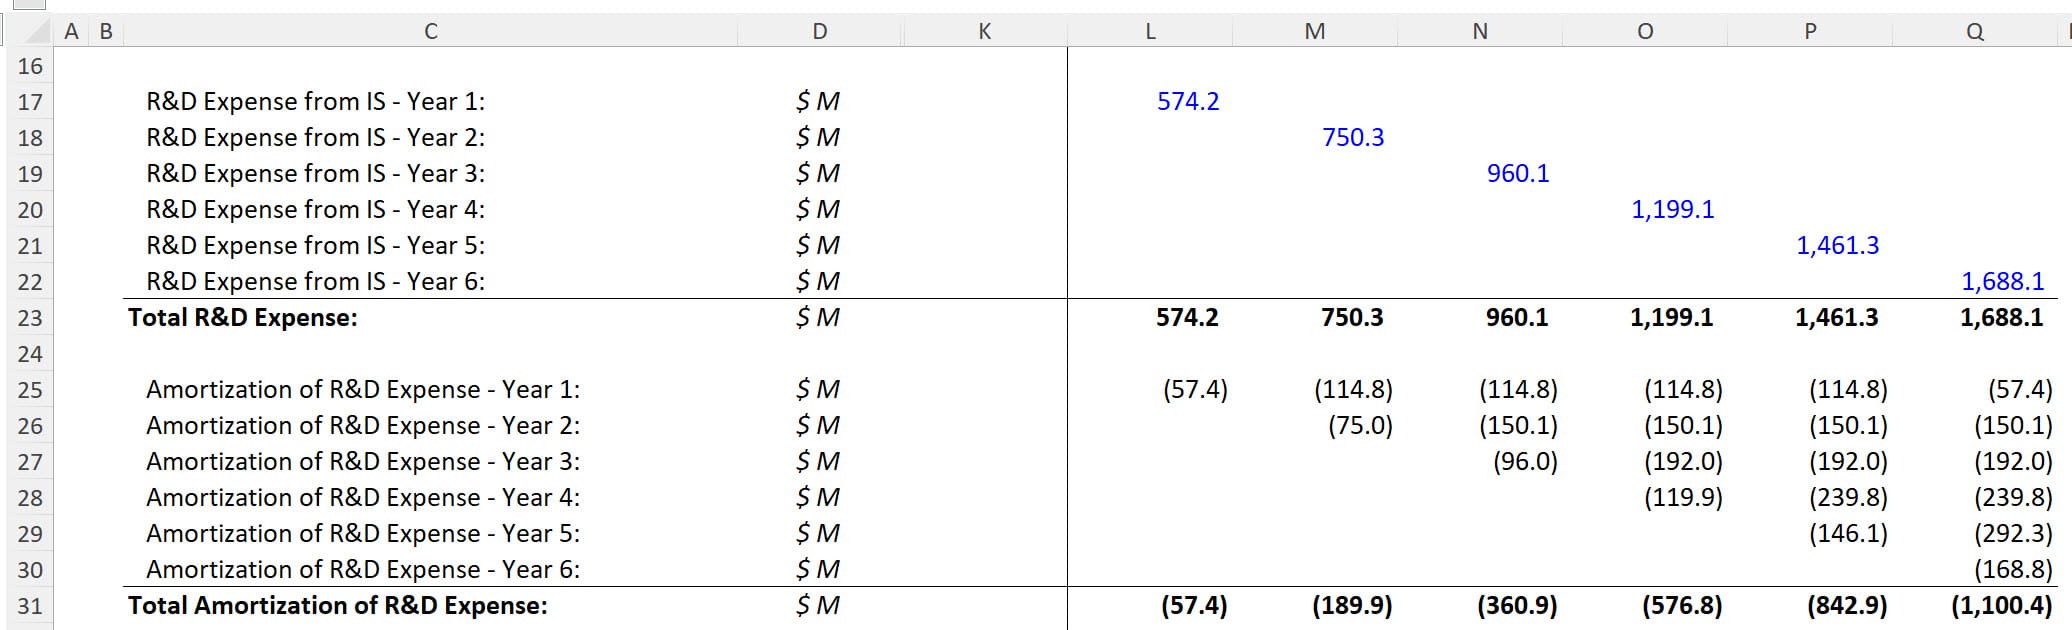
Therefore, we took the normal R&D spending that appears on the Income Statement and distributed it over a 5-year useful life:
Then, when calculating the Taxable Income, we used the Total R&D Amortization number rather than the actual R&D spending for the year (so, we added back the “R&D Expense” and deducted the “R&D Amortization”):
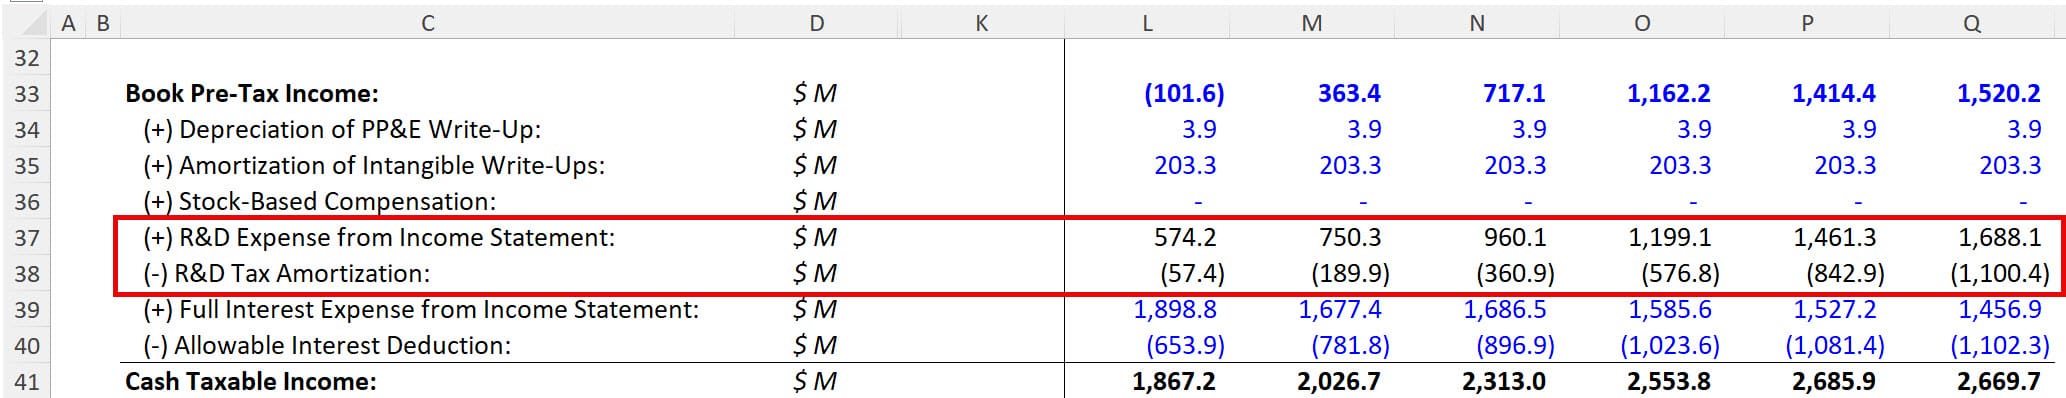
To take this one step further and truly capitalize R&D on the statements, we would have to move all the R&D spending to the Cash Flow Statement and list it in a line below CapEx.
Then, we would change the Income Statement and list the R&D Amortization rather than the normal R&D Spending.
As a direct result of this treatment, Twitter’s Cash Taxes are higher in the earlier years, but decrease/normalize in the later years.
This specific treatment only existed for a few years under U.S. GAAP; it ended when the “One Big Beautiful Bill” passed in 2025, which allowed companies to deduct their full domestic R&D spending (technically, they could choose whether to deduct or capitalize it, but most deduct everything possible).
Our general recommendation is to use the company’s current treatment because they know the purpose of their spending and the useful lives of their products better than you do.
Many non-U.S. companies capitalize part of their R&D because IFRS states that “experimental” spending should be expensed, while spending dedicated to specific product development should be capitalized.
A good example is the company Xero, based in New Zealand, which sells accounting/finance/bookkeeping software for small businesses:
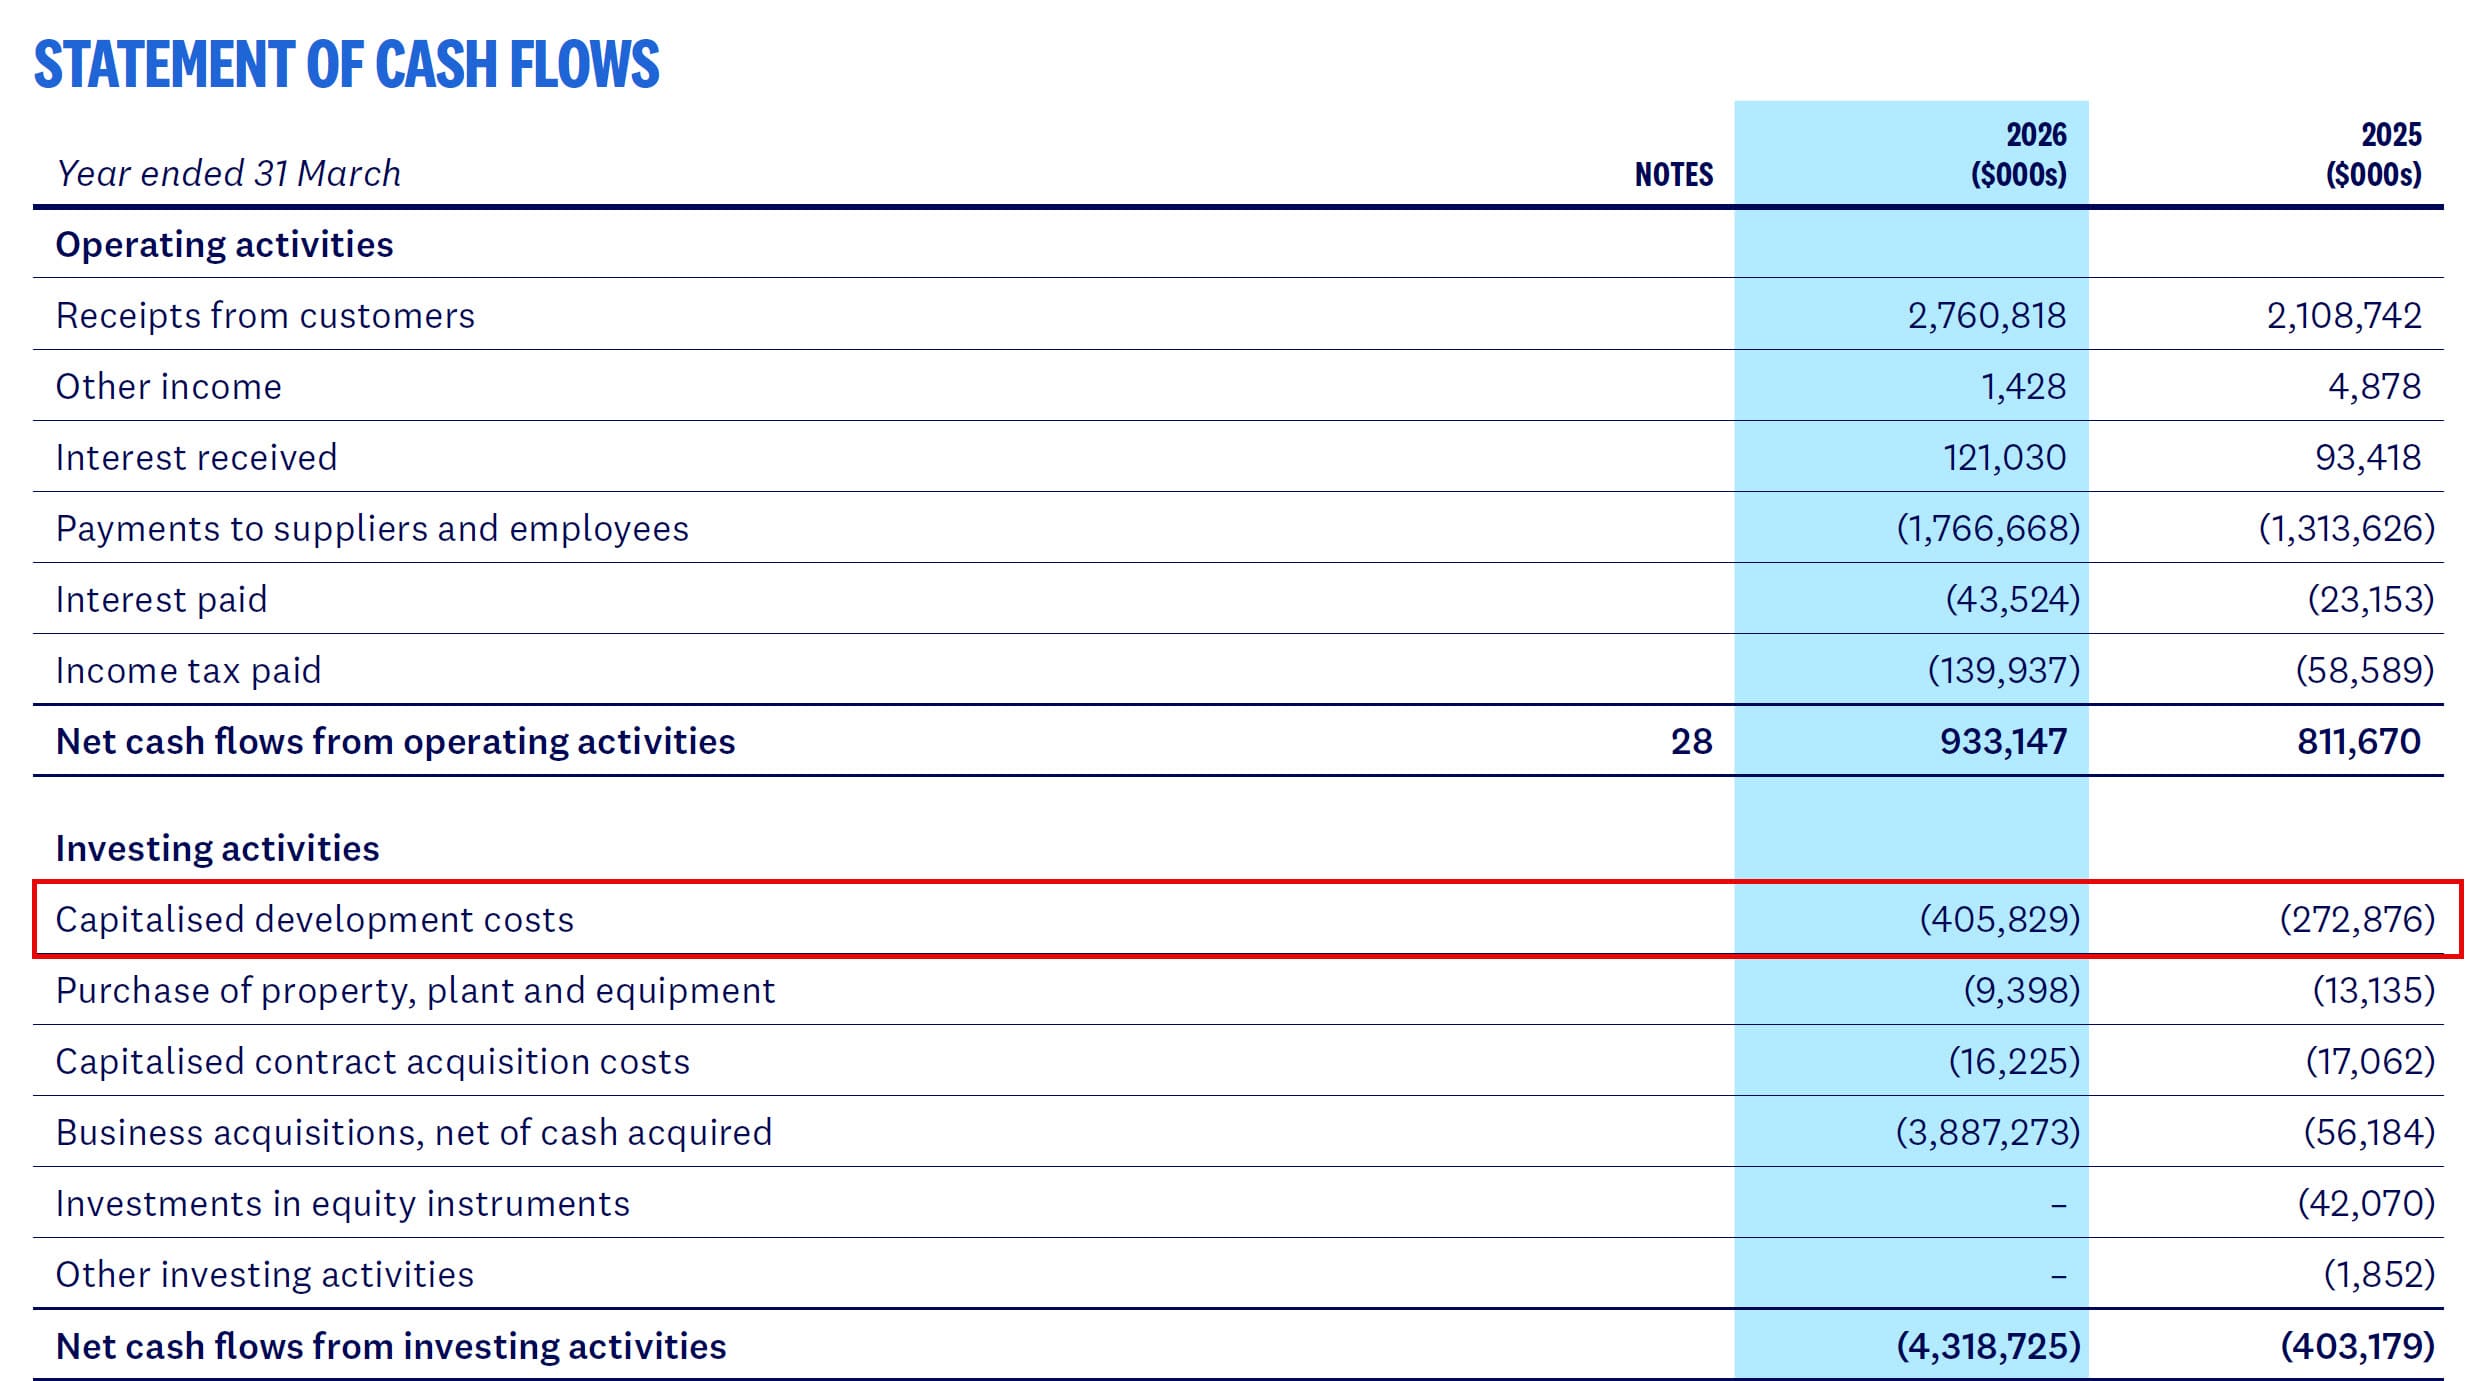
This company capitalizes part of its R&D and expenses the rest, so we subtract both in the Unlevered Free Cash Flow projections in the DCF:
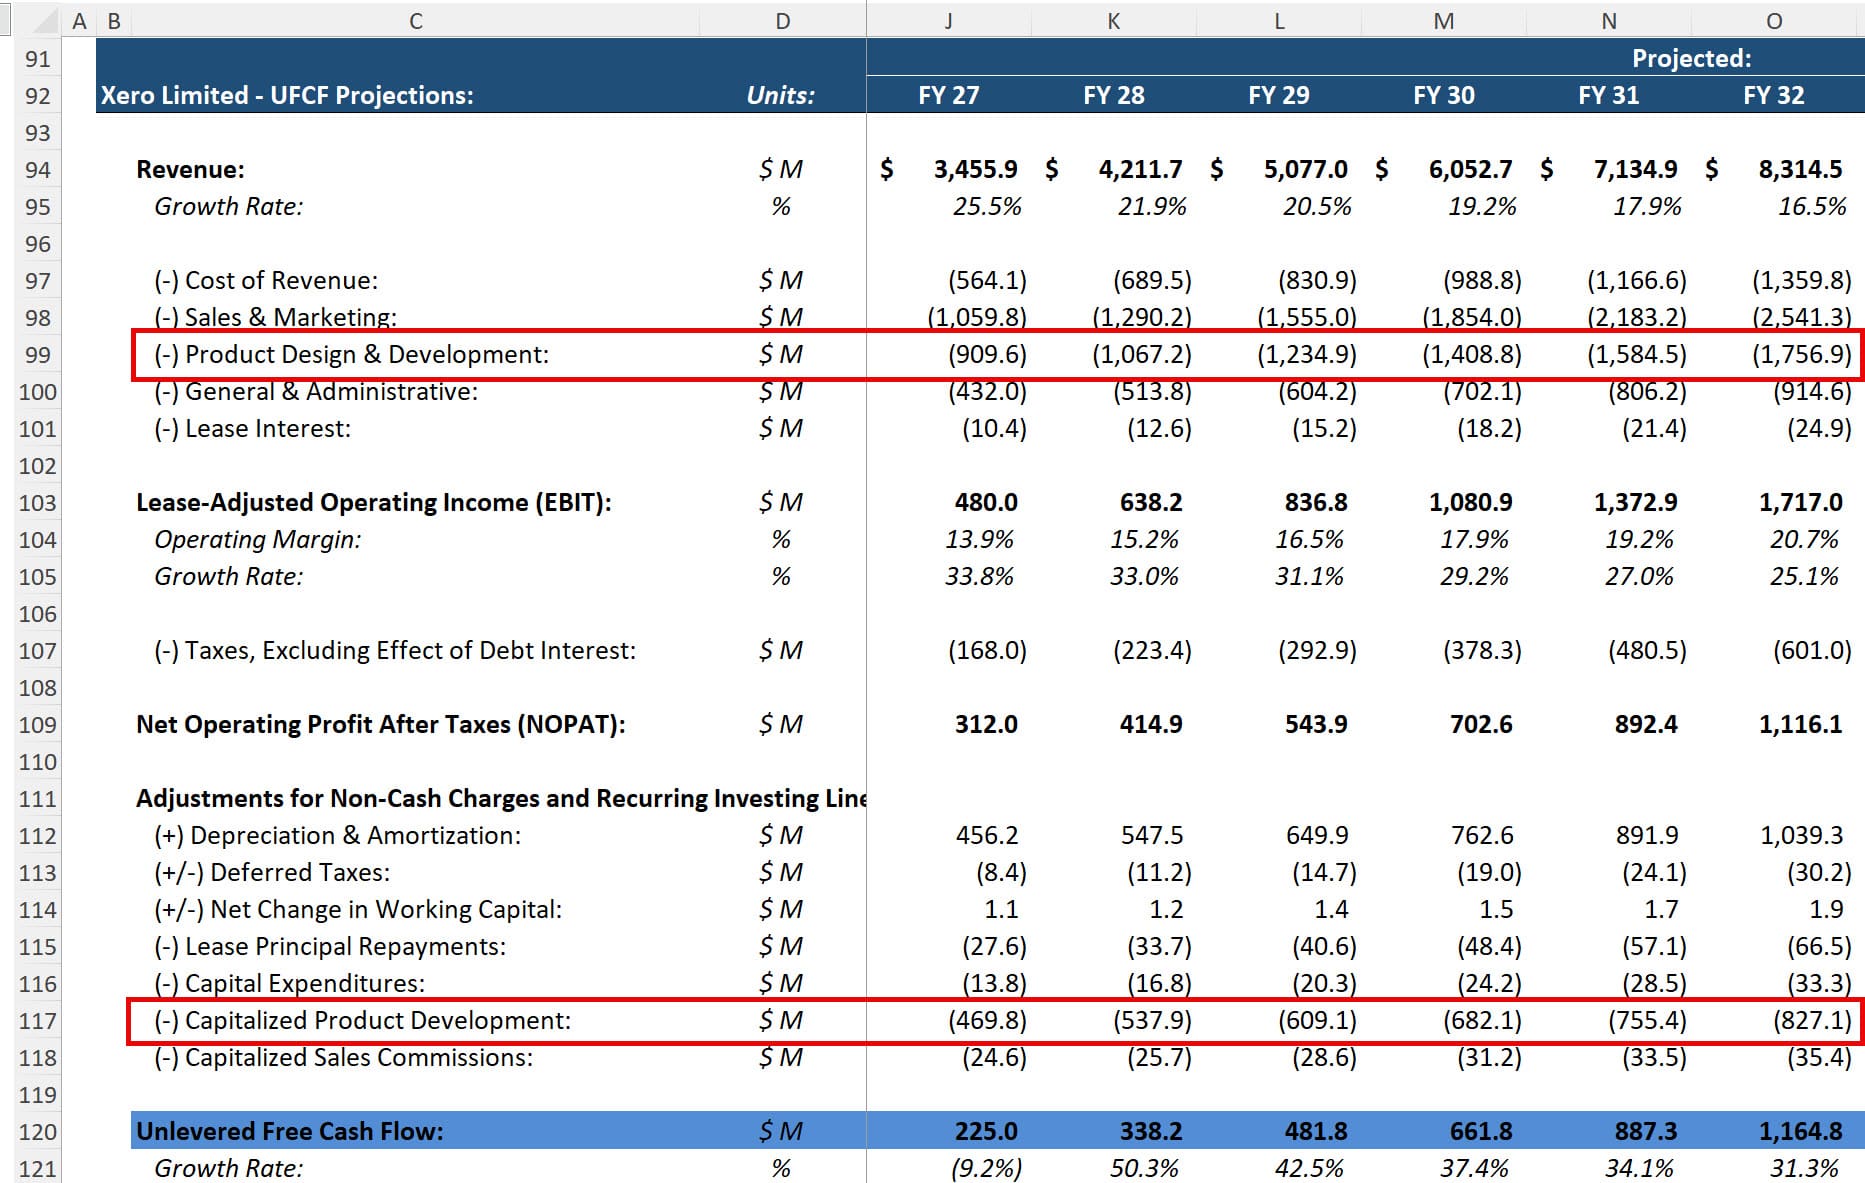
Both are cash outflows, but only the expensed R&D is a tax deduction.
If you’re wondering about the R&D Amortization, it’s now part of the “Depreciation & Amortization” line, which is embedded within the other expense categories above and added back as a non-cash adjustment.
In a traditional DCF, you set up the model to ensure that CapEx / Revenue exceeds D&A / Revenue if the company is expected to keep growing over the long term.
But for a company like this, the more appropriate comparison is D&A / Revenue vs. (CapEx + Capitalized R&D) / Revenue:
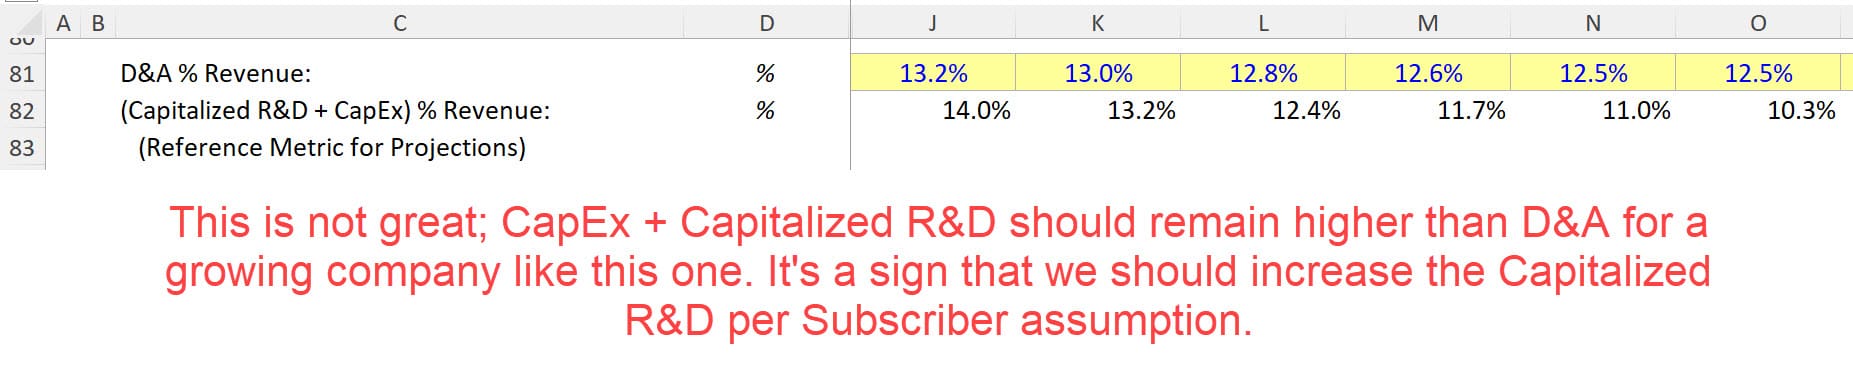
In this case, we would recommend increasing the Capitalized R&D Spending (projected on a $ per Subscriber basis) because CapEx + Capitalized R&D falls below normal D&A over the forecast period.
Capitalized R&D also distorts metrics such as EBITDA and the Return on Invested Capital (ROIC), or at least makes them more difficult to use for comparative purposes.
If you ever use a set of comparable public companies in a valuation, credit analysis, or financial statement analysis, you will have to capitalize R&D for each company in the set because of the types of issues shown below:
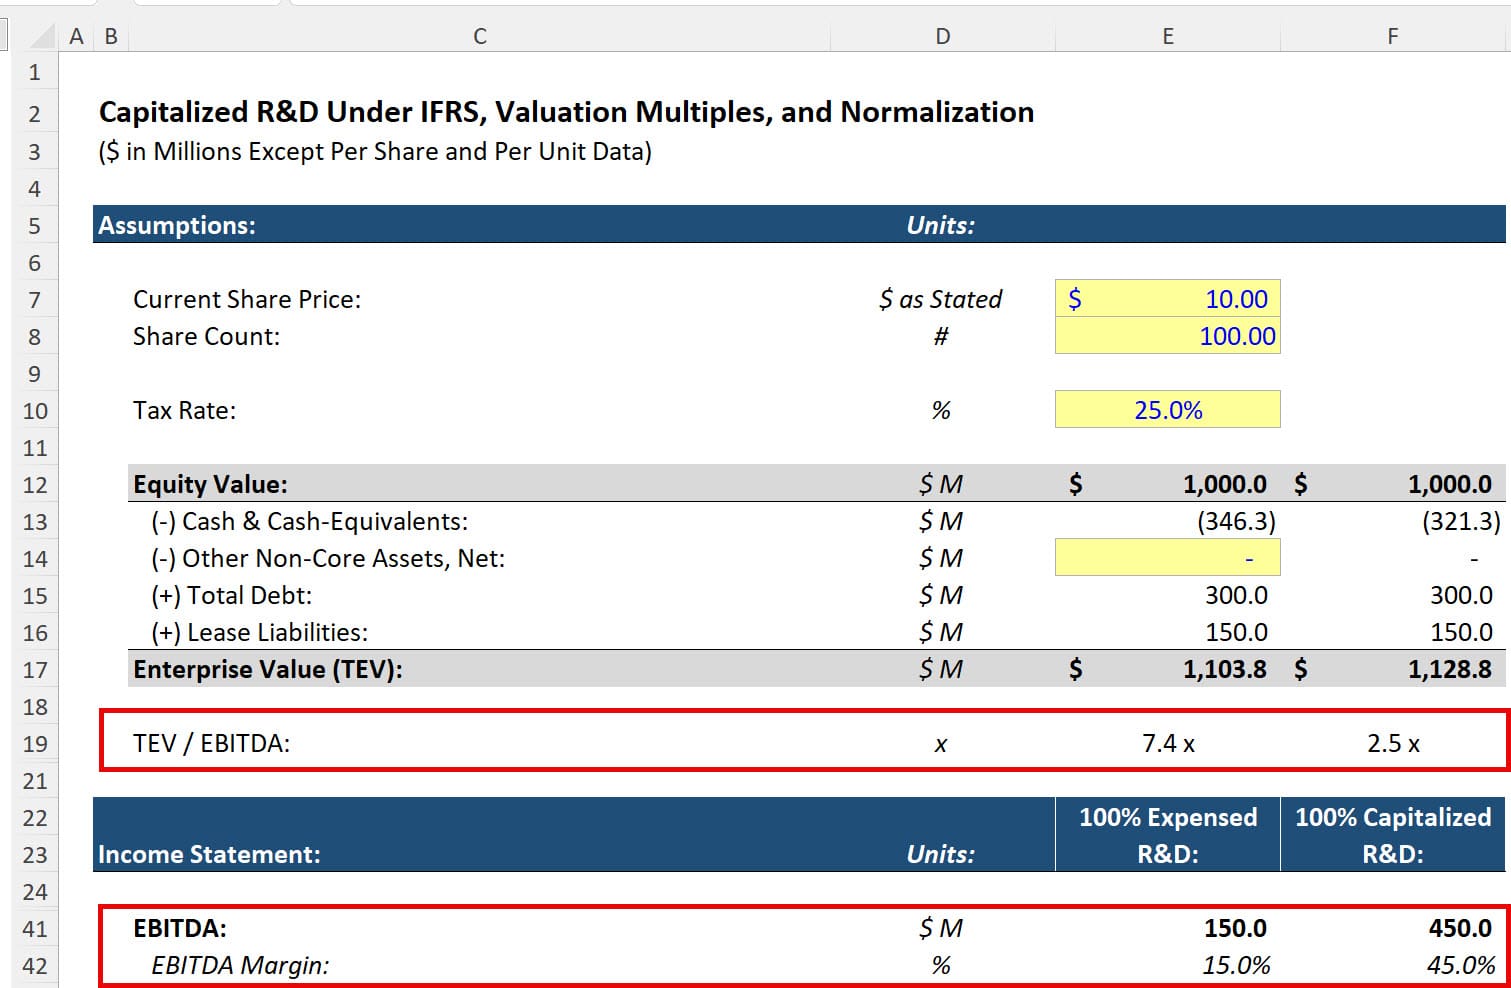
Company A here expenses all its R&D spending, while Company B capitalizes all of it.
Company A’s EBITDA is lower, while Company B’s is higher since the R&D Amortization is added back to EBITDA, and the actual R&D spending is not deducted from EBITDA since it’s a Cash Flow Statement line item.
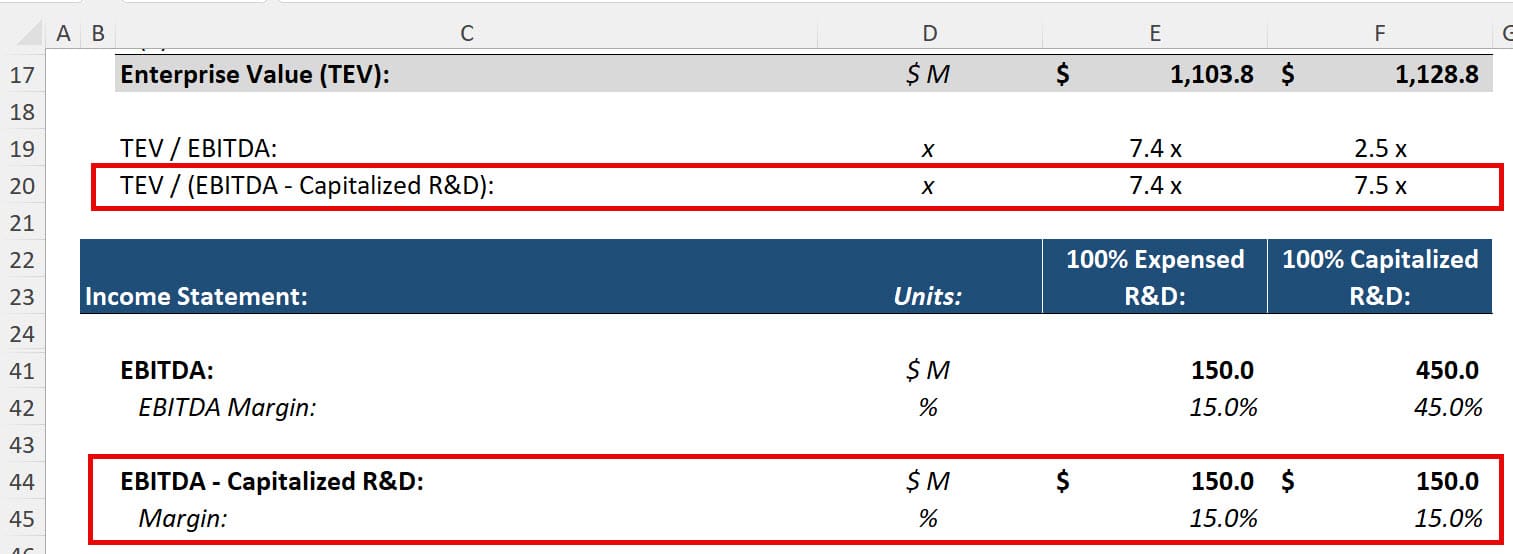
To fix this issue, you can modify EBITDA so that it deducts the Capitalized R&D:
Capitalized R&D also distorts metrics like ROIC because it increases the Net Operating Profit After Taxes (NOPAT) numerator in the early years, while Invested Capital increases over time because there’s a new R&D Asset on the Balance Sheet.
You would have to modify the ROIC calculation by deducting the Capitalized R&D in NOPAT and removing the effects of the R&D Asset in the denominator to address this.
The theoretical arguments for capitalizing R&D have merit because some portion of this spending corresponds to long-term features, products, and services that will generate revenue over many years.
But when you take 5 minutes to consider the practical implications, the problems become clear:
So, the path of least resistance is to capitalize R&D only if the company is already doing it for some of its spending, and management discloses the required metrics.
Many international firms do this because of differences in IFRS rules around R&D, but it’s much less common among companies that follow U.S. GAAP.
By capitalizing R&D, you’re making a mountain out of a molehill and turning a small problem into a host of confusing comparability issues in models.
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.

