


IFRS vs U.S. GAAP on the Financial Statements (21:57)
IFRS vs. U.S. GAAP differ on the financial statements mostly in their presentation of the Cash Flow Statement and treatment of Leases; you can find reconciliations to present the Cash Flow Statement properly and use alternative and adjusted metrics to deal with Lease comparability issues.
IFRS vs. U.S. GAAP
Summary
IFRS vs. U.S. GAAP differ on the financial statements mostly in their presentation of the Cash Flow Statement and treatment of Leases; you can find reconciliations to present the Cash Flow Statement properly and use alternative and adjusted metrics to deal with Lease comparability issues.
Under both major accounting systems, the Income Statement and Balance Sheet are largely the same. Some items may have slightly different names, but the Income Statement still starts with Revenue, shows Expenses, and finishes with Net Income or After-Tax Profits.
The Balance Sheet still has Current and Non-Current Assets and Liabilities and an Equity section, and Assets = Liabilities + Equity.
The differences emerge mostly on the Cash Flow Statement. U.S.-based companies typically start the CFS with Net Income and adjust for non-cash items, but non-U.S. companies might start with Operating Income or Pre-Tax Income, or show direct cash receipts and payments instead (i.e., the “Direct Method”).
Items may also be in more random locations; for example, some companies might put Dividends in Cash Flow from Operations for unclear reasons.
Leases are also quite different because the Operating Lease Expense is split into Interest and Depreciation elements under IFRS, while it is just a simple Rental Expense on the Income Statement under U.S. GAAP.
Finance Leases work the same way under both accounting systems (they are always split into Lease Interest and Lease Depreciation), but Operating Leases are bigger for most firms.
To deal with these issues, you normally have to find a Cash Flow Statement reconciliation for IFRS-based companies and use metrics such as EBITDAR or EBITDA-AL that add back or deduct all lease expenses for valuation purposes.
There are countless other differences between U.S. GAAP and IFRS, but the ones above are the major points that affect 3-statement models and valuations.
Video Table of Contents:
- 0:00: Introduction
- 3:07: Part 1: Differences on the Financial Statements
- 8:14: Part 2: How to “Convert” IFRS Cash Flow Statements
- b Part 3: Leases, Valuation Multiples, and the DCF Analysis
- 21:31: Part 4: More Advanced Topics
- 23:33: Recap and Summary
Files & Resources:
- U.S. GAAP vs. IFRS on the Financial Statements (XL)
- U.S. GAAP vs. IFRS in Valuation and Financial Modeling – Slides (PDF)
- EasyJet Financial Statements (PDF)
- Vivendi Key Extracts (PDF)
- Telstra Income Statement (PDF)
- Tencent Financial Statements (PDF)
IFRS vs. U.S. GAAP: Cash Flow Statement Conversion
EasyJet provides a good example of the types of problematic Cash Flow Statements that are common for IFRS-based companies:
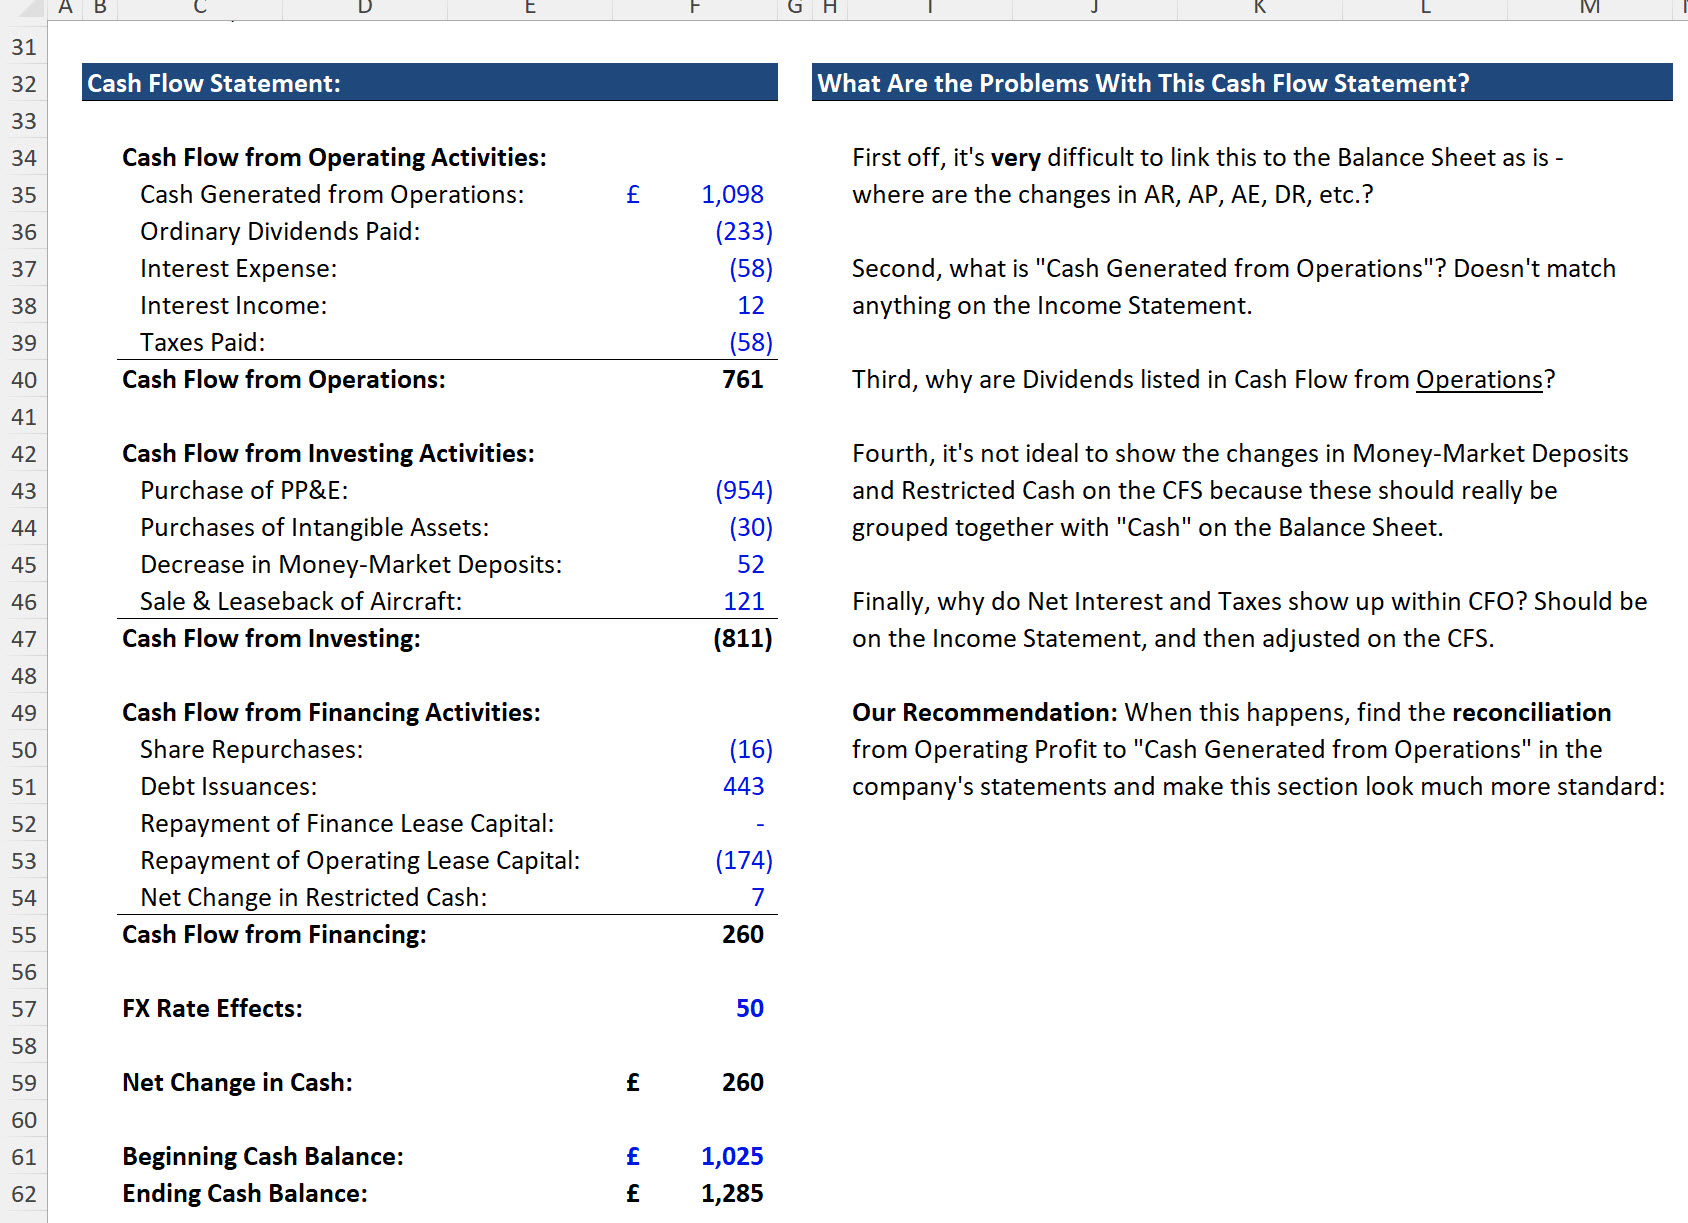
As noted above, the biggest issue here is simply that the company does not provide enough detail on its Cash Flow Statement to incorporate it into a true financial model.
We need to see how the Working Capital lines, such as Accounts Receivable, Inventory, and Accounts Payable, change, and we need more line items broken out from within the “Cash Generated From Operations” line.
There are also placement issues around the Dividends (they should be in Cash Flow from Financing) and line such as the Net Interest and Taxes.
You normally show these items on the Income Statement and then record the non-cash adjustments on the CFS, but EasyJet here is simply recording the entire Cash Net Interest and Cash Taxes in Cash Flow from Operations, which is not ideal.
To resolve these issues, you must find a reconciliation within the company’s statements:
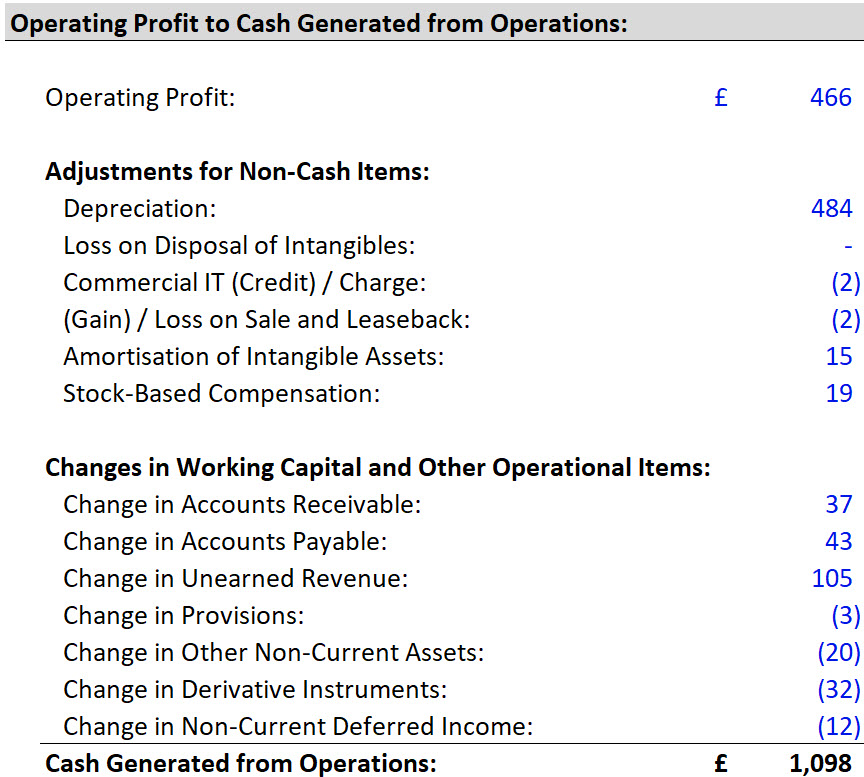
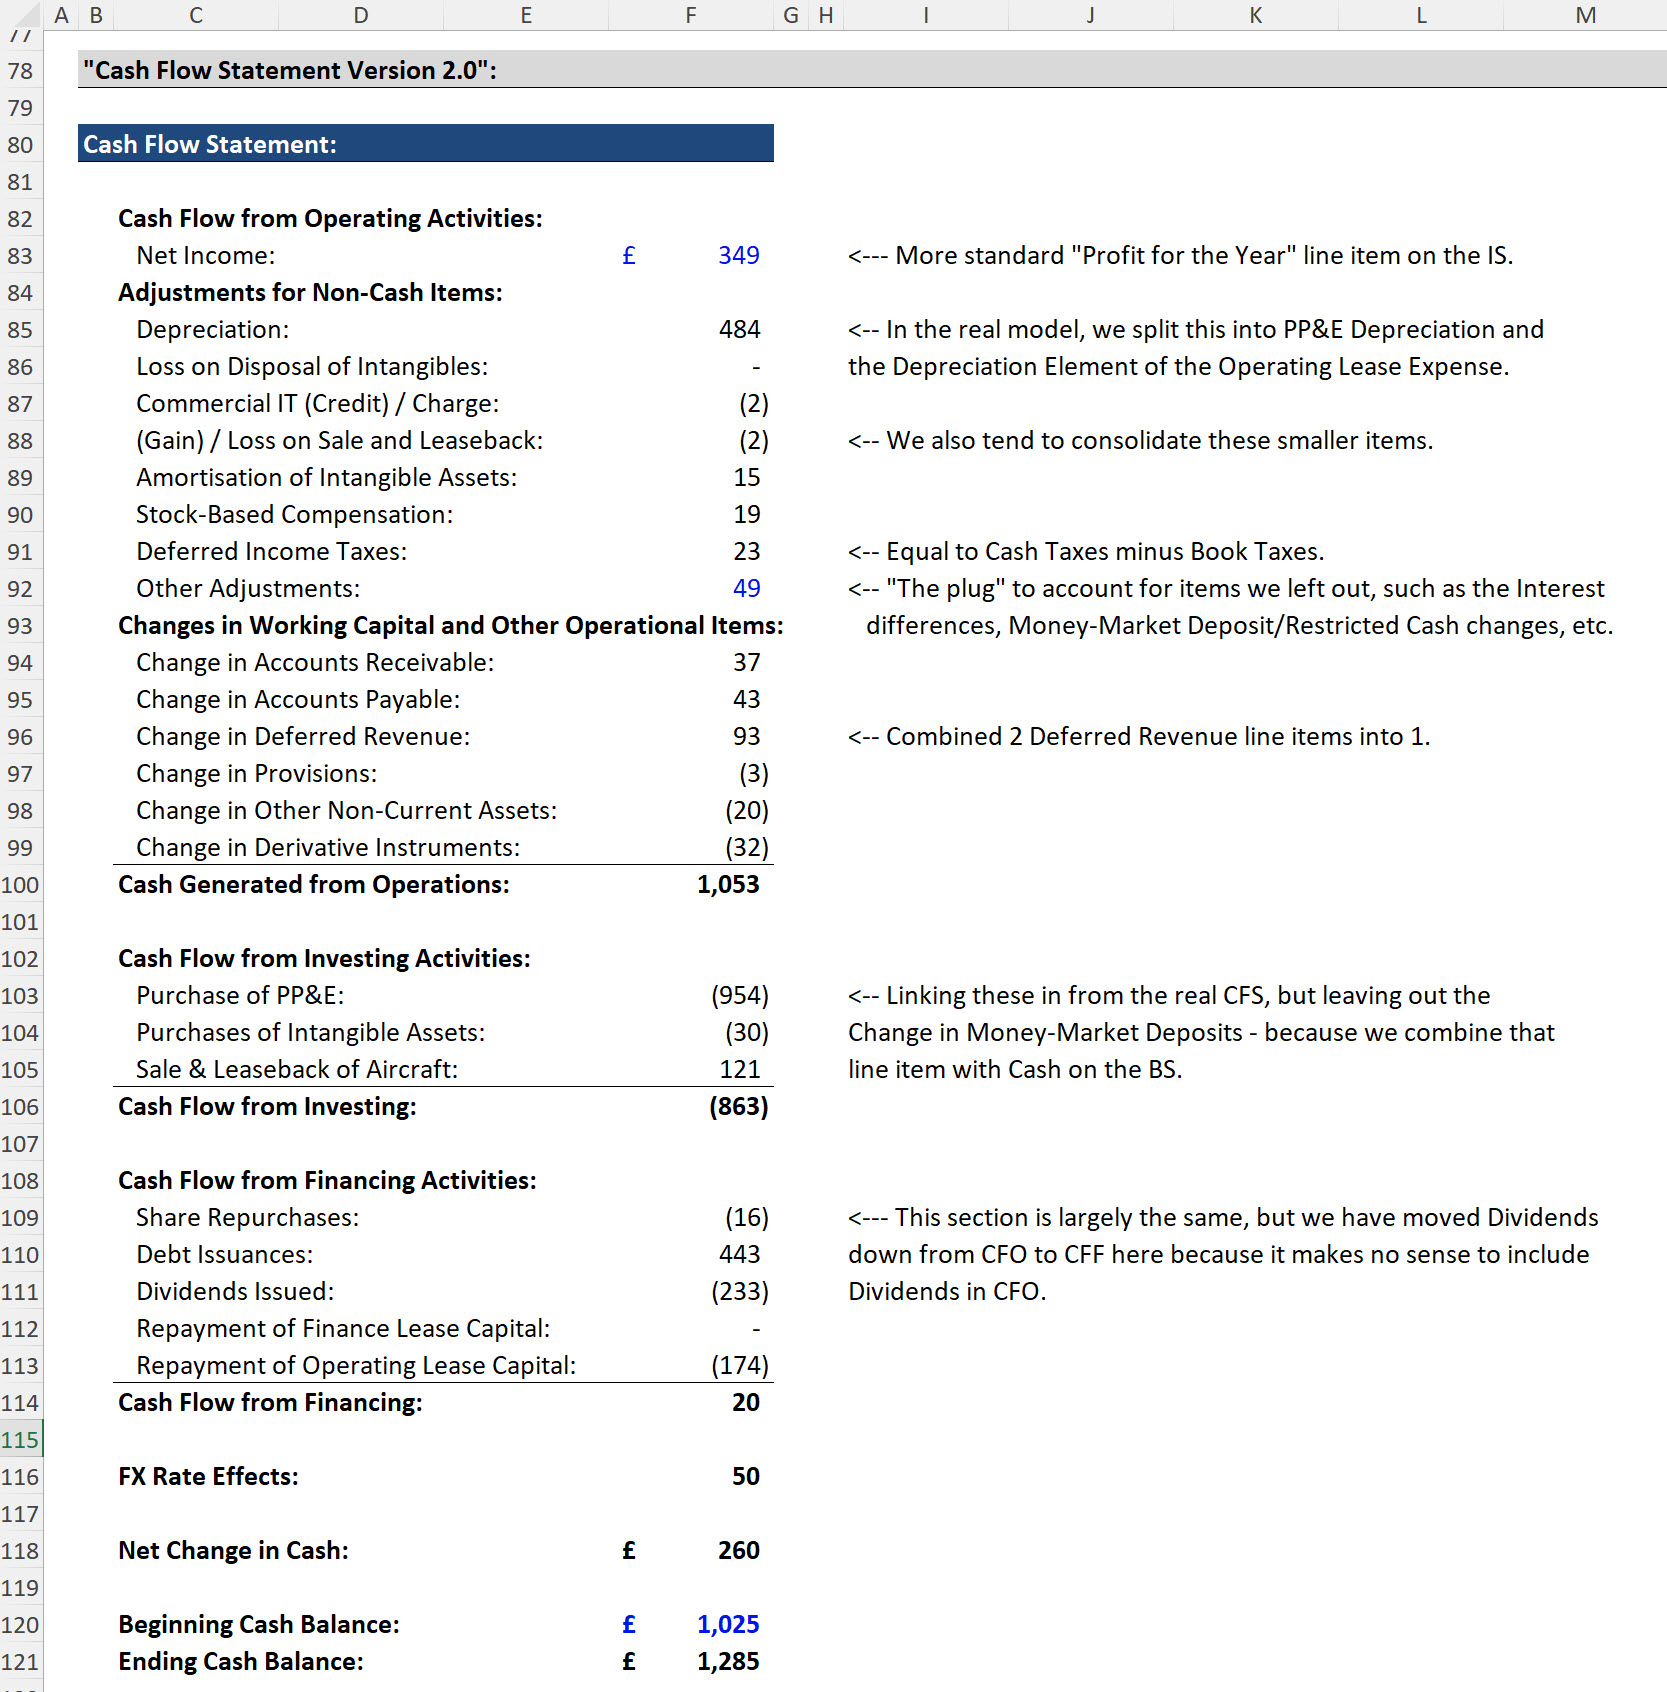
And then you can create a revised Cash Flow Statement that is closer to the traditional presentation:

-
Become a financial modeling pro
158 videos, detailed written guides, Excel files, quizzes, and more
-
Complete 10+ detailed global case studies
These include both the theory and the practical applications
-
Prepare for your internship or full-time job
Gain the skills you need to “hit the ground running” on Day 1
IFRS vs. U.S. GAAP: Lease Issues
Finance Lease Assets and Liabilities have always appeared directly on the financial statements, but starting in 2019, Operating Lease Assets and Liabilities also began to appear directly on the Balance Sheet under both accounting systems.
However, the Income Statement and Cash Flow Statement presentations differ because under U.S. GAAP, the Rental Expense is a simple expense line, but under IFRS, it is split into Lease Interest and Lease Depreciation.
We have a separate tutorial on lease accounting, which you should review for more on these points.
You do not have to do anything to “normalize” the statements because of these accounting differences, but you do need to be aware of them when you create 3-statement models and project the lease-related lines.
From a valuation perspective, you must be careful with the Enterprise Value calculation because it differs slightly under each system.
Under U.S. GAAP, if you count Operating Leases as a Debt-like item in Enterprise Value, you can no longer use EBIT and EBITDA because you must exclude the full Rental Expense in the denominator of valuation multiples.
So, the appropriate pairing is TEV Including All Lease Liabilities / EBITDAR.
Under IFRS, a metric like EBITDA already excludes the full Lease Expense, so it’s easiest to add all the Lease Liabilities in Enterprise Value and pair Enterprise Value with EBITDA directly (i.e., TEV Including All Lease Liabilities / EBITDA).
And if you’re comparing U.S. and non-U.S. companies, it’s best to use the TEV Including All Leases / EBITDAR multiple:
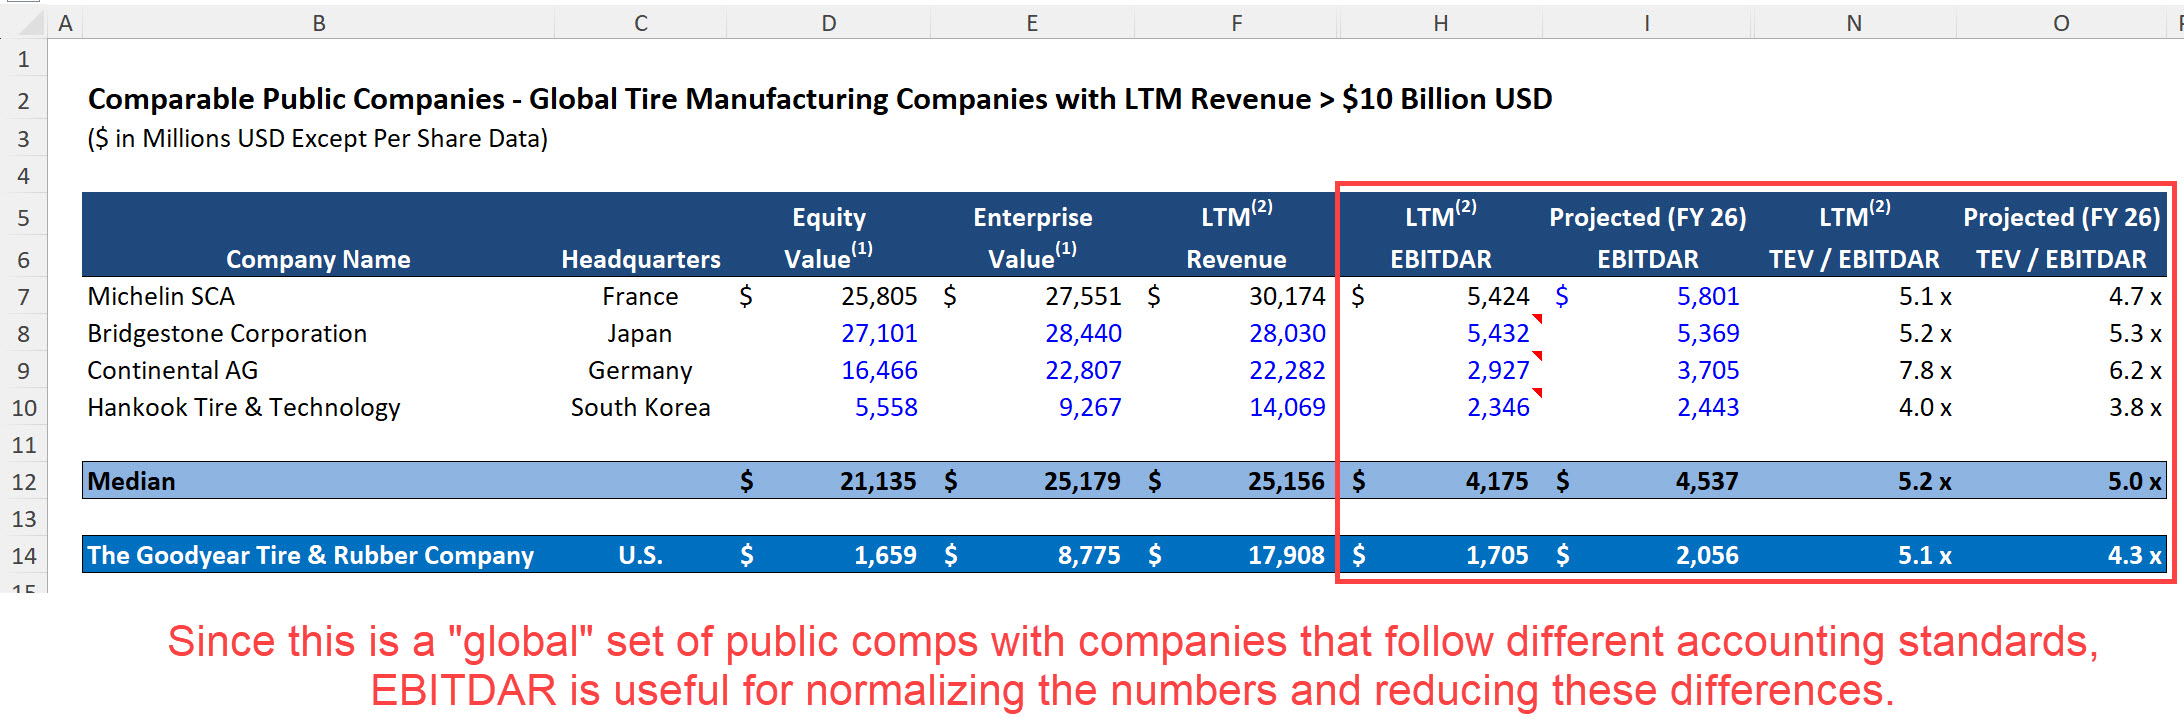
You could also potentially use something like EBITDA-AL (EBITDA After Lease Expense), which approaches it in the opposite way by deducting the full lease expense and not adding any Lease Liabilities in Enterprise Value, but not all companies disclose enough information to do this.
In a DCF analysis, it’s easiest to deduct the full Lease Expense, which is simple under U.S. GAAP since most of it is already deducted in Operating Income.
You should, technically, make an additional adjustment by deducting the Finance Lease Interest, but many companies do not even have Finance Leases, or the amount is so small it’s not disclosed separately.
Under IFRS, it’s trickier because Operating Income (EBIT) deducts only Lease Depreciation, but Lease Interest is a very significant line item that represents the other ~50% of the Lease Expense.
Therefore, you should adjust by deducting the Lease Interest from EBIT, and then you multiply that by (1 – Tax Rate) to calculate NOPAT for use in the Unlevered FCF calculation.
Then, you can either add back the entire D&A amount and subtract the Lease Principal Repayments from the Cash Flow from Financing section, or you could remove Lease Depreciation from Total D&A.
Either way, your goal is to deduct the full Lease Expense in UFCF:
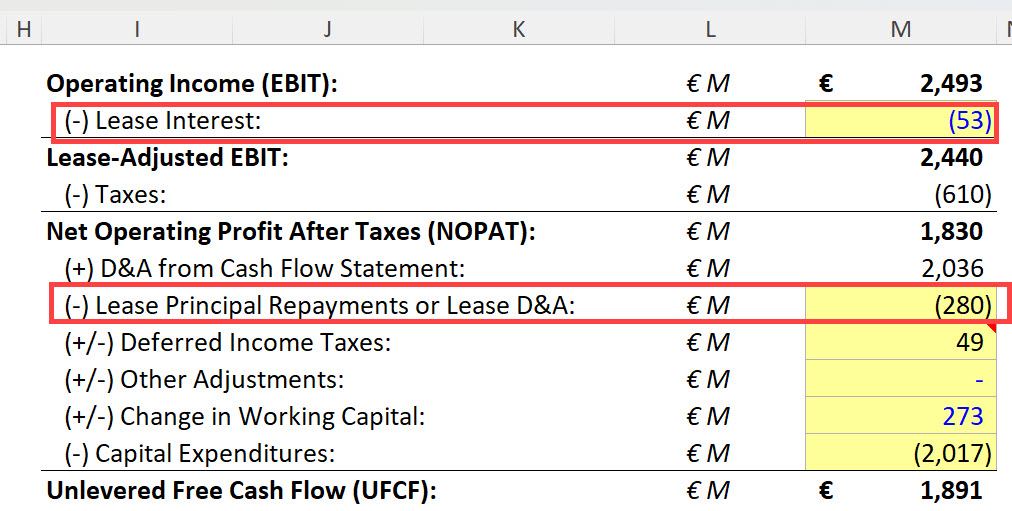
We prefer the first method (deducting the Lease Principal Repayments), but it depends on the information the company discloses.
If you deduct the full Lease Expense in Unlevered Free Cash Flow, you should not count Lease Liabilities in the Enterprise Value to Equity Value bridge at the end of the analysis, and they should not be a part of the WACC calculation.
We believe this treatment simplifies the DCF setup and makes it easier to calculate the key metrics, but some people approach it differently and add back the full Lease Expense, factor Lease Liabilities into the bridge, and count Lease Liabilities in WACC.
Other Points and More Advanced Topics
Of course, there are hundreds of other differences between IFRS and U.S. GAAP, and you can find 500+ page books and PDFs detailing all of them.
However, most of these other differences do not affect your day-to-day work in projecting and valuing companies.
For example, U.S. GAAP allows both LIFO “Last-In, First-Out”) and FIFO (“First-In, First-Out”) for recording Inventory costs, while IFRS allows only FIFO.
But this makes a marginal difference in real life because no companies provide enough information in their public filings to “adjust” line items like Inventory or COGS.
To make these types of adjustments, you would need information on the purchase prices and order dates for every single component of a company’s Inventory, which no company in their right mind would disclose publicly.
In practice, this difference simply means that you shouldn’t compare a U.S.-based retailer directly to a non-U.S. one, at least based on Inventory or COGS.
There are also many differences in line items like Taxes, Stock-Based Compensation, and Pensions, but many of these are country-specific and require more in-depth research because it’s not just a matter of “IFRS vs. U.S. GAAP.”
When in doubt, always think about what matters for projecting the cash flows and building valuations.
If one difference doesn’t affect those or cannot be translated into a direct impact, it probably doesn’t matter that much.
About Brian DeChesare
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.

