


About Brian DeChesare
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.
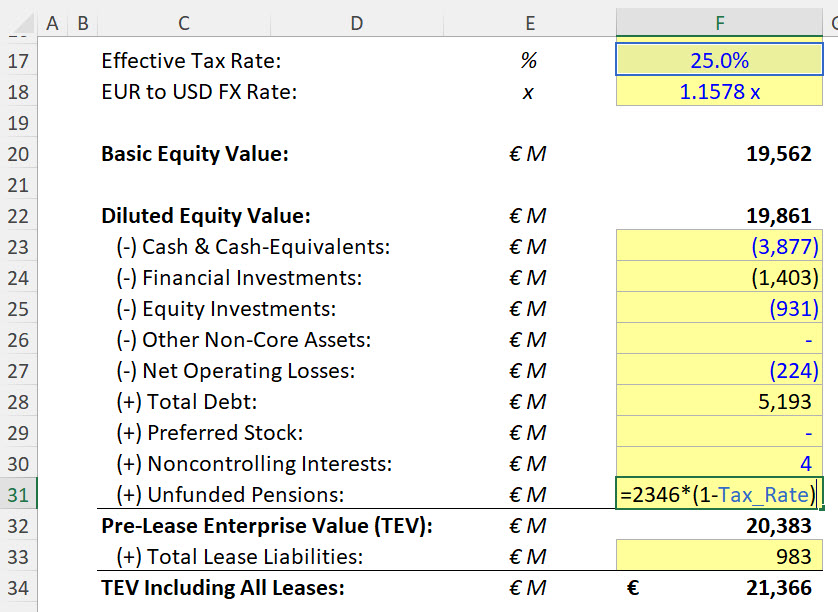
If a company has an unfunded or underfunded pension liability associated with a defined-benefit pension plan, you should add it in the Enterprise Value calculation. Exclude or add back the financial components of the pension expense in the corresponding multiples, and tax-adjust the net liability based on the tax treatment of employer contributions into the plan.
Unfunded Pensions Tutorial
Unfunded Pension Liabilities Definition: If a company has an unfunded or underfunded pension liability associated with a defined-benefit pension plan, you should add it in the Enterprise Value calculation. Exclude or add back the financial components of the pension expense in the corresponding multiples, and tax-adjust the net liability based on the tax treatment of employer contributions into the plan.
With a defined-benefit pension plan, a company offers to pay employees specific amounts in retirement based on the number of years they worked at the company and their average compensation in that time.
For example, one common formula might be:
Monthly Pension Check = 1% * # Years of Employment * Average Monthly Salary
So, if an employee worked for 20 years and earned $10K per month, on average, he would earn $2K per month from the pension after retirement.
These pensions incentivize long-term employment, make up for lower salaries, and (partially) “take care of” retirement; they also complicate valuation multiples and Enterprise Value.
The short version of unfunded pension liabilities is as follows:
1) Only “Defined-Benefit” Pension Plans Matter – These are plans in which the company promises to pay retired employees specific amounts in the future, and the company is responsible for setting aside the funds and investing them appropriately.
Defined-Contribution Pensions, such as the 401(k) plan in the U.S., do not factor into Enterprise Value at all because they do not appear on the Balance Sheet.
2) Add the Tax-Adjusted Un(der)funded Pension When Calculating Enterprise Value – In other words, add MAX(0, Pension Liabilities – Pension Assets) * (1 – Tax Rate) in most cases, assuming that contributions into the plan are tax-deductible. If this is not the case, do not multiply by the (1 – Tax Rate) term.
3) Exclude or “Add Back” the Financial Components of the Pension Expense in TEV-Based Metrics – The Pension Expense on the Income Statement is normally split into components such as the Service Cost, Interest, Expected Return, Amortization of Losses, Amortization of Prior Service Cost, Settlement Charges, and so on.
Only the Service Cost is operational, so only the Service Cost should be deducted in TEV-based metrics such as EBIT and EBITDA. The other components of the Pension Expense are all “financial” in nature.
Unfortunately, automated financial data sources like Capital IQ and FactSet often get these points wrong or ignore pensions altogether, so you can’t rely on them for this process.
Pensions are not that important for most companies because most modern firms do not offer defined-benefit pension plans.
However, if you’re working in a sector such as industrials or utilities, with much older companies, you will encounter pensions.
You can use the sample Excel files below to understand the key points about pension accounting and the calculations in valuation multiples:
To demonstrate these points, we’ll walk through a sample calculation for Michelin, the French auto tire company.
Note that in most cases, you will have to look up pension information in the company’s annual report because the interim reports for quarterly and half-year periods rarely provide everything.
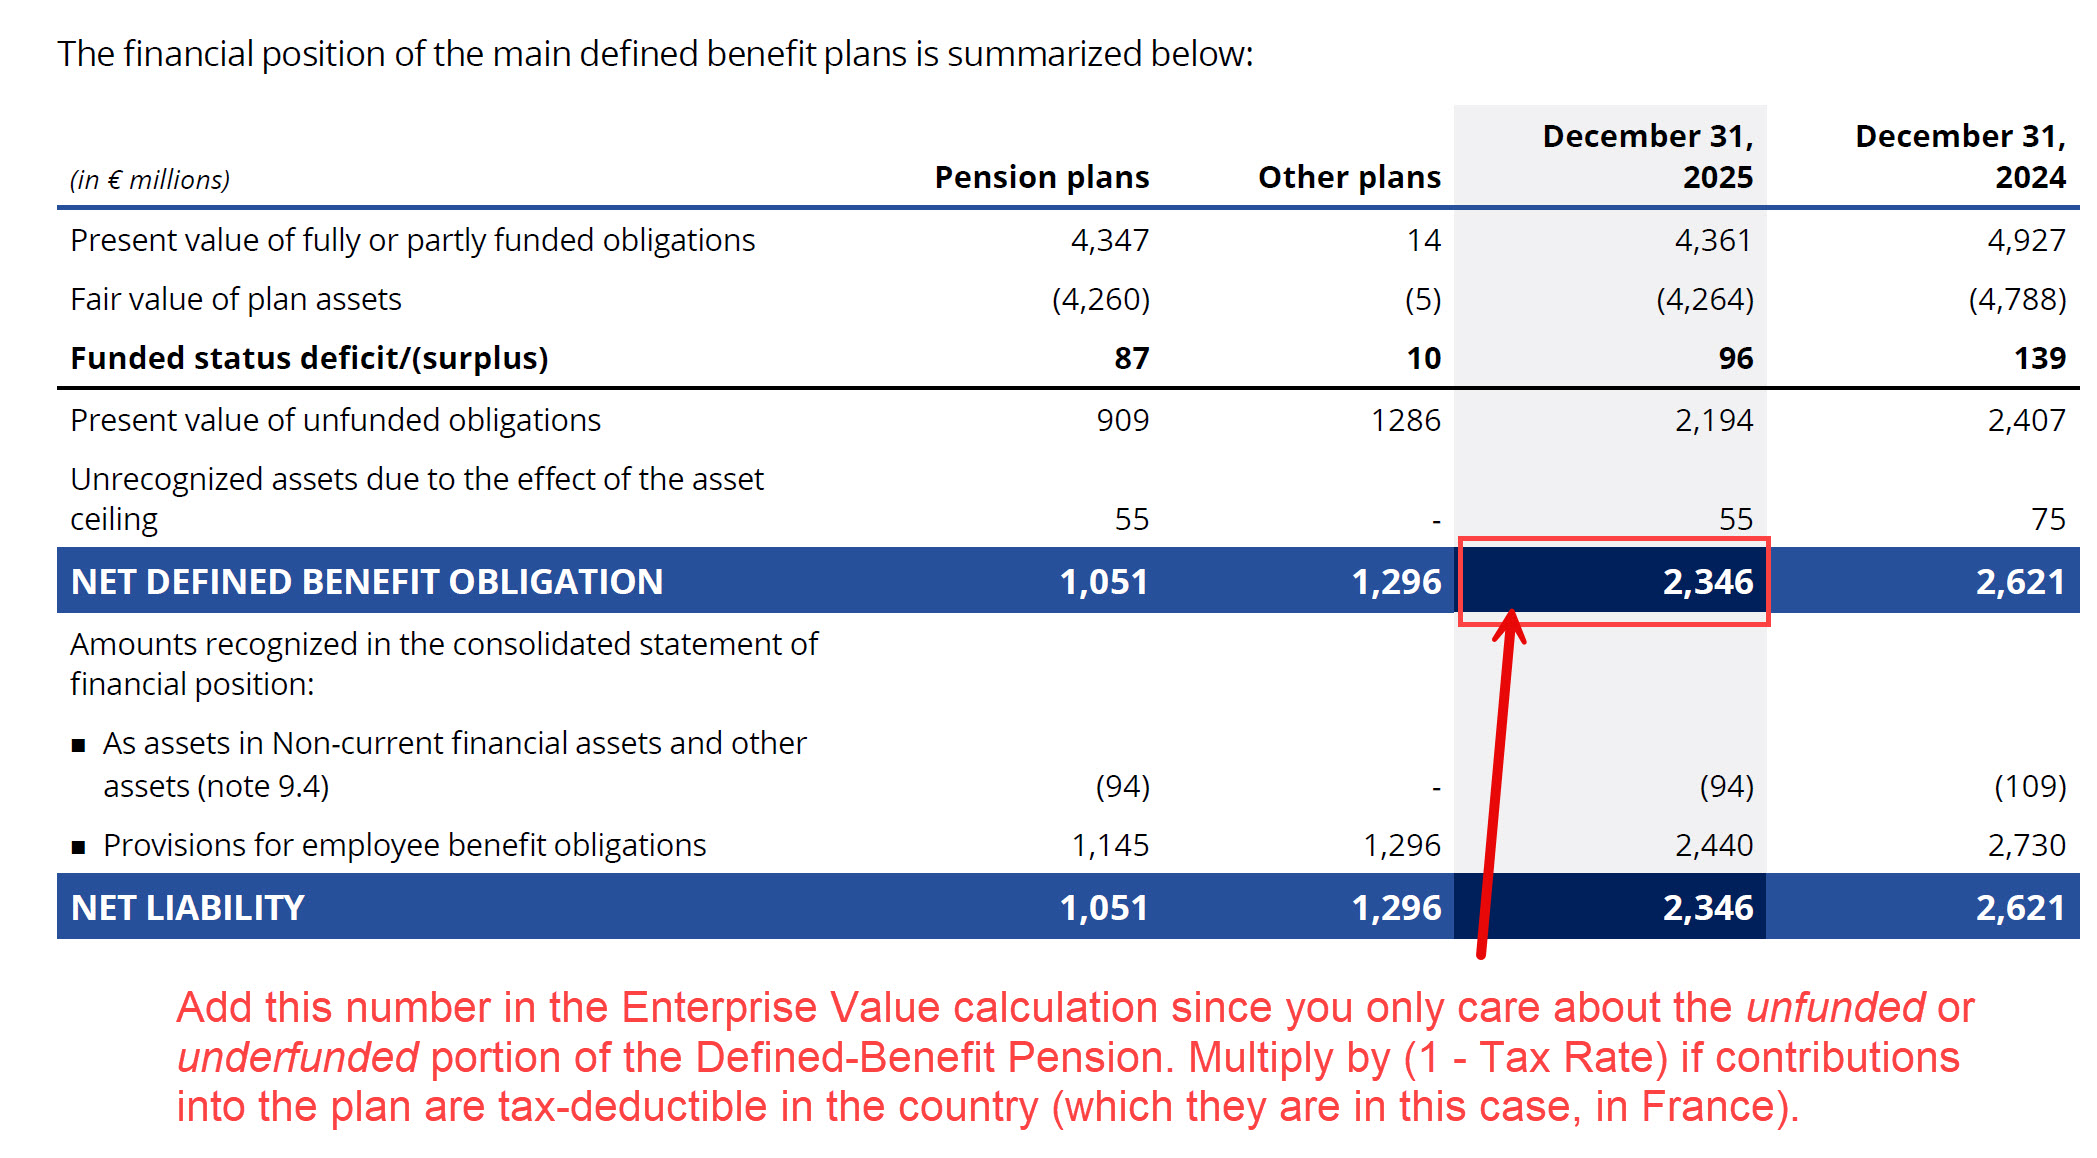
To find the Pension Asset and Pension Liability, you can search the annual filing for terms like “pension”:
Next, keep scrolling through the results to find the Pension Expense and its presentation on the Income Statement:
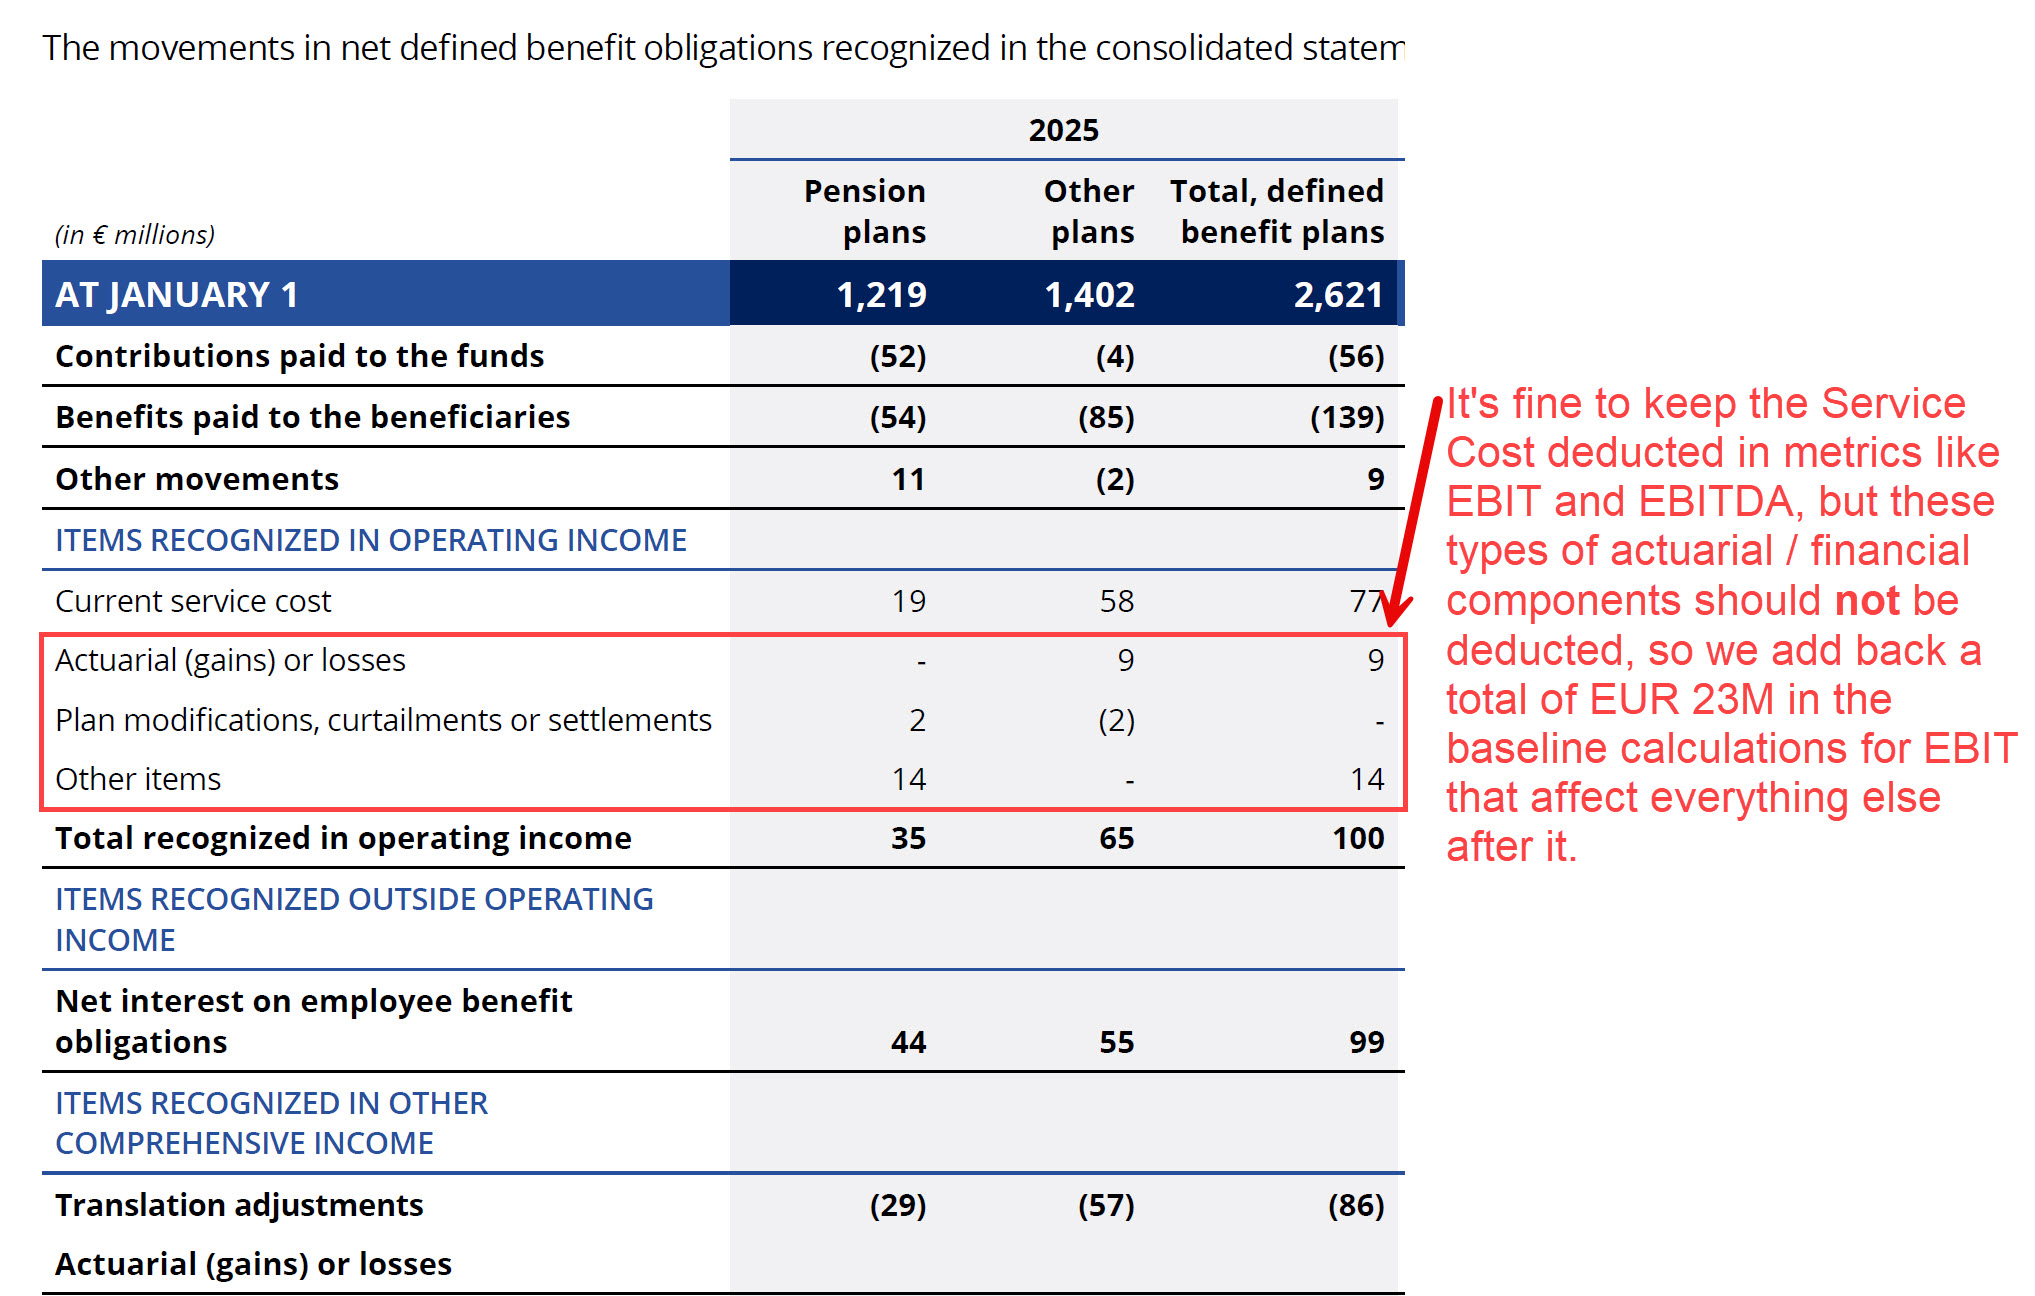
U.S.-based companies generally classify the Service Cost within Operating Expenses and place everything else within Interest Expense or Other Expenses, but under IFRS, the treatment varies widely, as shown in Michelin’s disclosures above.
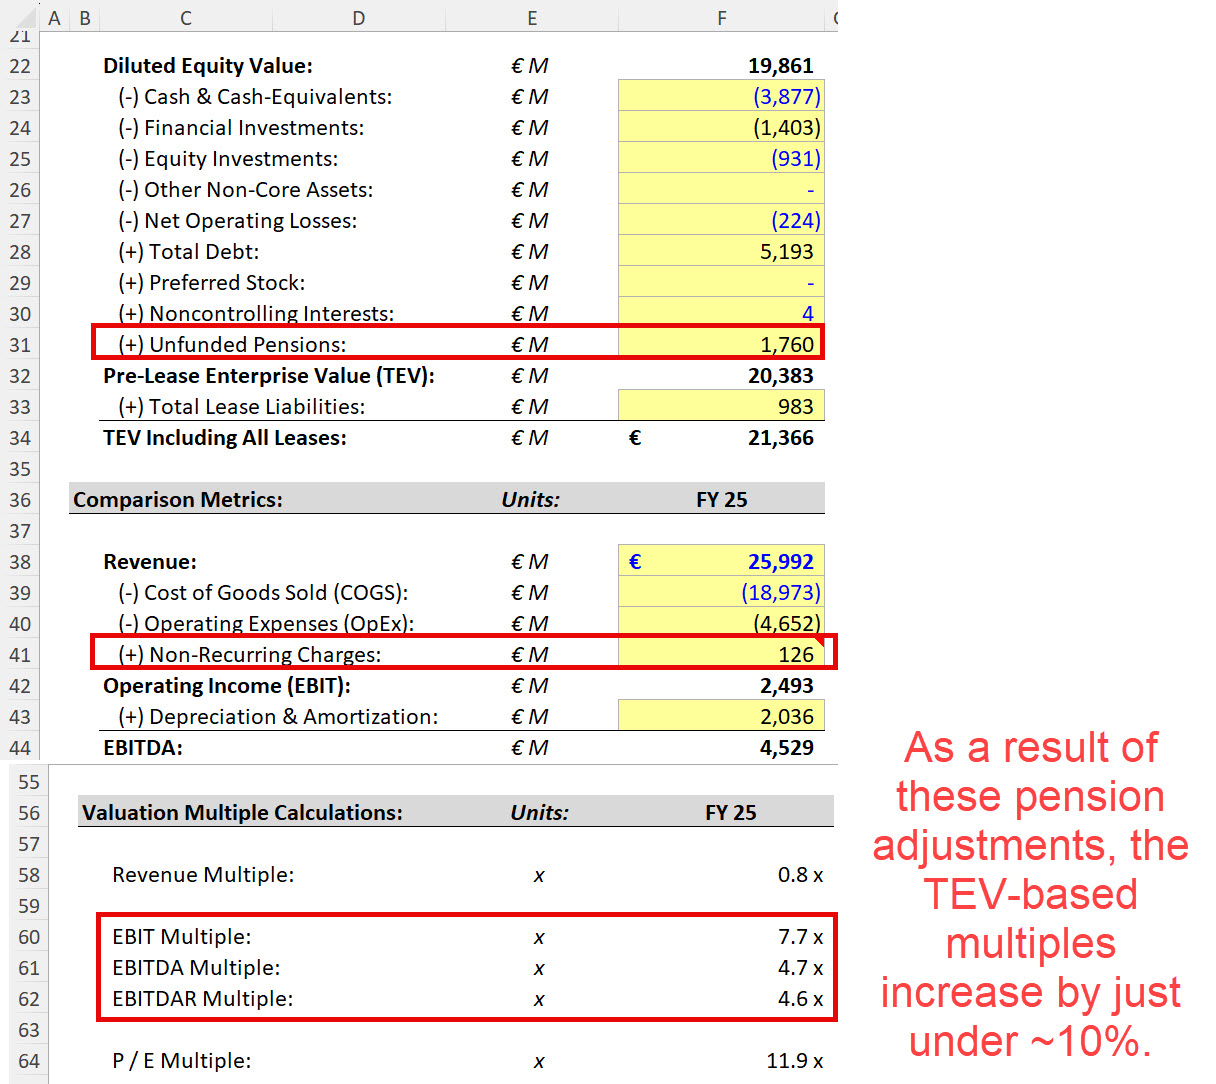
The final calculations, factoring in all the adjustments above, look like this:
Pension accounting gets extremely complicated, but the basics are straightforward and might be helpful if you want to learn the intuition behind the adjustments above.
If a company offers a plan where employees set aside some of their salaries, invest the funds independently, and withdraw the money in retirement, the complexity around pensions goes away.
Most likely, the company will offer a “match” for 25%, 50%, or 100% of what the employees contribute. This shows up as an Operating Expense on the Income Statement, as shown below:
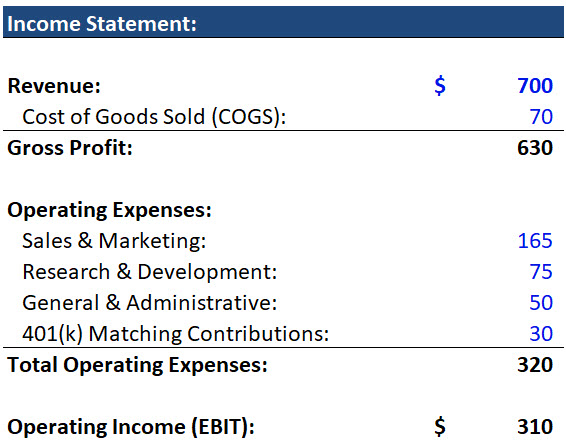
This type of plan does not create long-term Pension Assets or Liabilities because the employees, rather than the company, are responsible for everything.
If a company promises specific payments to employees in the future based on their current salaries and years of work at the company, the complexity increases dramatically.
When a company creates a plan like this, it must set aside funds to pay for it in the future. These funds appear as Pension Plan Assets on the Balance Sheet.
On the L&E side, the company must record a Projected Benefit Obligation (PBO) or Pension Liability associated with the plan. This item represents the Present Value of expected future payments to employees.
The Pension Plan Asset changes based on the investment returns on the assets, contributions from employers and employees, and benefit payments:
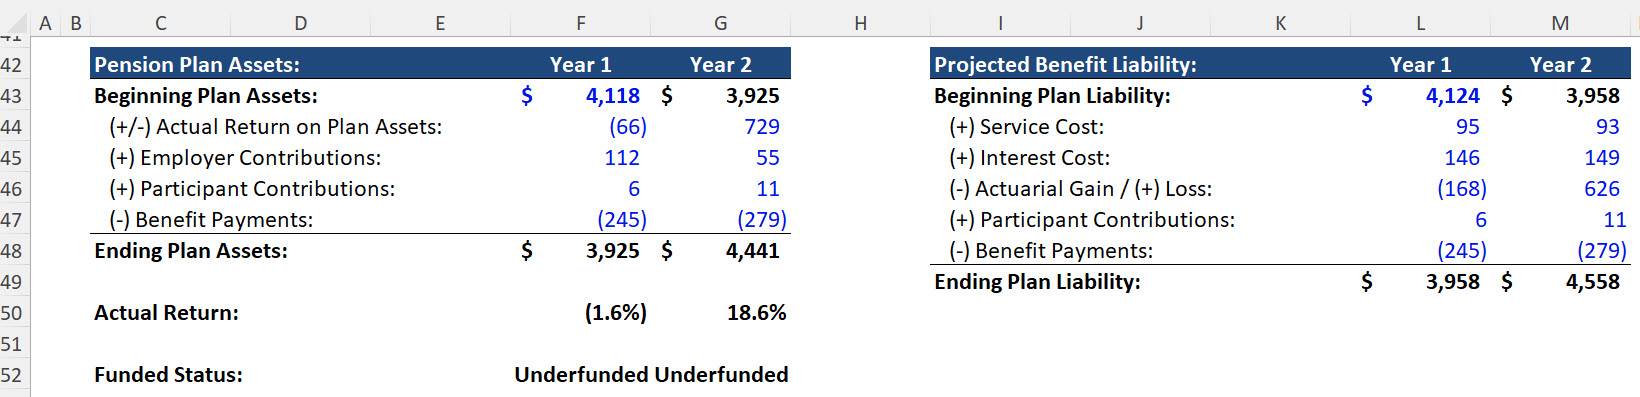
The Actual Return on Plan Assets, Employer Contributions, and Participant Contributions all tend to increase the Pension Plan Asset, while the Benefit Payments reduce it because the company sells some of its investments to pay for the employees who retire.
Meanwhile, the Pension Liability follows a different flow, though the “Participant Contributions” and “Benefit Payments” lines are the same.
These lines affect both the Pension Asset and the Pension Liability because as the employees contribute more, they’re also owed more in future payments, and Benefit Payments reduce both the company’s available funds and its future payouts.
The Service Cost here represents the additional cost accrued each year from employees staying at the company longer and receiving pay increases.
If an employee retiring at age 65 receives a paycheck for 1% * # of Years of Employment * Average Monthly Salary:
The Service Cost represents the aggregation of this increase each year for all current employees who will receive pension benefits in the future.
It is NOT a cash expense because it just represents the accrual of future payments owed to employees, but it is an operational expense.
The Interest Cost represents how the company moves closer to the payout of the full pension benefits each year, which increases the Present Value of the PBO.
For example, consider a future benefit payment to employees in Year 5. At a Discount Rate of 5%, here’s how the Present Value of this future payment changes each year:
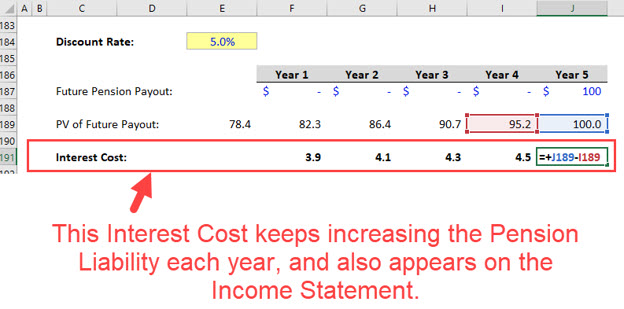
So, the Service Cost and Interest Cost both increase the Pension Liability as time passes.
The last remaining line item, “Actuarial Gain / Loss,” represents adjustments for payments that are above or below expectations (e.g., if the terms of the plan change, or the company’s performance allows it to pay more than expected).
The big idea is that the returns on Pension Assets (i.e., Gains and Losses) are volatile, so companies attempt to “smooth them out” on the Income Statement.
So, instead of recording the Actual Returns, companies record the Expected Returns based on a simple percentage assumption, such as 6% or 8% of the beginning Plan Assets.
Then, they amortize the difference between Actual and Expected Returns on the Income Statement.
If the difference between Actual Returns and Expected Returns shrinks, this Amortization shrinks; if the difference grows, the Amortization also grows.
While this practice makes logical sense, it also makes the Income Statement numbers completely divorced from the true cash expenses.
Here are the pension expense components that might appear on the IS:
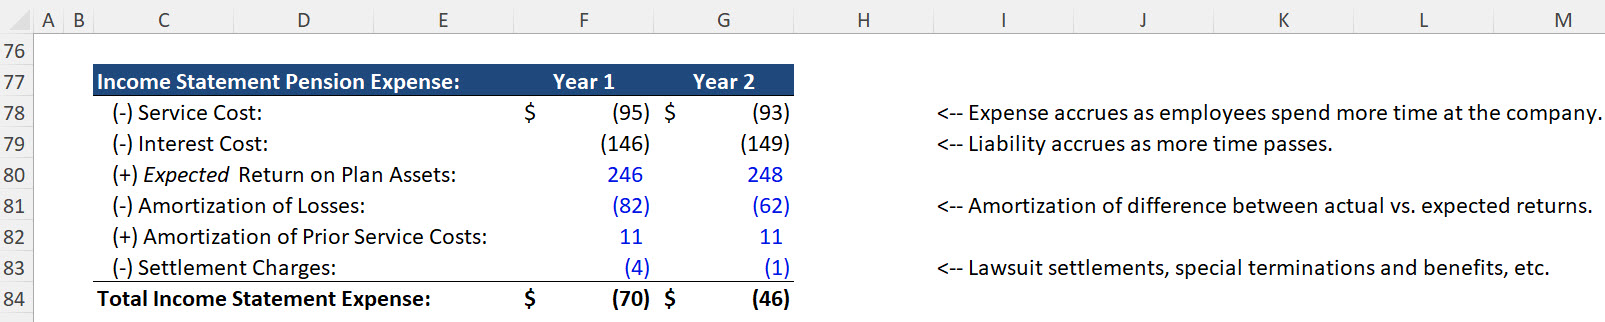
In theory, only the Service Cost should be an Operating Expense, but you will see deviations in real life.
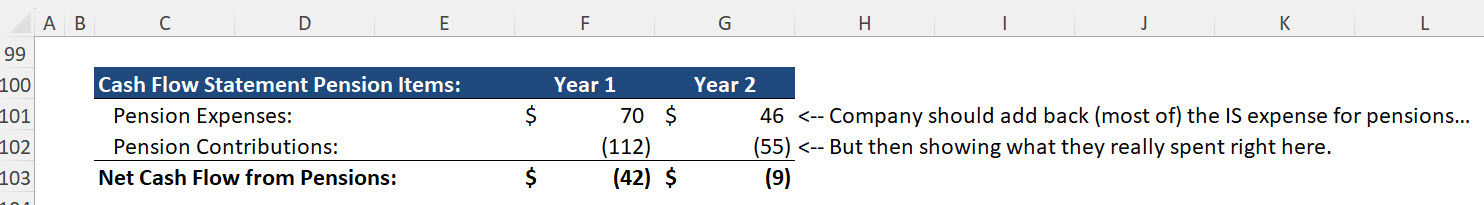
On the Cash Flow Statement, the company adds back the entire Pension Expense from the Income Statement because it’s ~100% non-cash, and it records a cash outflow for the Employer Contributions:
There will almost always be a Deferred Tax adjustment to account for the items that are tax-deductible vs. non-tax-deductible.
Due to this complexity, it’s difficult to “glance at” the financial statements and understand a company’s pensions; this is why we recommend simplifying as much as possible and sticking to the basic treatment above.
The Footnotes Analyst has a great article on pensions in a DCF, which presents several different treatment options.
We almost always recommend the first option they present, i.e., deduct only the Service Cost from Unlevered Free Cash Flow, add it back as a non-cash expense to capture the tax savings, and deduct the tax-adjusted Net Pension Liability in the Enterprise Value to Equity Value bridge at the end.
This makes the treatment consistent with the valuation multiples, so you do not need “separate versions” of Enterprise Value.
They also recommend adjusting WACC by counting pensions as another form of capital and recalculating it with additional terms, such as in this type of formulation:
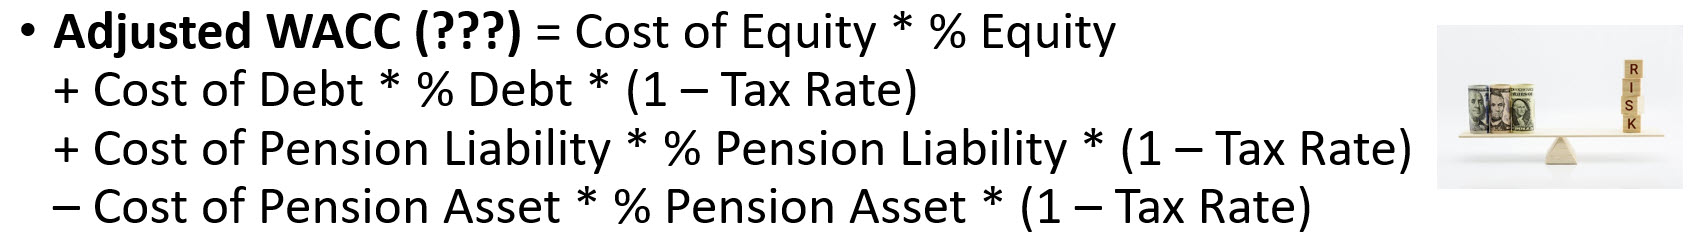
With this setup, the Pension Liabilities increase WACC, and the Pension Assets reduce WACC, so the net effect will be small if the pension is just barely underfunded.
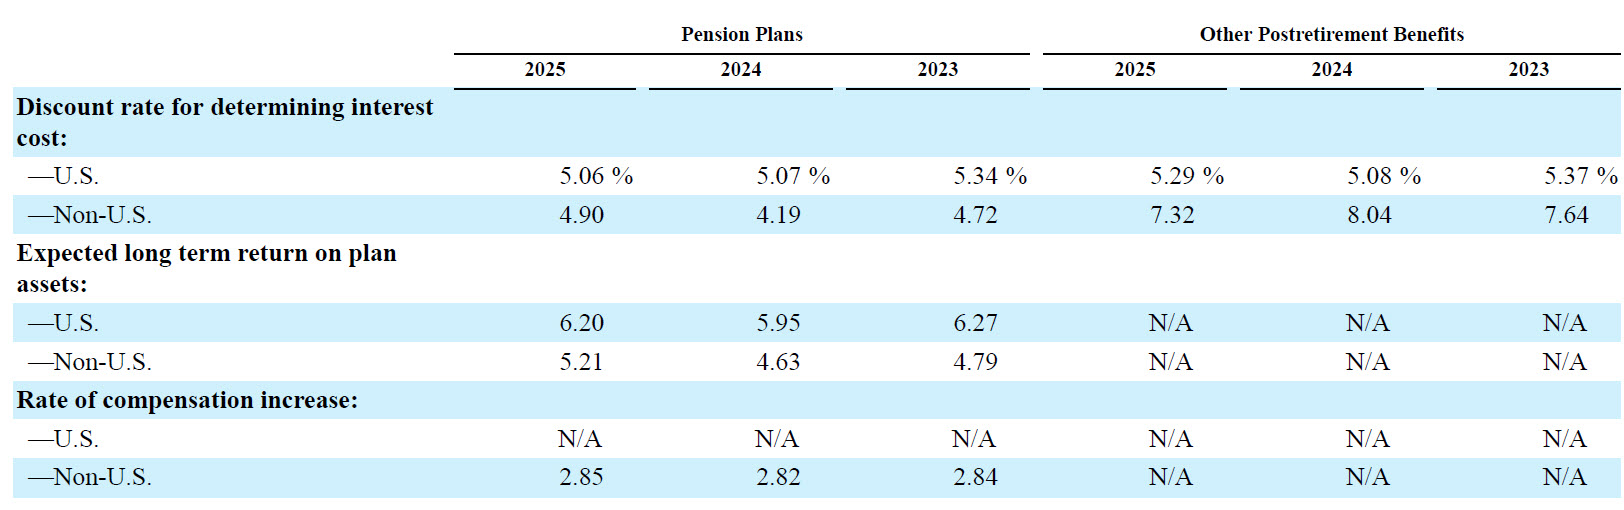
You could retrieve the Discount Rates for the Pension Assets and Pension Liabilities by looking up the targeted returns and current interest rates in the company’s filings:
While this approach makes theoretical sense, in practice, many banks do not use it and instead rely on the standard WACC formula.
Beyond these adjustments, some people also argue for adjusting the Pension Assets and Liabilities if the company seems to be misstating them.
For example, many companies understate their true Pension Liability by using low estimates for the Discount Rate or the average growth rate in employee compensation.
The list of possible adjustments goes on forever, but these points matter most when a company has substantial pensions that are significantly underfunded.
If the pension represents ~1% of a company’s Enterprise Value, none of this will shift the valuation output or an investment recommendation.
On the other hand, if an unfunded pension liability is 20 – 30% of the company’s Enterprise Value, you’ll have to spend more time and effort analyzing it and making these adjustments.
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.

