


About Brian DeChesare
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.
Midstream companies in the oil & gas sector transport and store oil, gas, fuel, and water; they operate like a cross between industrials, utilities, and infrastructure companies. Key metrics include the Capacity and Utilization Rates, Per-Unit Fees, Distributable Cash Flow, EBITDA, and Distributions, and the DCF and Dividend Discount Model are common valuation methodologies.
Midstream Oil & Gas
Midstream Oil & Gas Definition: Midstream companies in the oil & gas sector transport and store oil, gas, fuel, and water; they operate like a cross between industrials, utilities, and infrastructure companies. Key metrics include the Capacity and Utilization Rates, Per-Unit Fees, Distributable Cash Flow, EBITDA, and Distributions, and the DCF and Dividend Discount Model are common valuation methodologies.
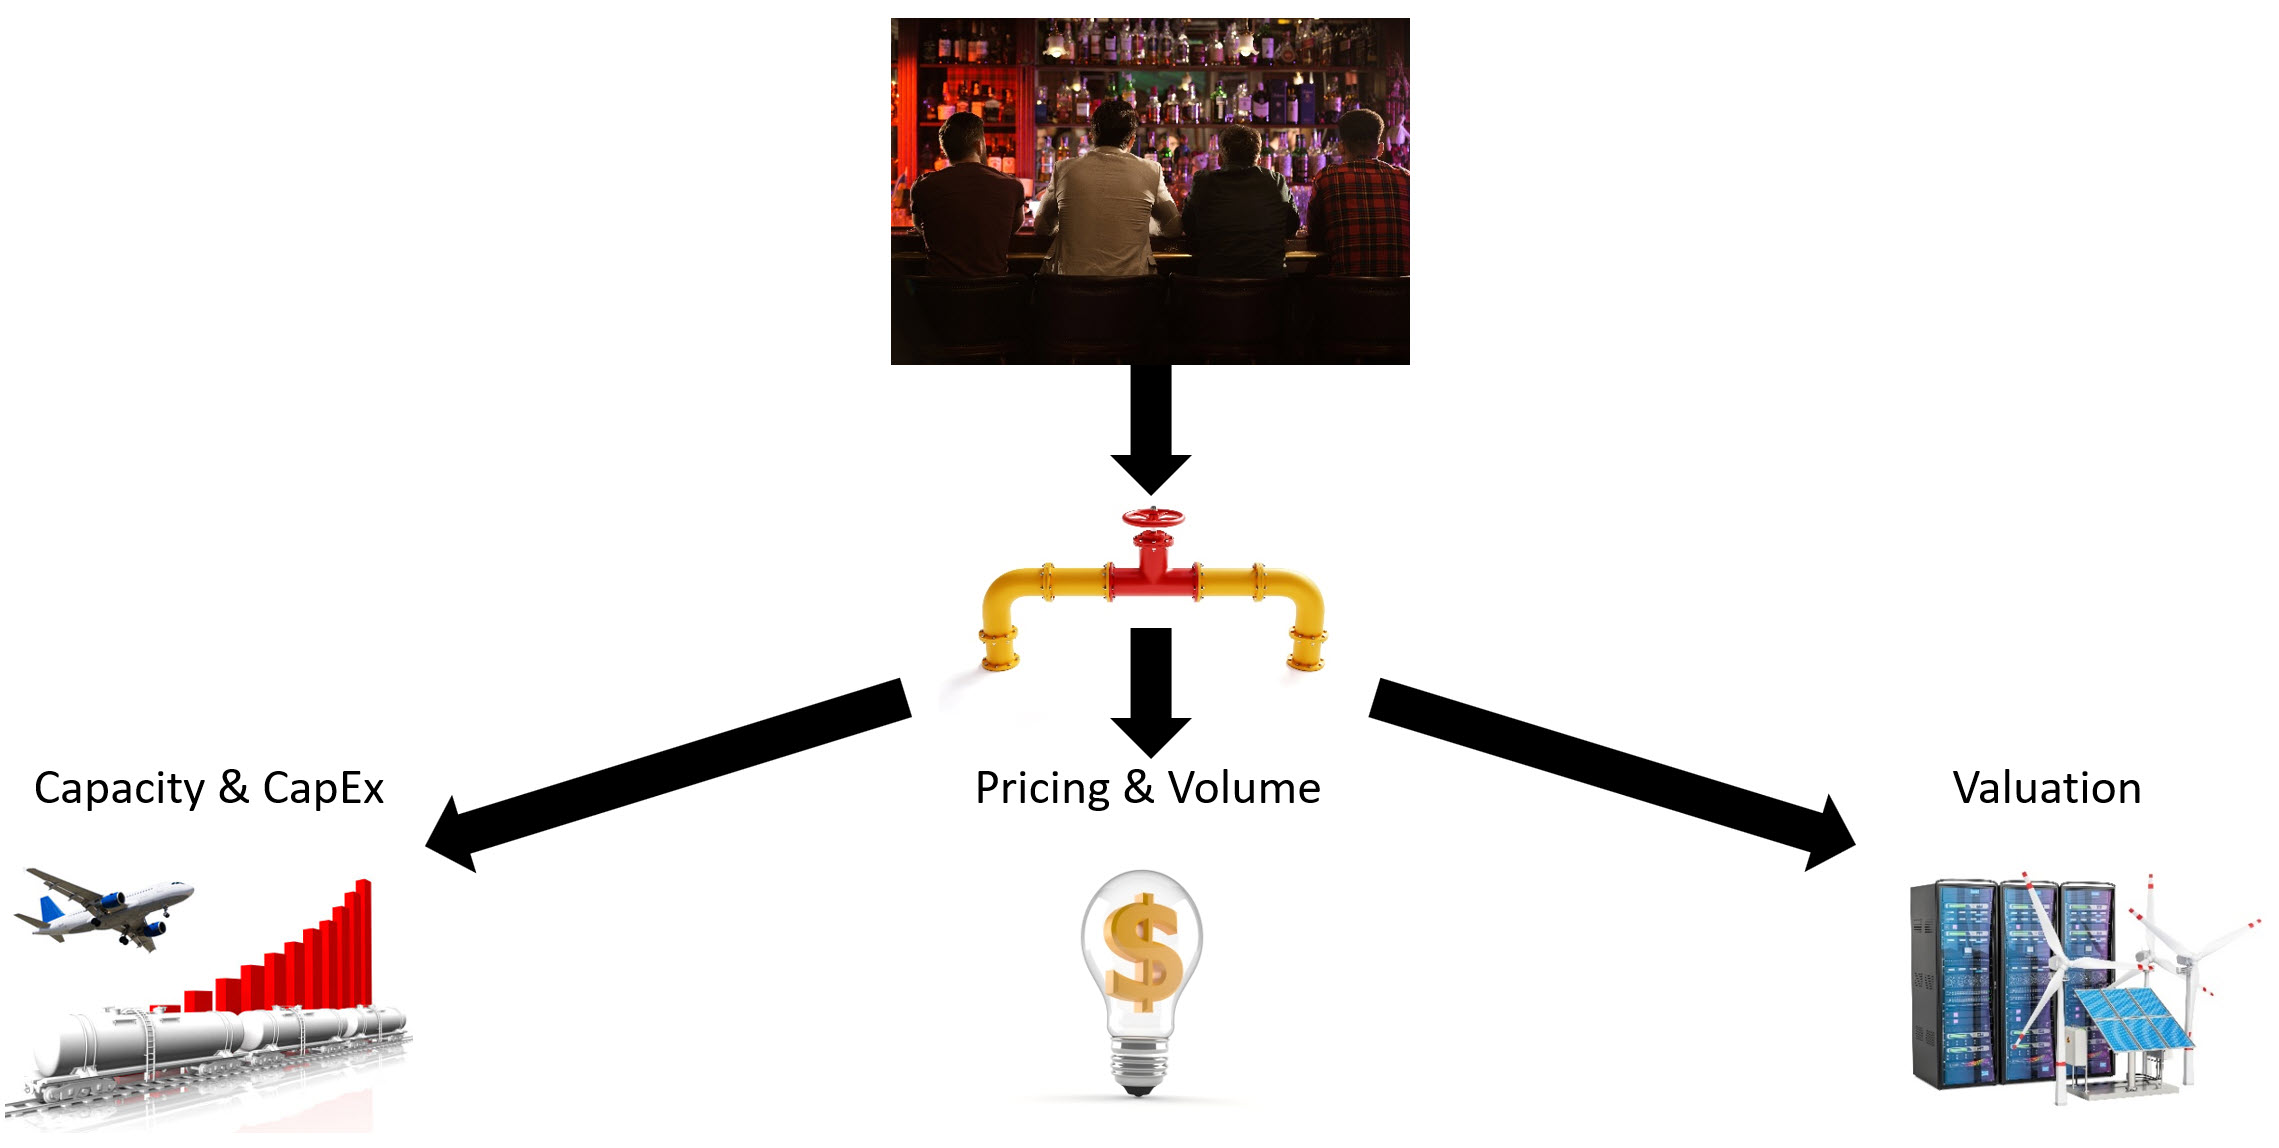
To understand the Midstream vertical, imagine if industrials, utilities, and infrastructure bankers hooked up after a raucous client dinner and had a baby.
This baby would look like an oil pipeline, and bankers would forecast its Capacity and Capital Expenditures as if it were an industrials company, with utilities-like assumptions governing its pricing and volume, and valuation coming from the infrastructure side:
In the U.S. and Canda, most independent Midstream companies operate pipelines that transport oil and gas.
In the rest of the world, independent pipeline companies are rare because pipelines are usually operated by the oil & gas super-majors (BP, TotalEnergies, etc.) or large, state-owned entities.
Therefore, “Midstream” in these regions usually refers to companies that transport oil and gas over the ocean (e.g., Frontline) or provide storage and transmission services (e.g., Fluxys Belgium).
These firms are closer to maritime / shipping companies, so their pricing, capacity, and utilization assumptions are more volatile.
In this tutorial, we’ll walk through Midstream analysis based on simplified models for DT Midstream and Western Midstream Partners.
These simplified examples come from more complex versions taught in our Oil & Gas Modeling course.
Midstream firms typically earn Revenue based on a “fee per unit transported/stored” model, and these fees are usually governed by long-term contracts that provide pricing visibility.
As a result, companies in this vertical are the least sensitive to commodity prices out of anything in oil & gas. However, “least sensitive” does not mean “insensitive.”
Commodity prices still affect them because higher prices mean that Upstream (E&P) companies are incentivized to drill and extract more, which means that transported volumes tend to increase.
But since these prices affect mostly the volume rather than the fees per unit, Midstream firms are less affected by commodity price volatility than Upstream or Downstream firms.
The standard Midstream business model for a pipeline or storage company looks like this:
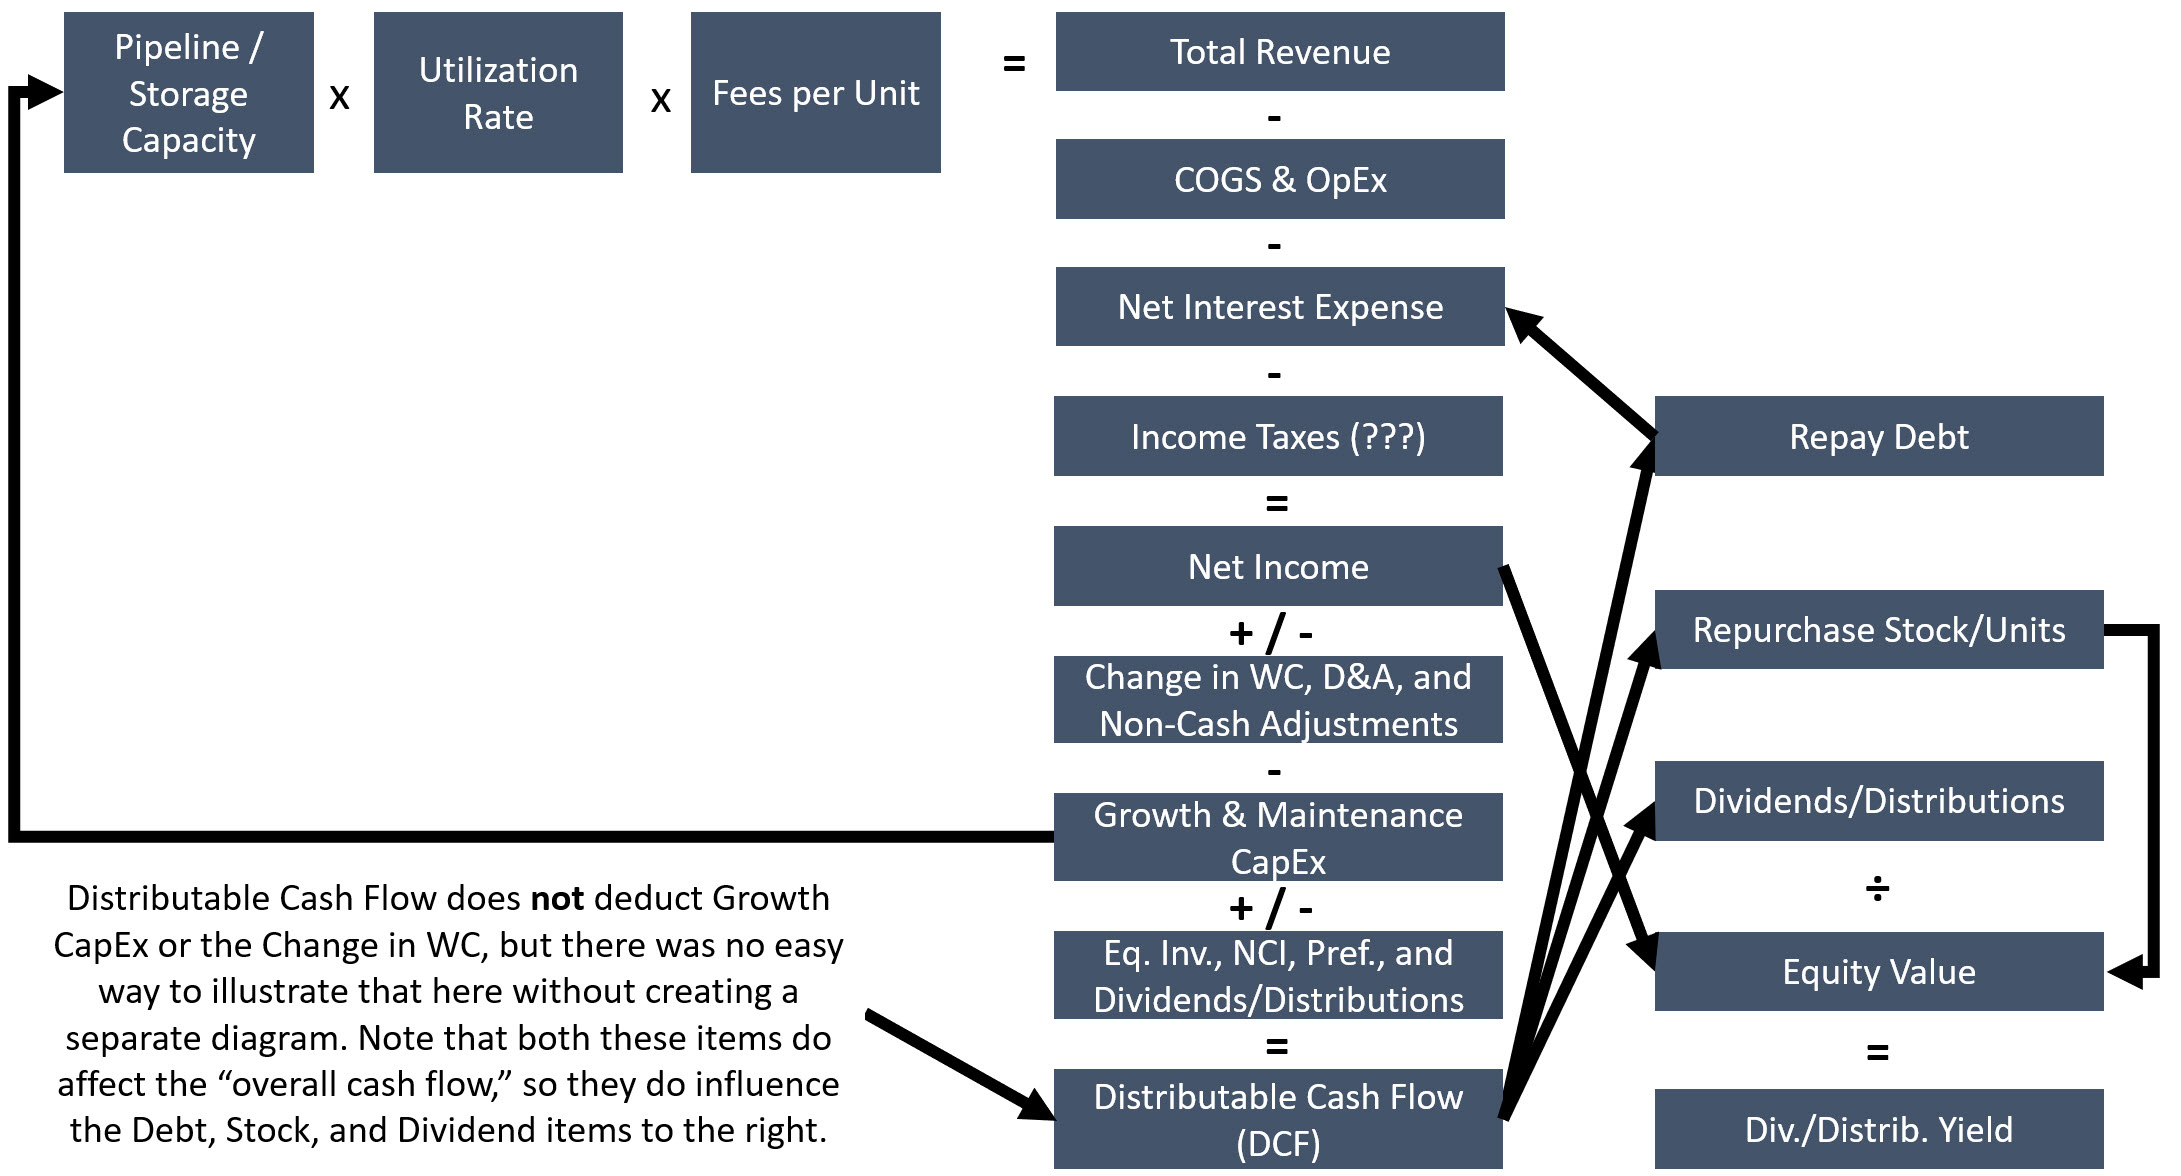
Many Midstream firms in the U.S. are structured as Master Limited Partnerships (MLPs), which are pass-through entities that pay no corporate-level taxes (or minimal taxes) and instead make Distributions to unitholders, who are taxed at their personal rates.
This corporate structure creates analytical complications because it means there are General Partners (GPs) that operate the firm and Limited Partner (LPs) that act as passive investors, similar to private equity funds.
The tricky part is that even if the LPs own ~98% and the GPs own ~2%, the Distributions or Dividends do not necessarily follow a 98% / 2% split, as it depends on the MLP terms.
MLPs have become less common over time as U.S. corporate tax rates have fallen, which is why one of the example companies here (DT Midstream) is a C-Corporation.
On the valuation side, most Midstream firms are considered infrastructure plays, so metrics like the Distributable Cash Flow (DCF) and Distribution Yield, defined as Distributions / Equity Value, are critical.
Since these firms tend to have very high margins, Distribution Yields of 8 – 10% or higher are plausible.
You can still use EBITDA multiples and a standard Unlevered DCF to value Midstream firms, but alternatives based on Distributions or Dividends are also common.
To create Midstream forecasts, you normally start by gathering the historical data on the company’s Capacity, Throughput, and Per-Unit Fees, which are sometimes disclosed in confusing ways (e.g., Western Midstream Partners discloses the Gross Margin per Unit, but not the Revenue per Unit).
You can then assume percentage growth rates and utilization rates based on historical trends, management commentary, and your own research:
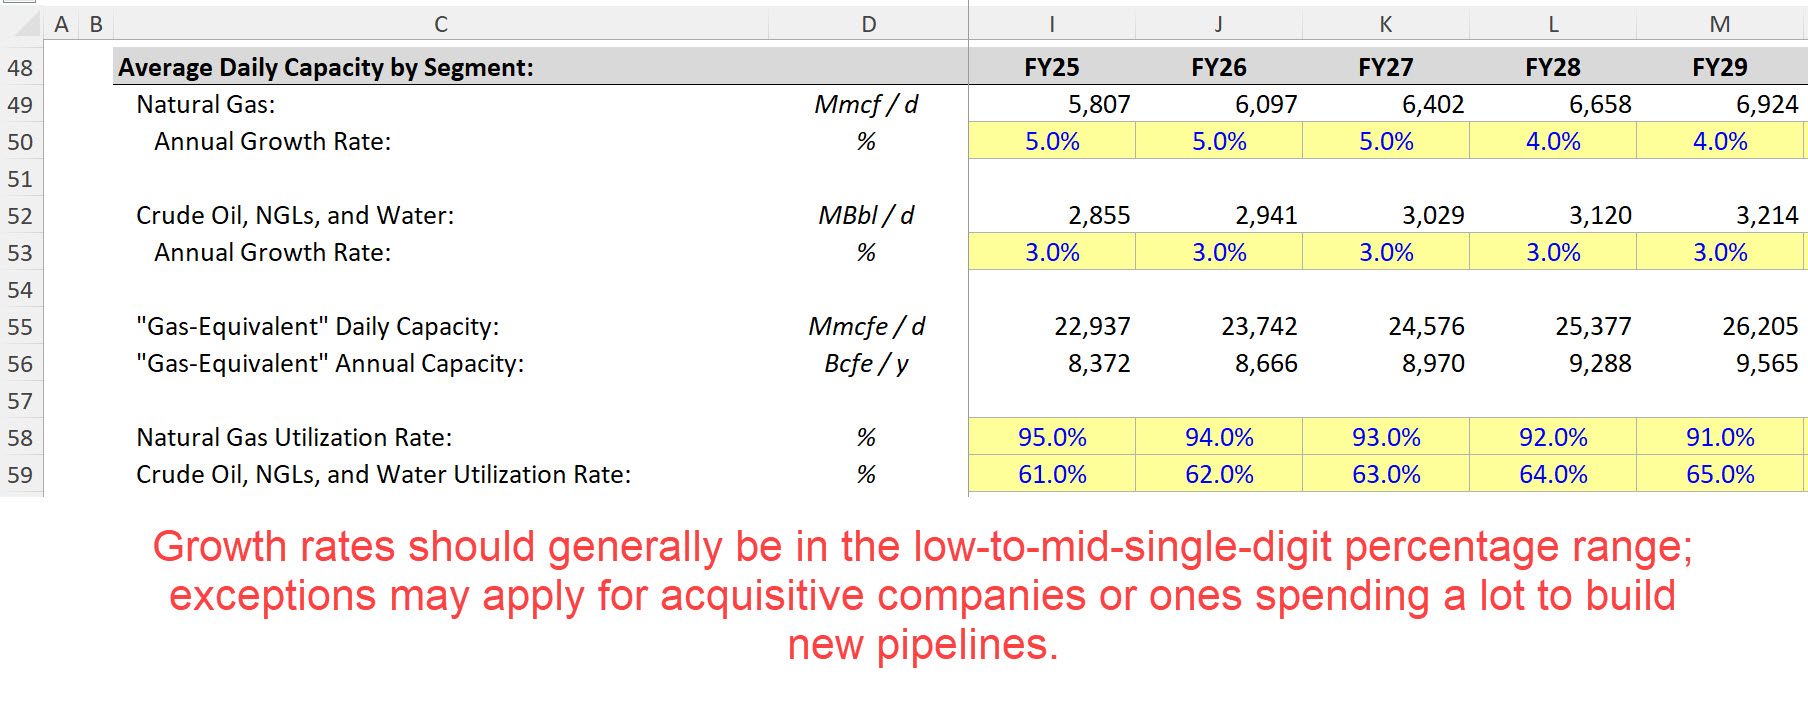
You then multiply the Daily Capacity by the Utilization Rate to get the Daily Throughput, and you multiply that by 365 or 366 to get the Annual Throughput.
Next, you make assumptions for the Fees per Unit. If the company discloses the terms of its contracts, you can use that information, but if not, it’s safest to follow the trends and management estimates.
The growth rates should be low percentages, in-line with inflation in most cases, because Midstream companies have little pricing power:
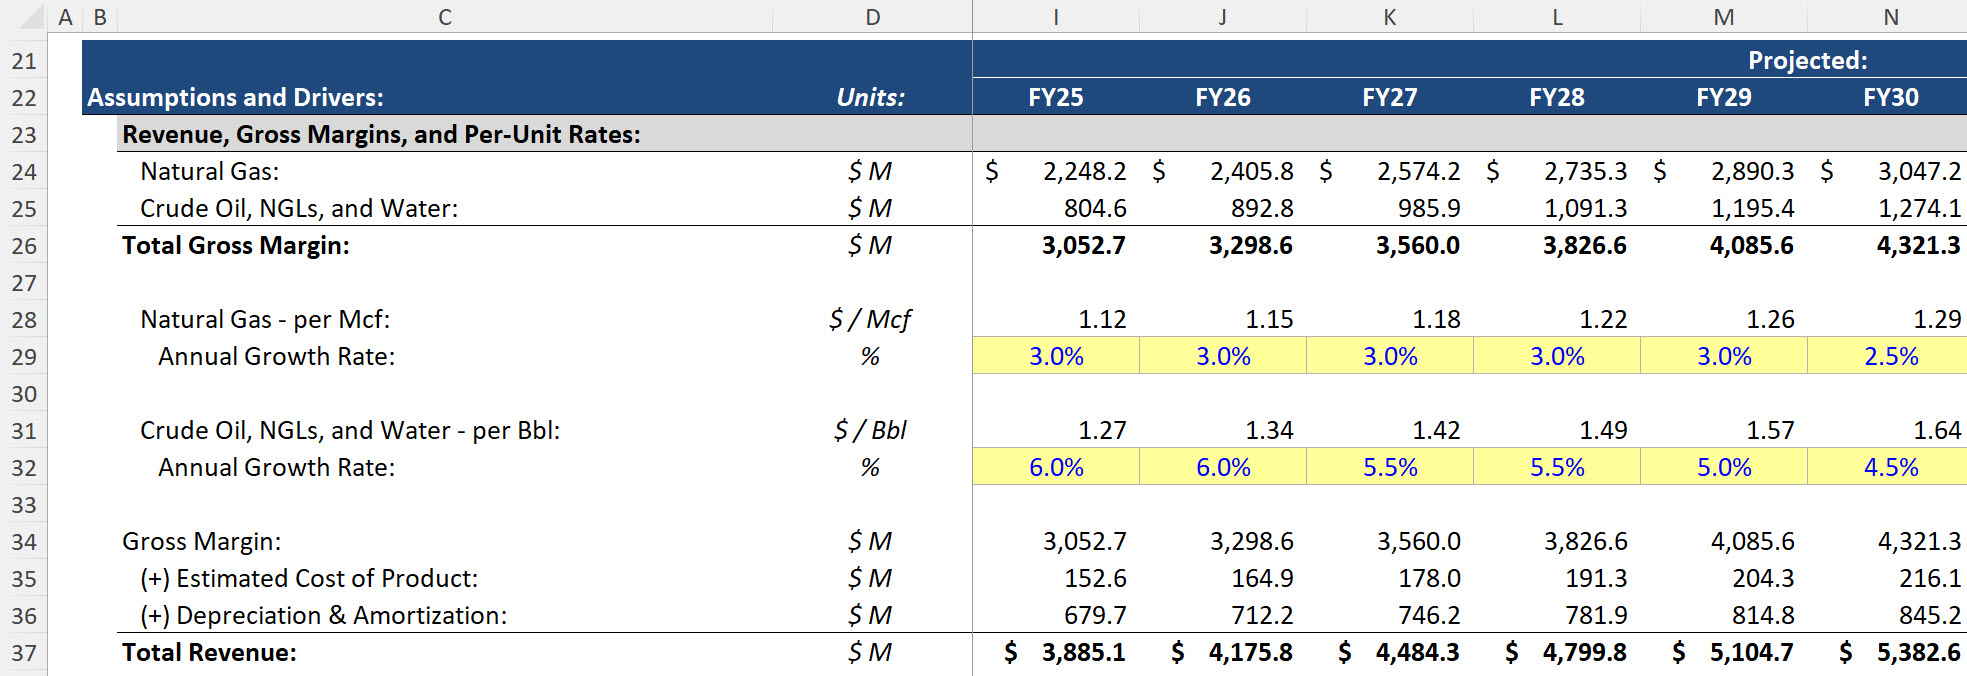
The D&A is projected based on $ / Capacity figures, and the Cost of Product is a simple percentage of the “Gross Margin” (the company’s disclosures require you to back into these numbers).
All Midstream companies spend significant amounts on CapEx, with the mix allocated to Maintenance, Growth, and “Other” / Corporate purposes.
The tricky part is that not all companies disclose the percentages in useful ways, so you normally must settle for rough estimates.
For example, WES lists the following in its investor presentation:
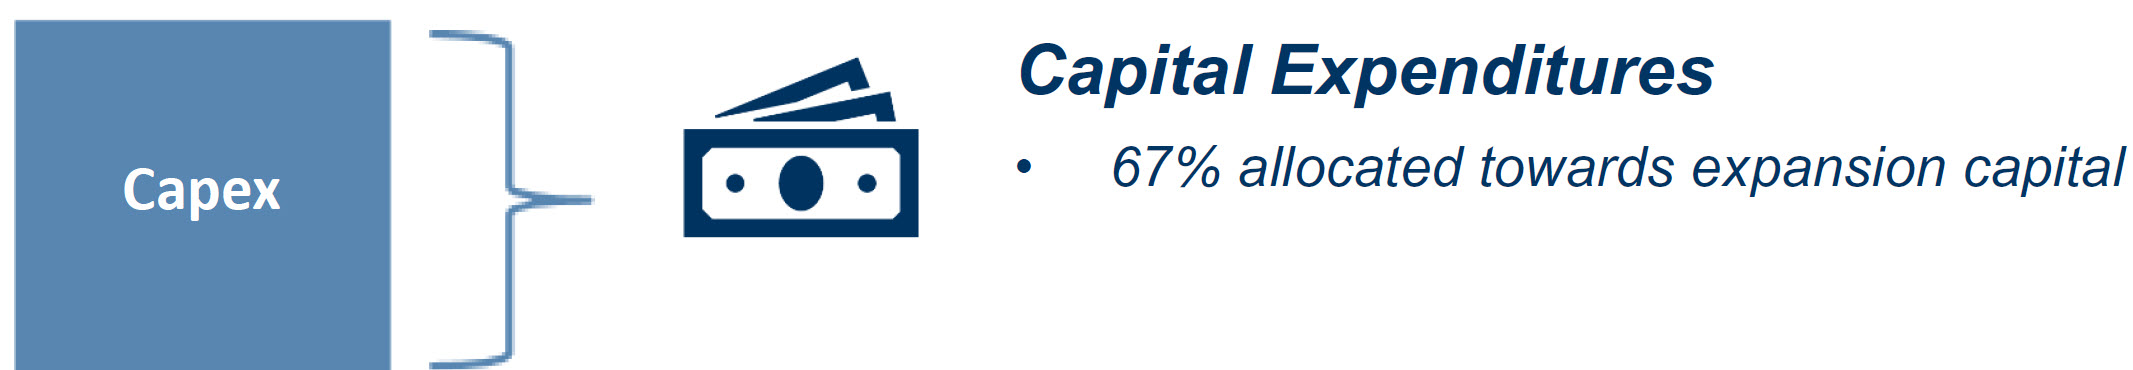
Based on this estimate, you can split up the historical CapEx and assume that 1/3 is for Maintenance/Corporate and 2/3 is for Growth each year.
You can then create “Maintenance CapEx per Total Capacity” and “Growth CapEx per Capacity Growth Unit” metrics and build projections based on these and the annual Capacity growth:
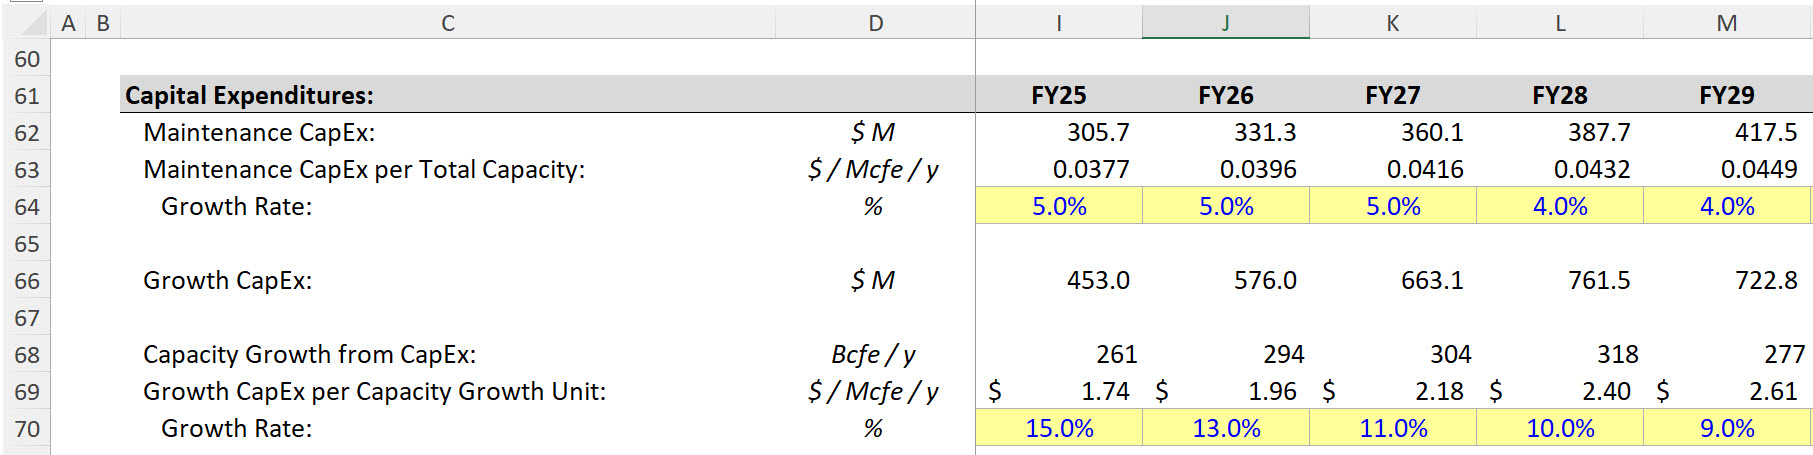
Since CapEx is vital, you should make sure that metrics like CapEx / Revenue and Growth CapEx / Total CapEx say in consistent ranges over time.
Technically, you do not need anything beyond these simple cash-flow projections to value a Midstream company.
But if you want to go beyond this, the rest of the financial statements are similar to any other 3-statement model.
Most other Income Statement line items can be forecast as percentages of Revenue, the Working Capital items on the Balance Sheet link to Revenue and Expense lines the normal way, and the Cash Flow Statement has the standard line items.
To determine the Debt issuances / repayments and Stock issuances / repayments, you normally set a “Minimum Cash” level and compare the pre-financing Cash to this Minimum.
If the Cash exceeds the Minimum Cash, use some of the excess to repay Debt and repurchase Stock; if it does not, issue more Debt or Stock to offset this deficit.
The Dividends or Distributions are simple percentages of Net Income or Distributable Cash Flow (DCF), which is normally defined as:
These “other groups” represent different types of partial ownership in other assets or the Midstream firm itself.
If you do not have full 3-statement projections, you can forecast lines such as Distributable Cash Flow and Cash Interest Expense based on simple percentages of Operating Income or EBITDA, but this is not ideal for a robust model:
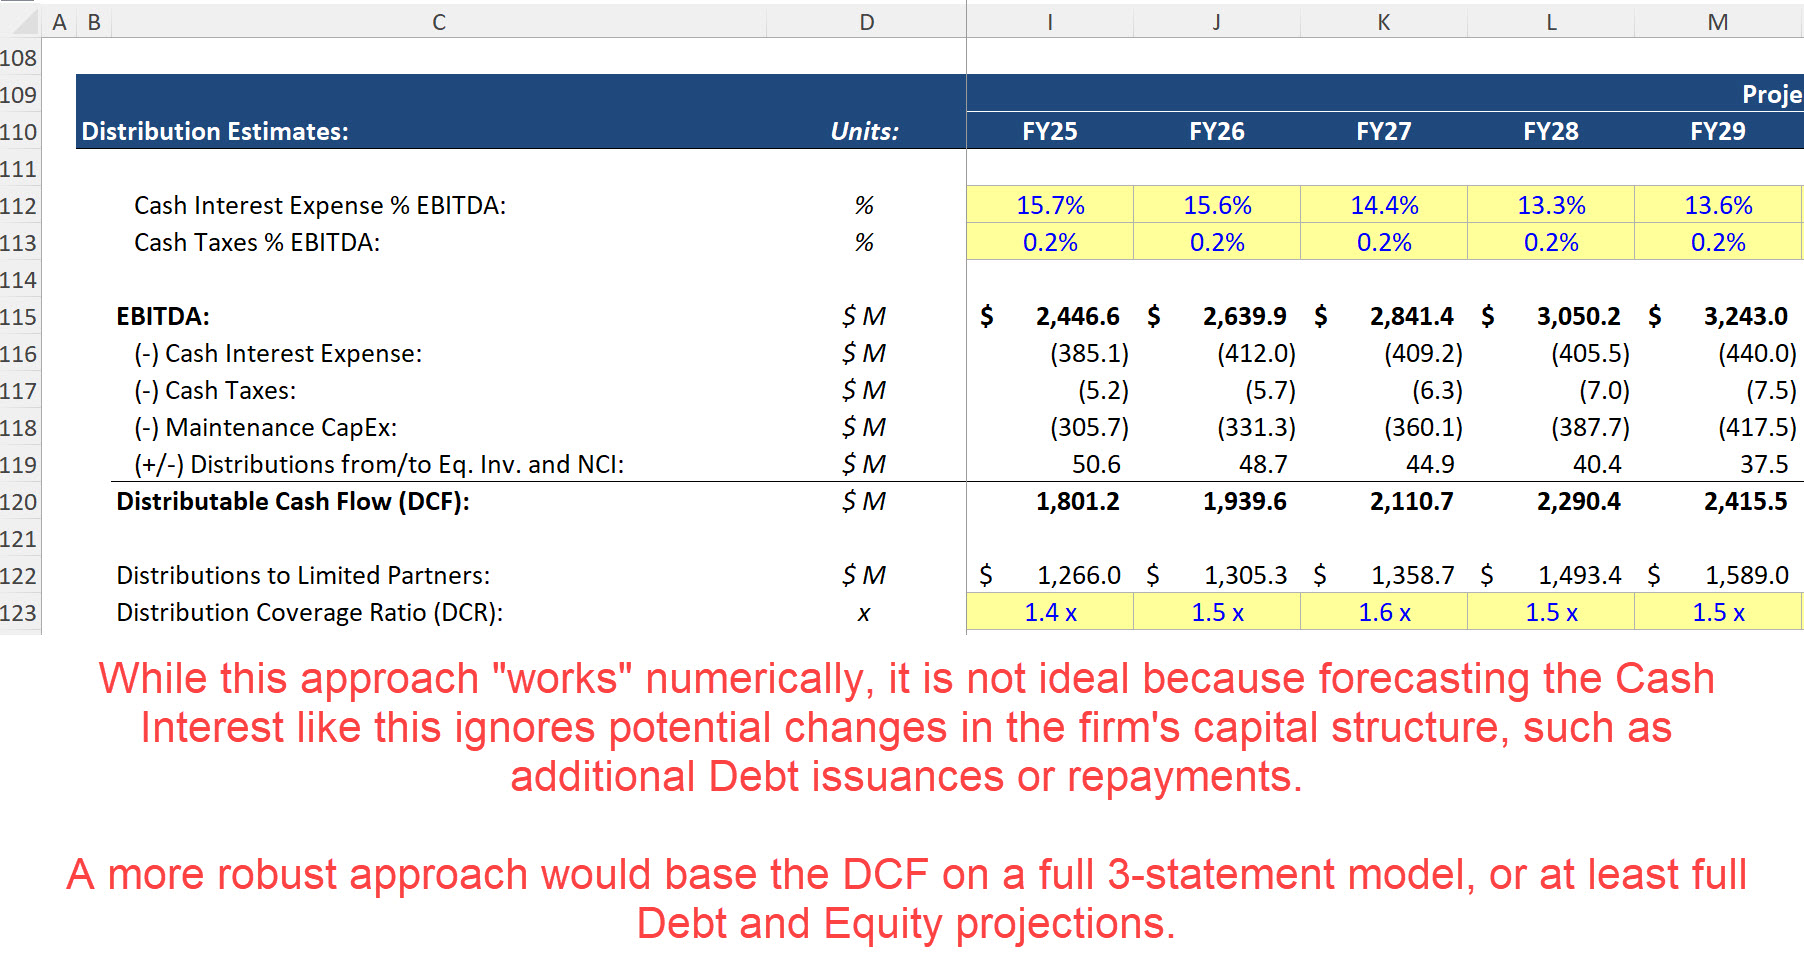
Infrastructure valuation is all about cash flows and distributions, and so is Midstream valuation.
EBITDA-based multiples and the standard Unlevered DCF are common approaches in both fields, even though EBITDA is quite different from “cash flow” in most cases.
If you have a 3-statement model or cash-flow estimates, you can also incorporate metrics and multiples based on Distributions and Distributable Cash Flow.
These metrics give you a better sense of what the equity investors will earn in cash; the disadvantage is that they’re less useful for comparing different companies due to differences in tax rates, capital structure, and capital intensity.
You screen for Midstream Public Comps and Precedent Transactions based on the same geographic, industry, and financial criteria as always (plus “time” for the transactions).
For example, in the full Western Midstream Partners valuation, we use:
Here’s a summary of the valuation multiples:
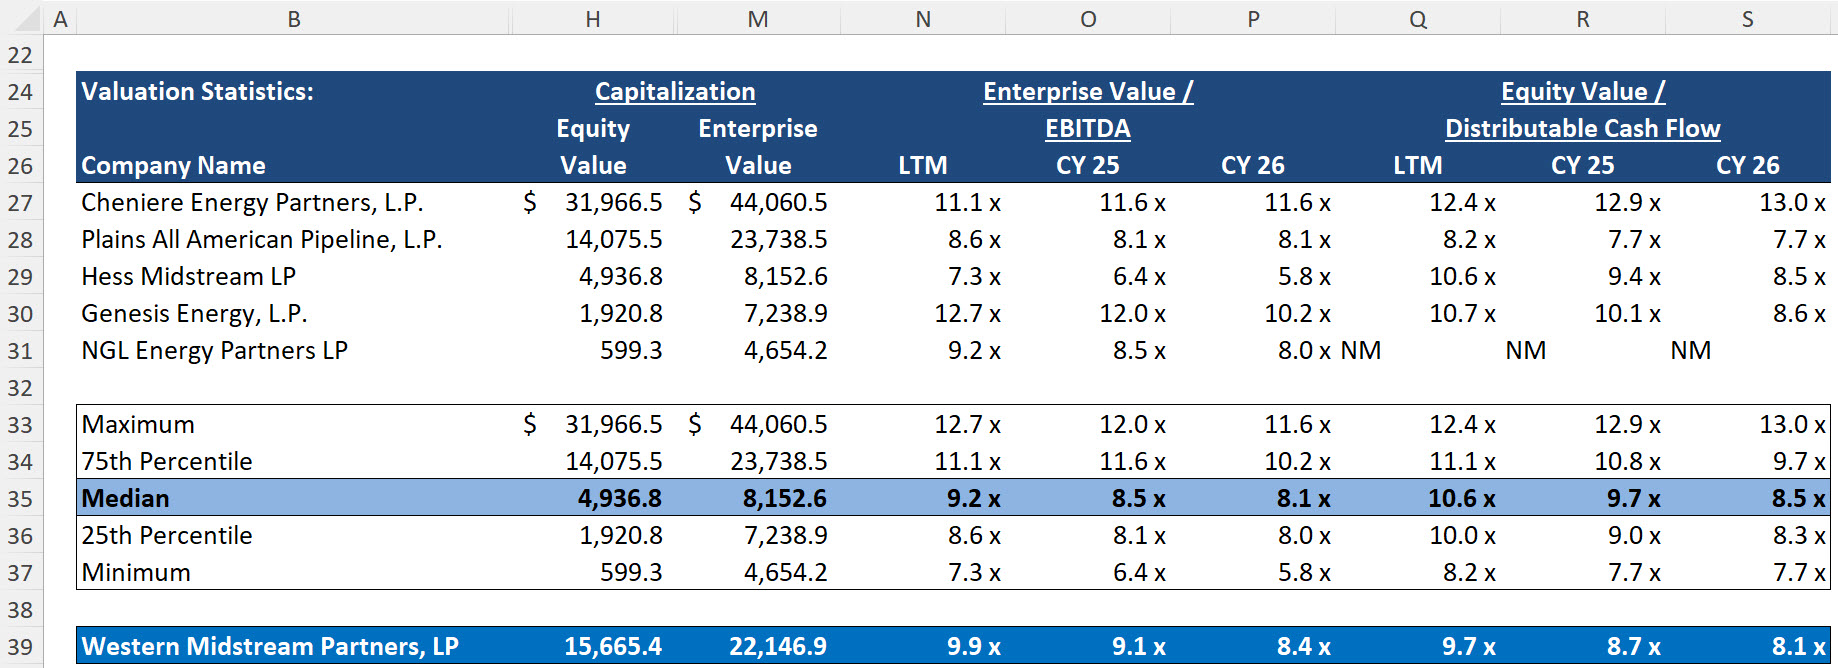
Some adjustments may be required for the GP / LP structure.
Also, companies tend to define Distributable Cash Flow inconsistently, so you might need to create your own definition and apply it to all the companies in your set, “overwriting” their own numbers.
You could also use the Distribution Yield, similar to the Dividend Yield for normal companies, as a valuation metric and quasi-multiple.
Another difference in both the Public Comps and the Precedent Transactions is that you often focus on forward metrics and multiples, such as EBITDA and DCF in the next fiscal year or next two years.
Since Midstream is a “yield-based industry” with predictable cash flows, investors often buy in based on their expected distributions over the next few years.
We’ve covered the Dividend Discount Model extensively in the separate tutorial for DT Midstream, so you should refer to that for the details and full walkthrough.
When you’re valuing MLPs, the “Dividend Discount Model” is often renamed to the “Discounted Distribution Analysis” (DDA) because these firms technically issue Distributions rather than Dividends, but the setup is the same.
If you already have 3-statement or cash-flow-level projections, the DDA/DDM should extend directly from these forecasts.
You start by taking the Revenue, Expenses, and CapEx numbers from those forecasts and using them to calculate the Distributable Cash Flow:
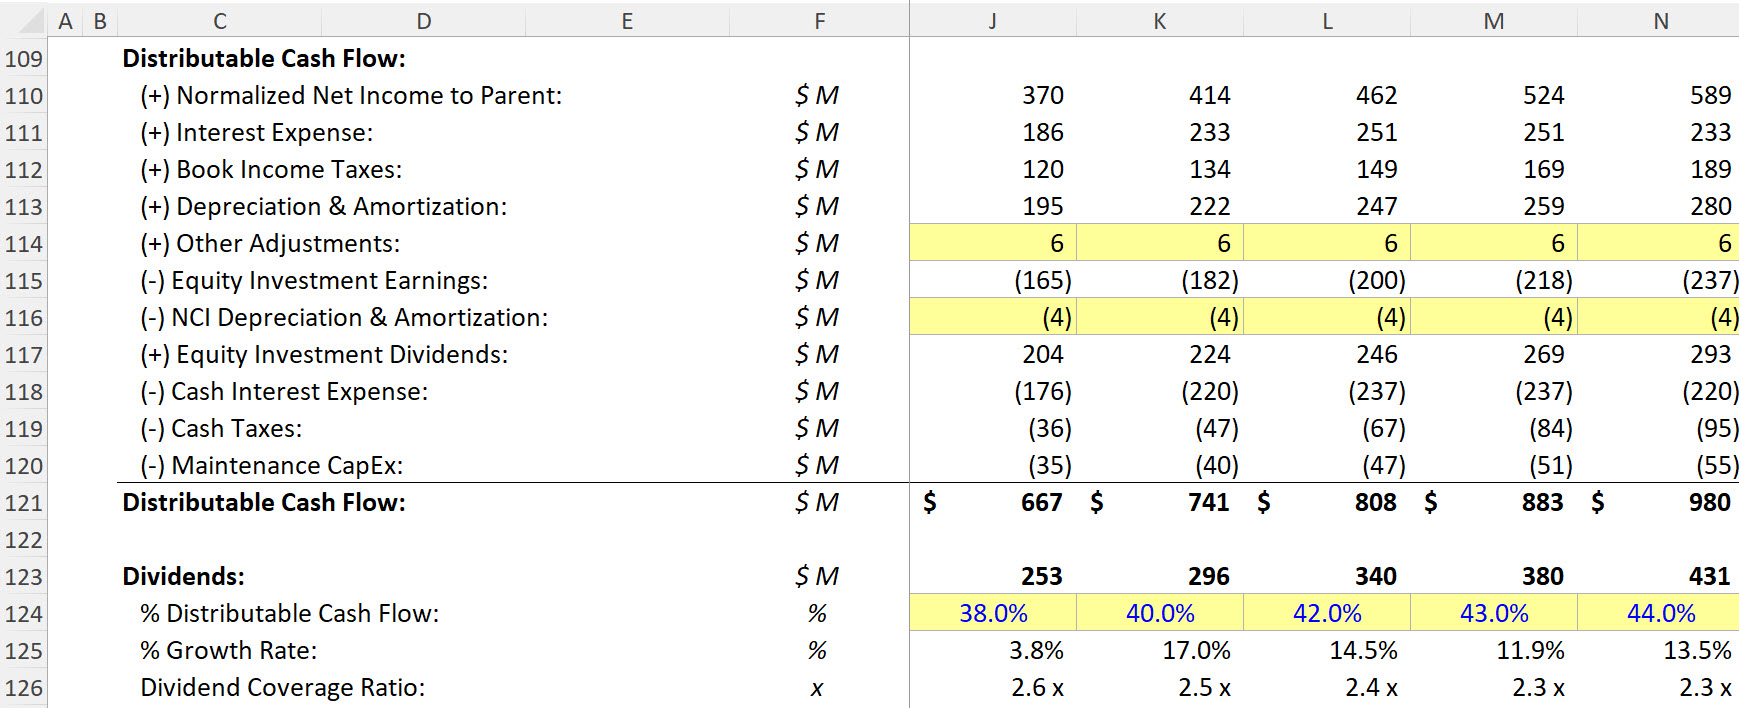
Then, you make the Distributions a percentage of this number, also factoring in possible capital structure changes and how they’ll affect the Net Interest Expense.
For example, if the company needs to issue more Debt to raise its Cash level, its Net Interest Expense in the period should increase.
Once you’re done, you discount all the Dividends based on the Cost of Equity, calculate the Terminal Value, discount that based on the Cost of Equity, and add up everything to get the company’s Implied Equity Value.
This Terminal Value calculation should be linked to an Equity Value-based multiple, such as P / E or Equity Value / Distributable Cash Flo; you could also use the Perpetuity Growth Rate method.
There is no “bridge” because the model calculates the Implied Equity Value directly.
You calculate the Cost of Equity in the same way for Midstream companies, though you could potentially use the Projected Dividend Yield + Dividend Growth Rate method to cross-check your results.
The Discounted Cash Flow Model, which, confusingly, shares the same abbreviation as the “Distributable Cash Flow” (DCF), is still based on Unlevered Free Cash Flow.
The main differences vs. the DDA/DDM are as follows:
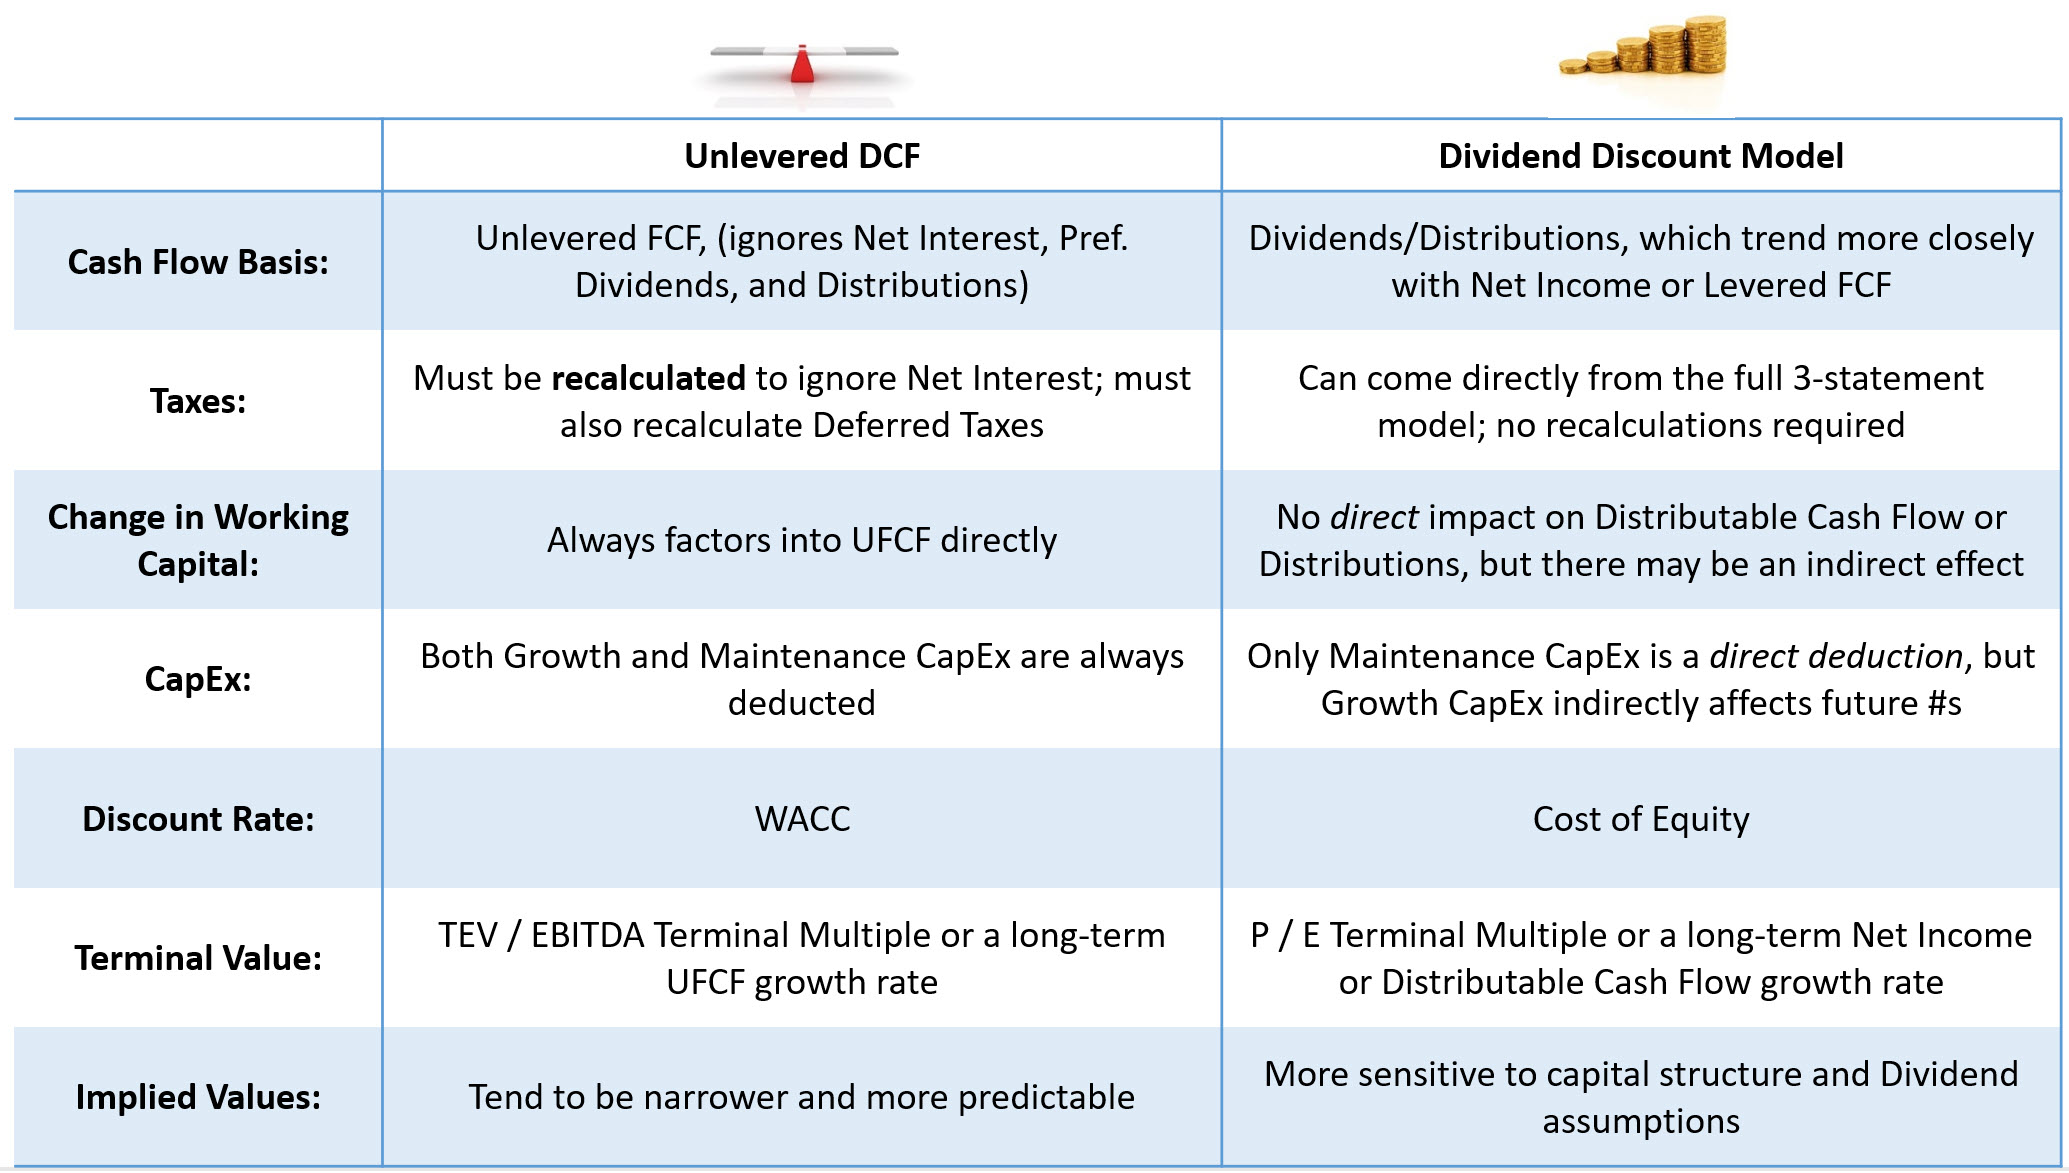
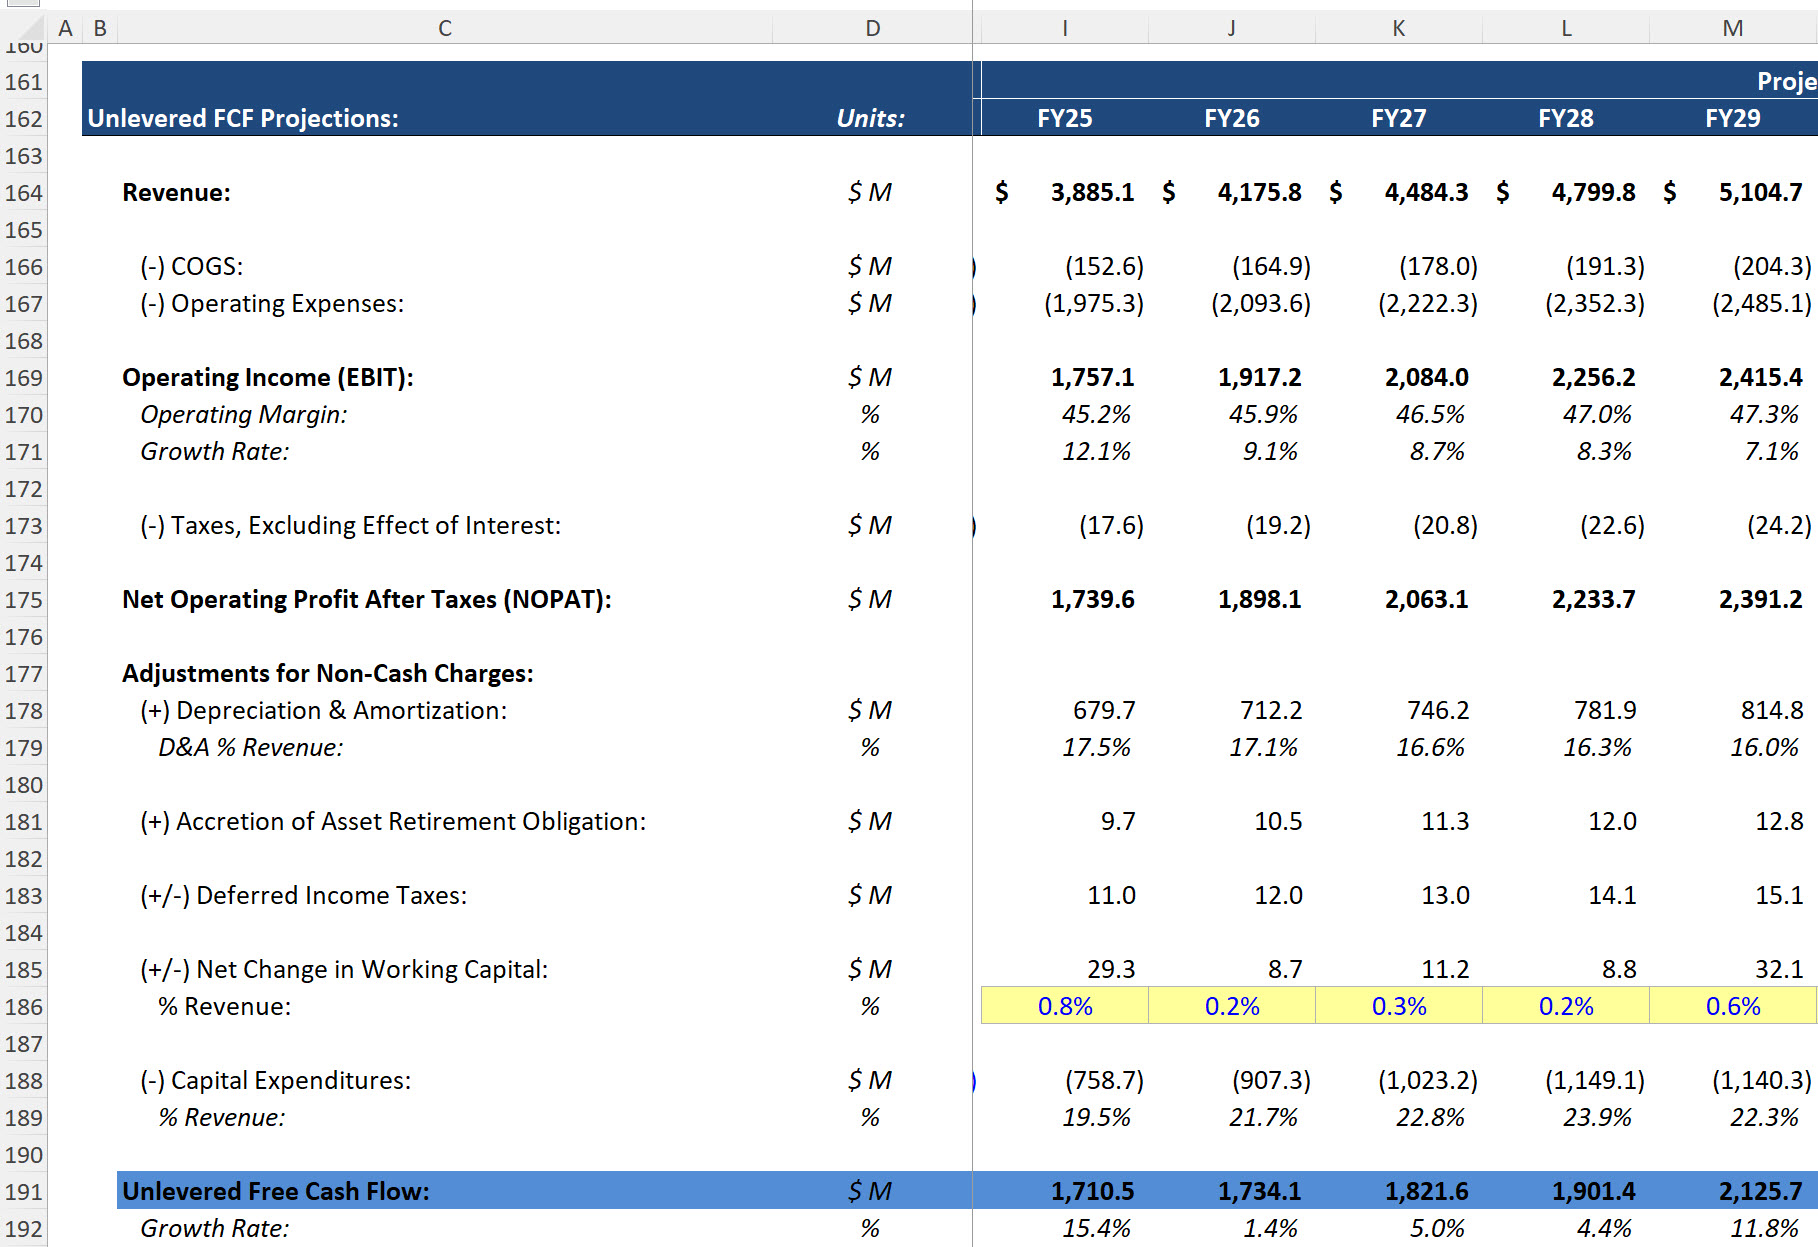
You can see many of these differences in the Western Midstream Partners DCF setup below:
When you interpret the results of a valuation, you must be careful to account for points like differences in the targeted Distributions.
For example, Western Midstream Partners here seems to be quite undervalued based on the DCF and DDA:
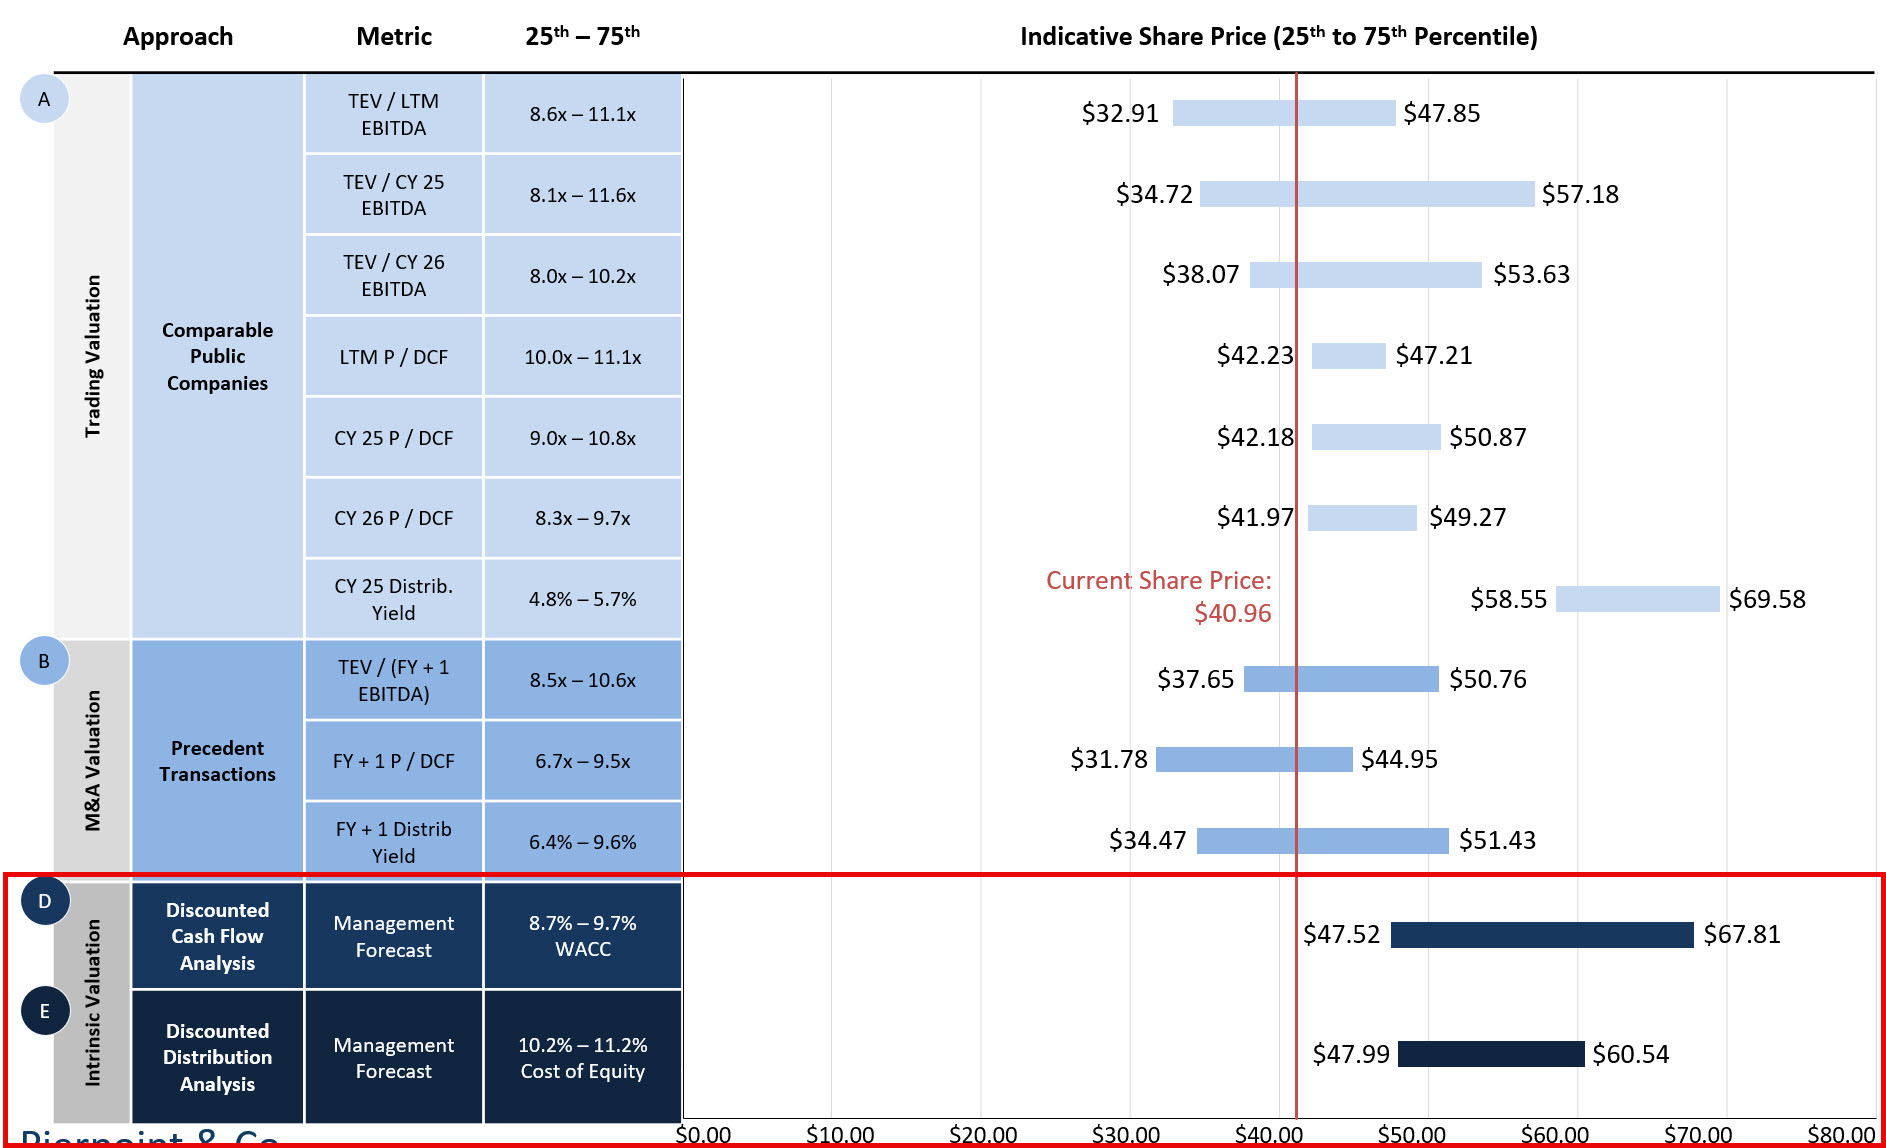
But that’s mostly because it distributes a much higher percentage of its cash flow than the peer companies, so its Distributions are unnaturally high.
If you assume lower payout percentages, the valuation looks more reasonable.
If you look at independent “Midstream” companies in other parts of the world, they often operate more like traditional transportation/logistics companies within the industrials sector.
A few of the key differences include:
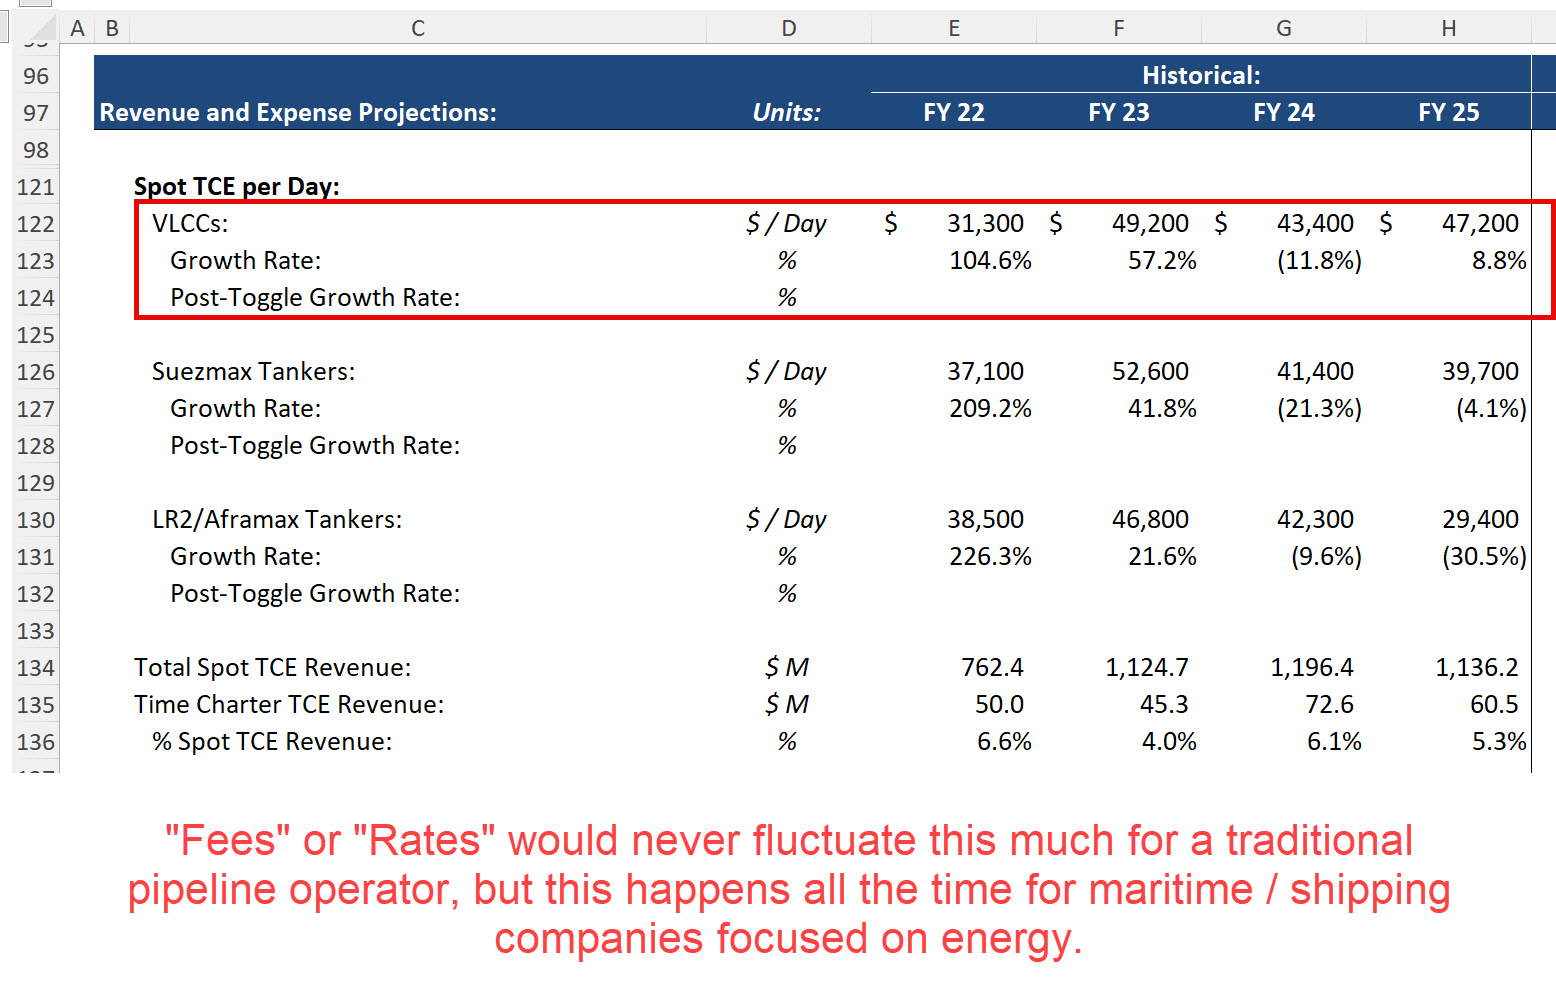
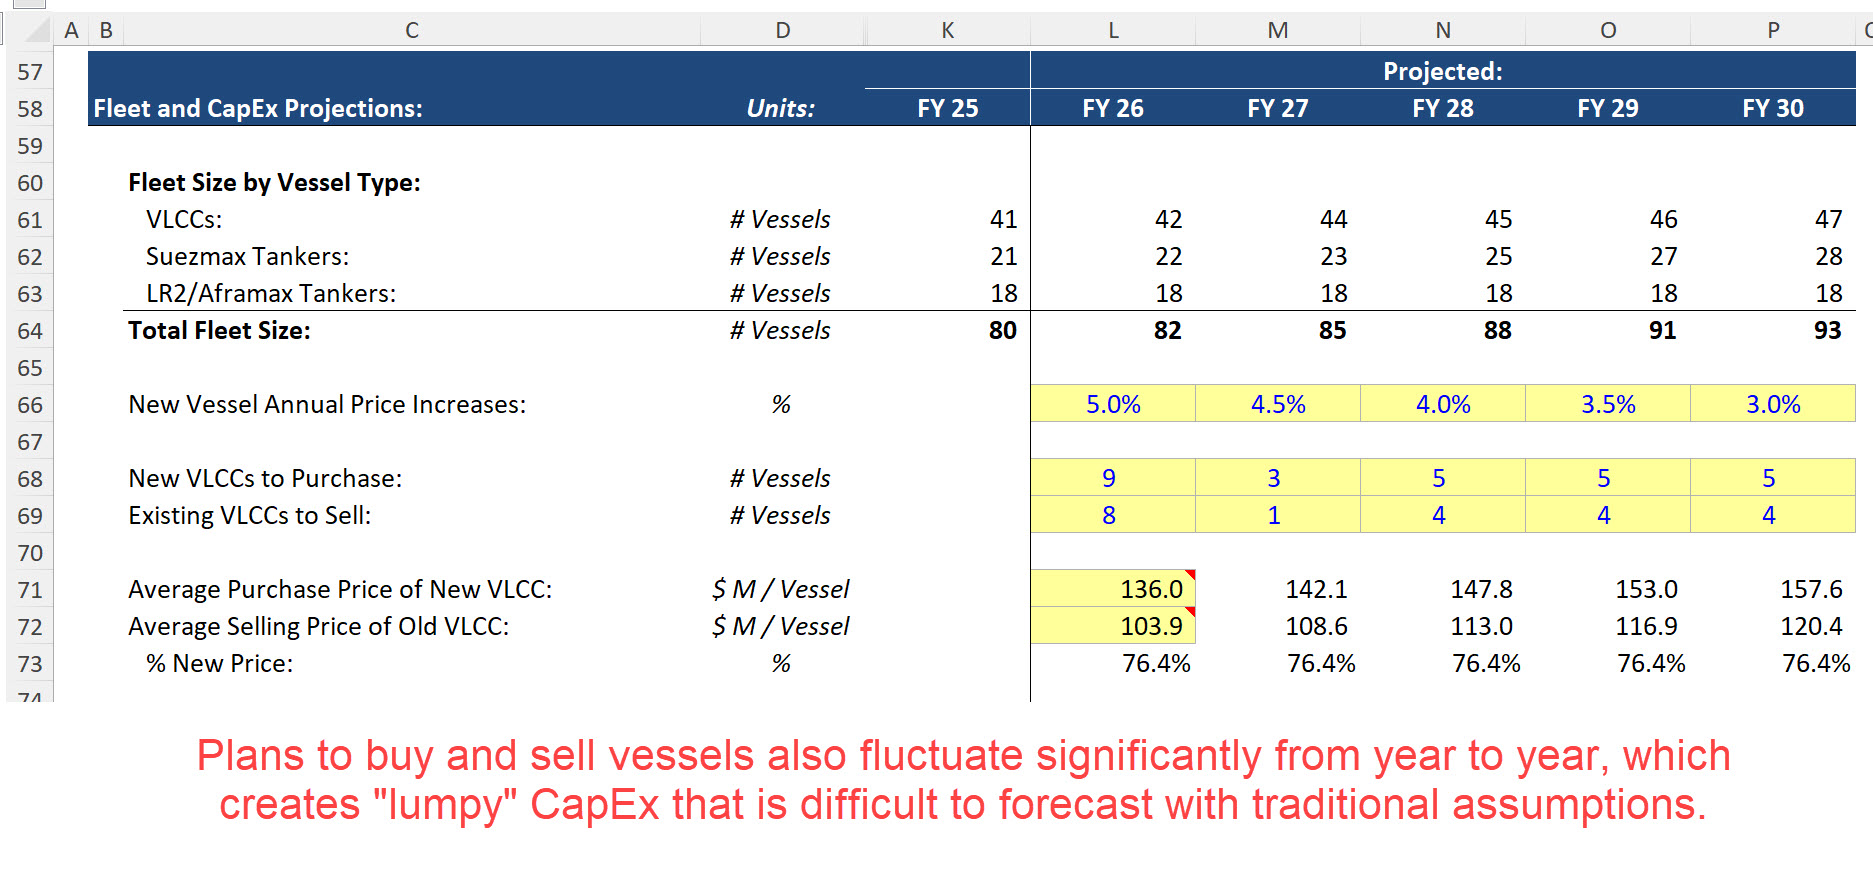
The corporate tax rate is often quite low or even ~0 for these companies, even though the MLP structure does not exist in other countries – because many of these firms are based in tax havens, such as Cyprus, Malta, or Monaco.
You can still use EBITDA multiples and a standard DCF to value maritime firms, but the Dividend Discount Model is more questionable, as is anything linked to “Distributable Cash Flow.”
Yes, you can calculate these metrics, but they’re less meaningful because the Dividends and cash flows are far less predictable.
These metrics are most useful when the companies involved resemble infrastructure assets with power purchase agreements (PPA) or similar contracts governing long-term prices.
When prices are locked in, production volumes can be reasonably estimated, and the capital requirements are known upfront, the cash flows tend to be predictable.
But as companies and assets move into “unpredictable” territory, forecasts based on distributions and cash flows become less reliable.
At the minimum, you should use lower multiples and higher Discount Rates for companies in this category to reflect the added risk.
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.

