


About Brian DeChesare
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.
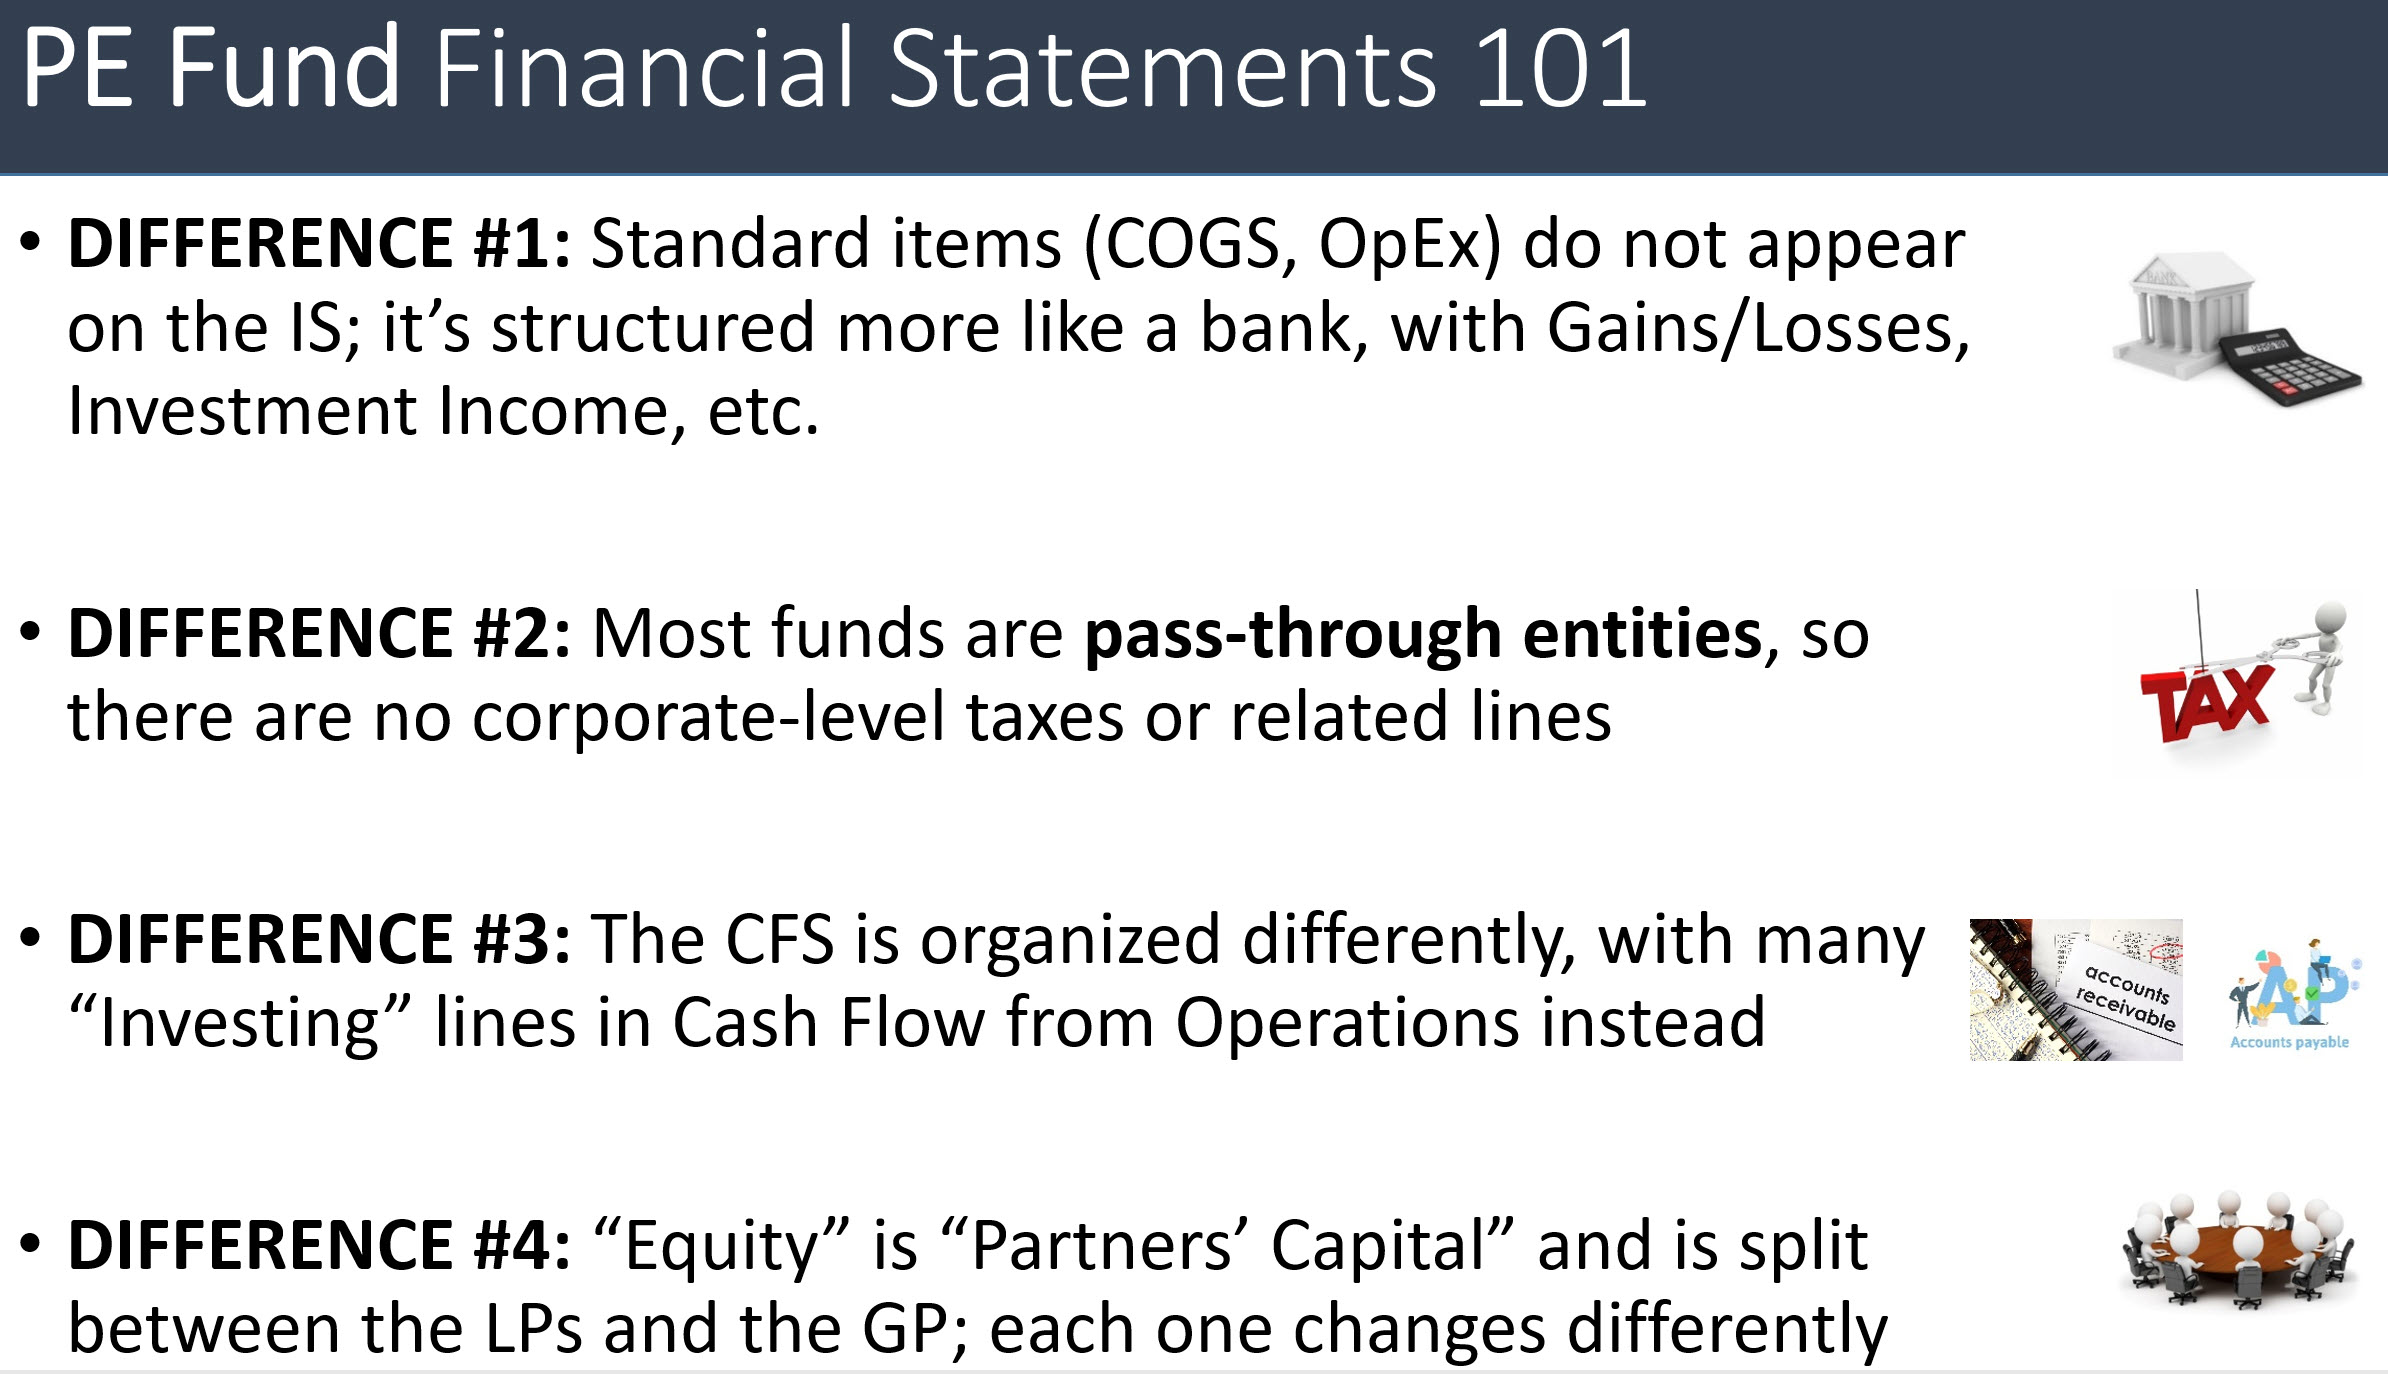
PE funds use the same financial statements – the Income Statement, Balance Sheet, and Cash Flow Statement – as normal companies, but the individual line items differ, there are typically no corporate-level taxes, the CFS is set up differently, and Equity is split between the Limited Partners (LPs), and General Partners (GPs).
Private Equity Fund Financial Statements Definition: PE funds use the same financial statements – the Income Statement, Balance Sheet, and Cash Flow Statement – as normal companies, but the individual line items differ, there are typically no corporate-level taxes, the CFS is set up differently, and Equity is split between the Limited Partners (LPs), and General Partners (GPs).
In the context of case studies for funds of funds and secondaries roles, a private equity fund’s financial statements are not that important.
If you interview for one of these roles, any case study will most likely be about evaluating a fund’s performance or a specific deal, not building a 3-statement model for the fund.
However, for interview purposes, it is still good to know about fund-level financial statements because you could easily get questions about them.
You can get a simplified example of a PE fund 3-statement model below and more explanations of the formulas, but here is the short summary:
The hardest part of a PE fund’s financial statements is not the projections or linking but translating portfolio companies into specific line items.
For example, it can be especially challenging to determine the Unrealized vs. Realized Gains and Losses unless you are given detailed information.
The sample file here presents a simplified view of the statements, but the real-life versions are significantly more complex.
To begin building a set of financial statements for a PE fund, you need a schedule of the fund’s investments, unrealized portfolio company values, and realizations (i.e., the values of companies the fund has sold).
Ideally, you’ll get year-by-year information for each portfolio company:
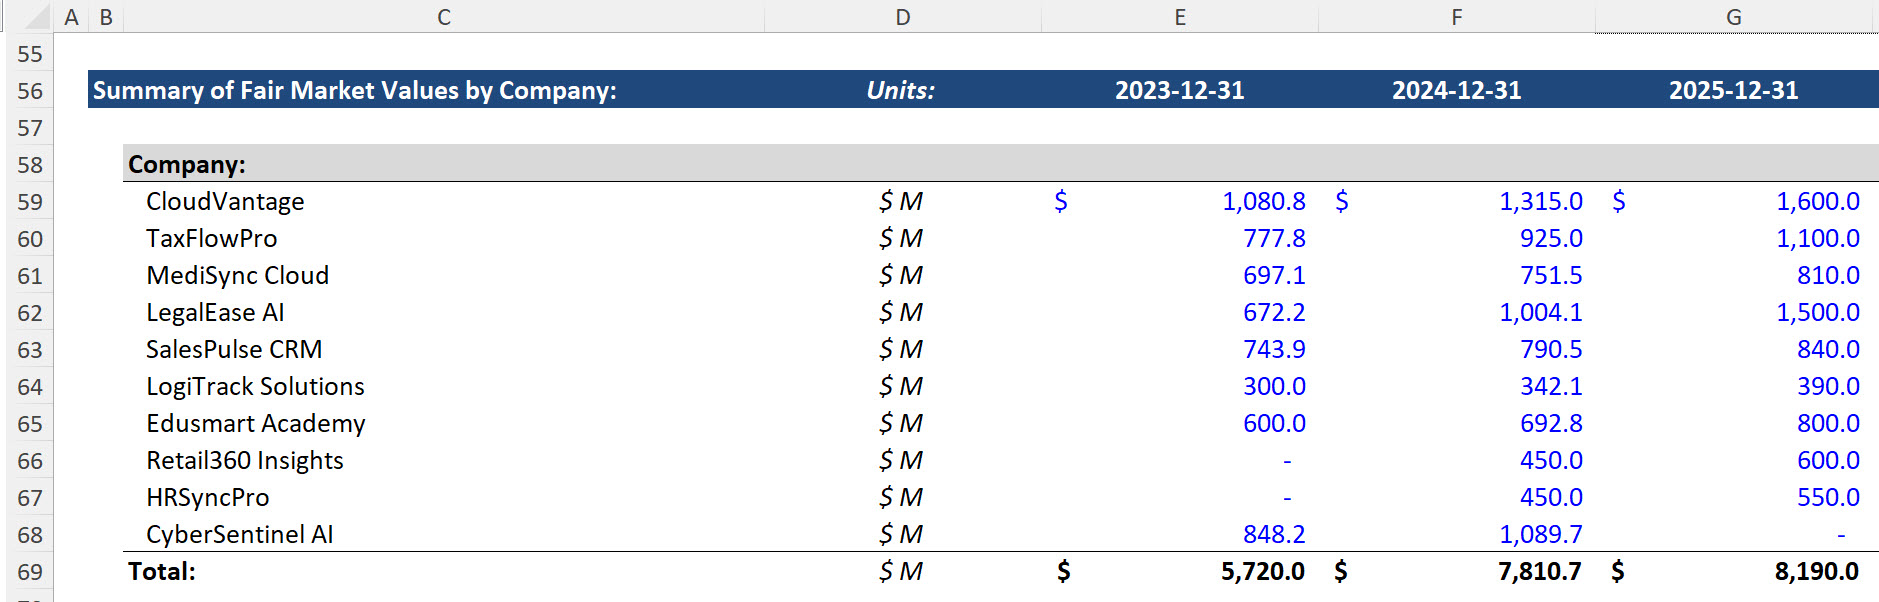
But you may only have access to much higher-level information, such as the total investments, unrealized values, and realizations, without attribution to specific companies:
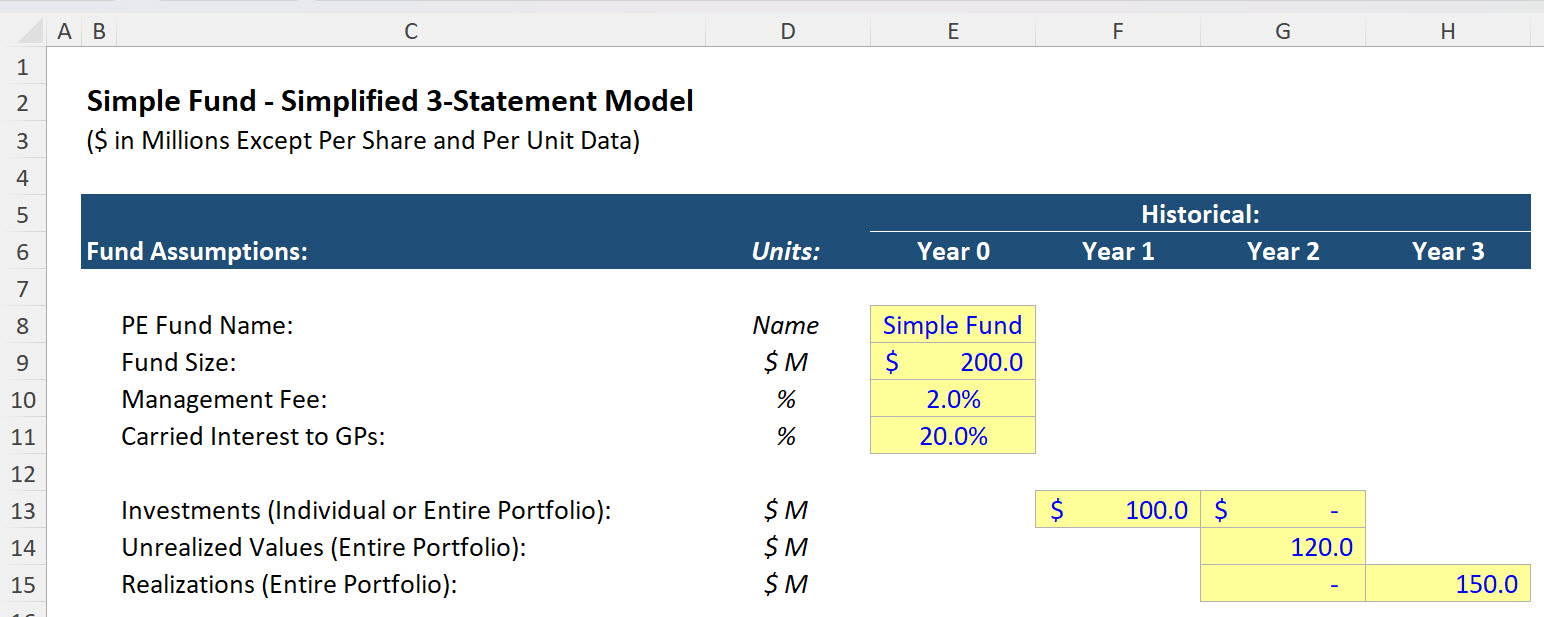
In a case like this, the logic is reasonably simple if you constrain the allowed inputs:
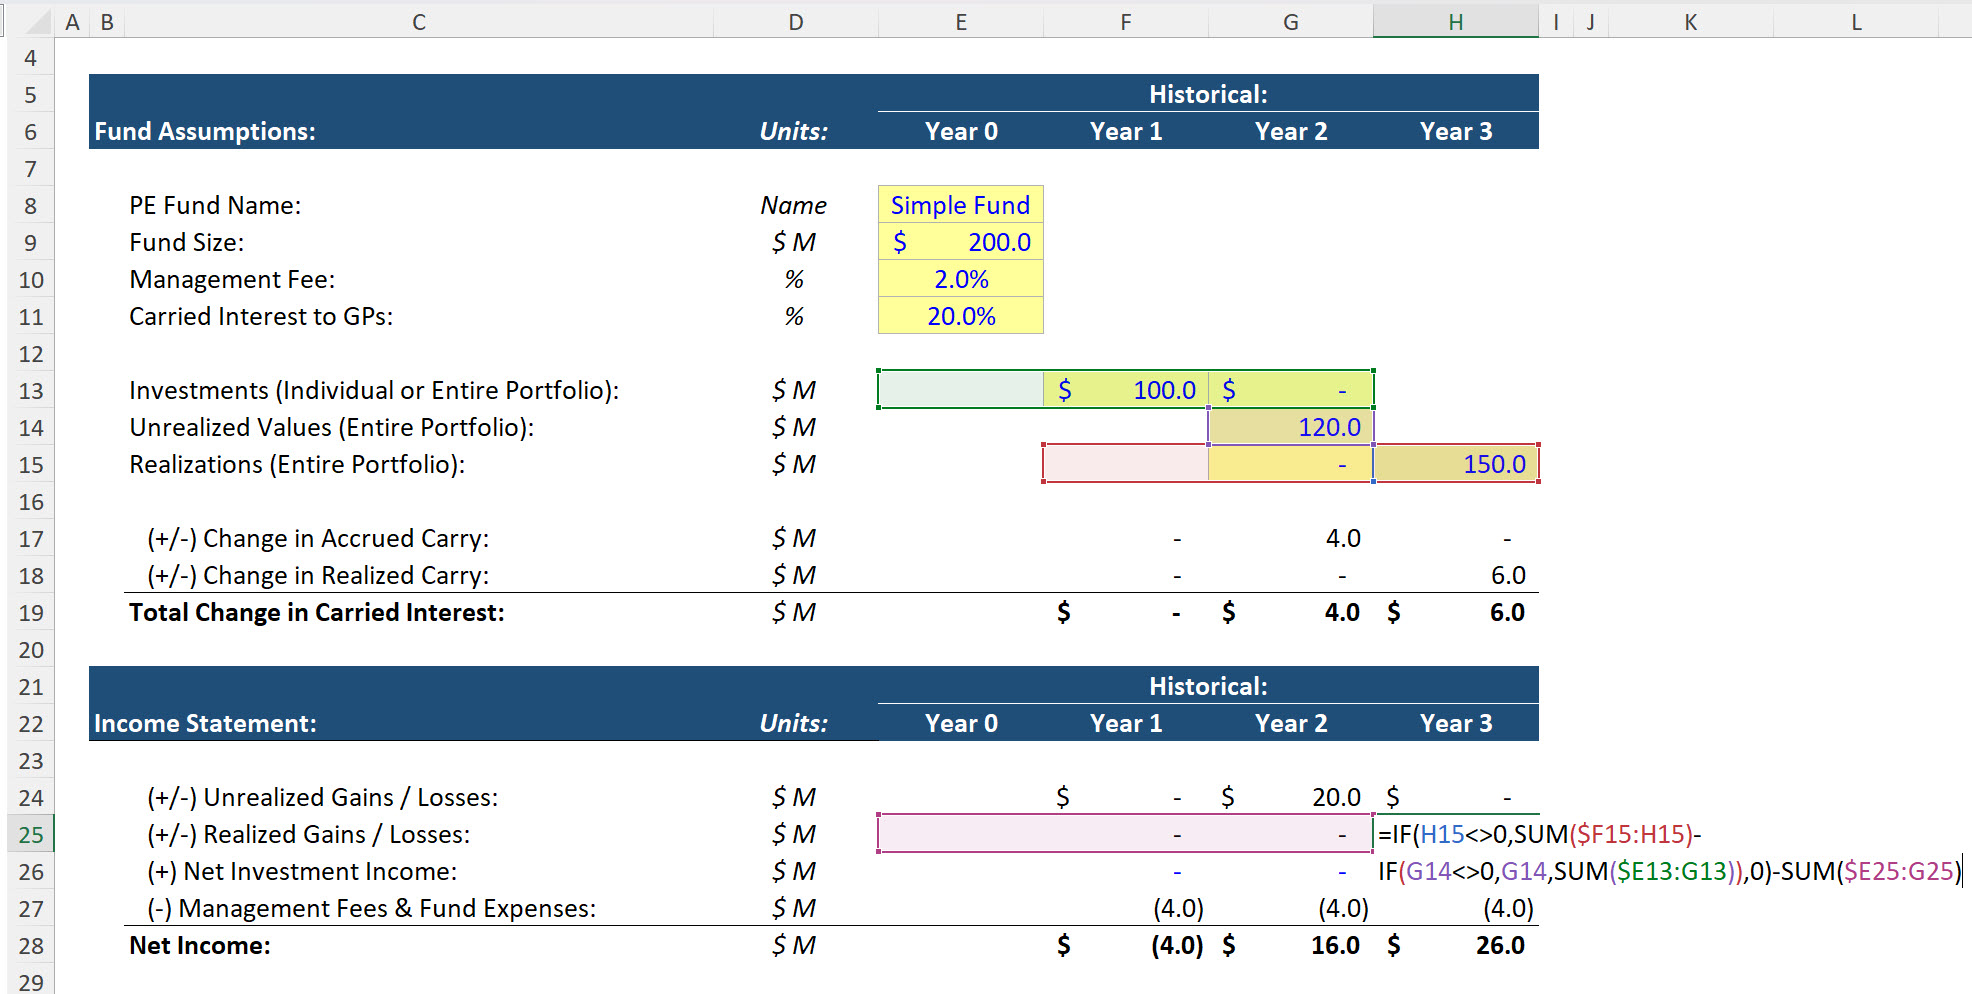
These formulas are NOT fully robust – they work for certain limited cases, but it’s not possible to handle every scenario without a detailed schedule.
The Accrued Carry is then based on a percentage of the Unrealized Gains, and the Realized Carry is based on a percentage of the Realized Gains (typically 20%).
In real life, there would be an IRR vs. Hurdle Rate check and a full waterfall schedule with the Return of Capital, Preferred Return, GP Catch-Up, and other elements.
But in this simplified example, we use simple percentages without these checks (it might be worth adding a MAX(0 to the Change in Realized Carry formula to prevent it from turning negative):
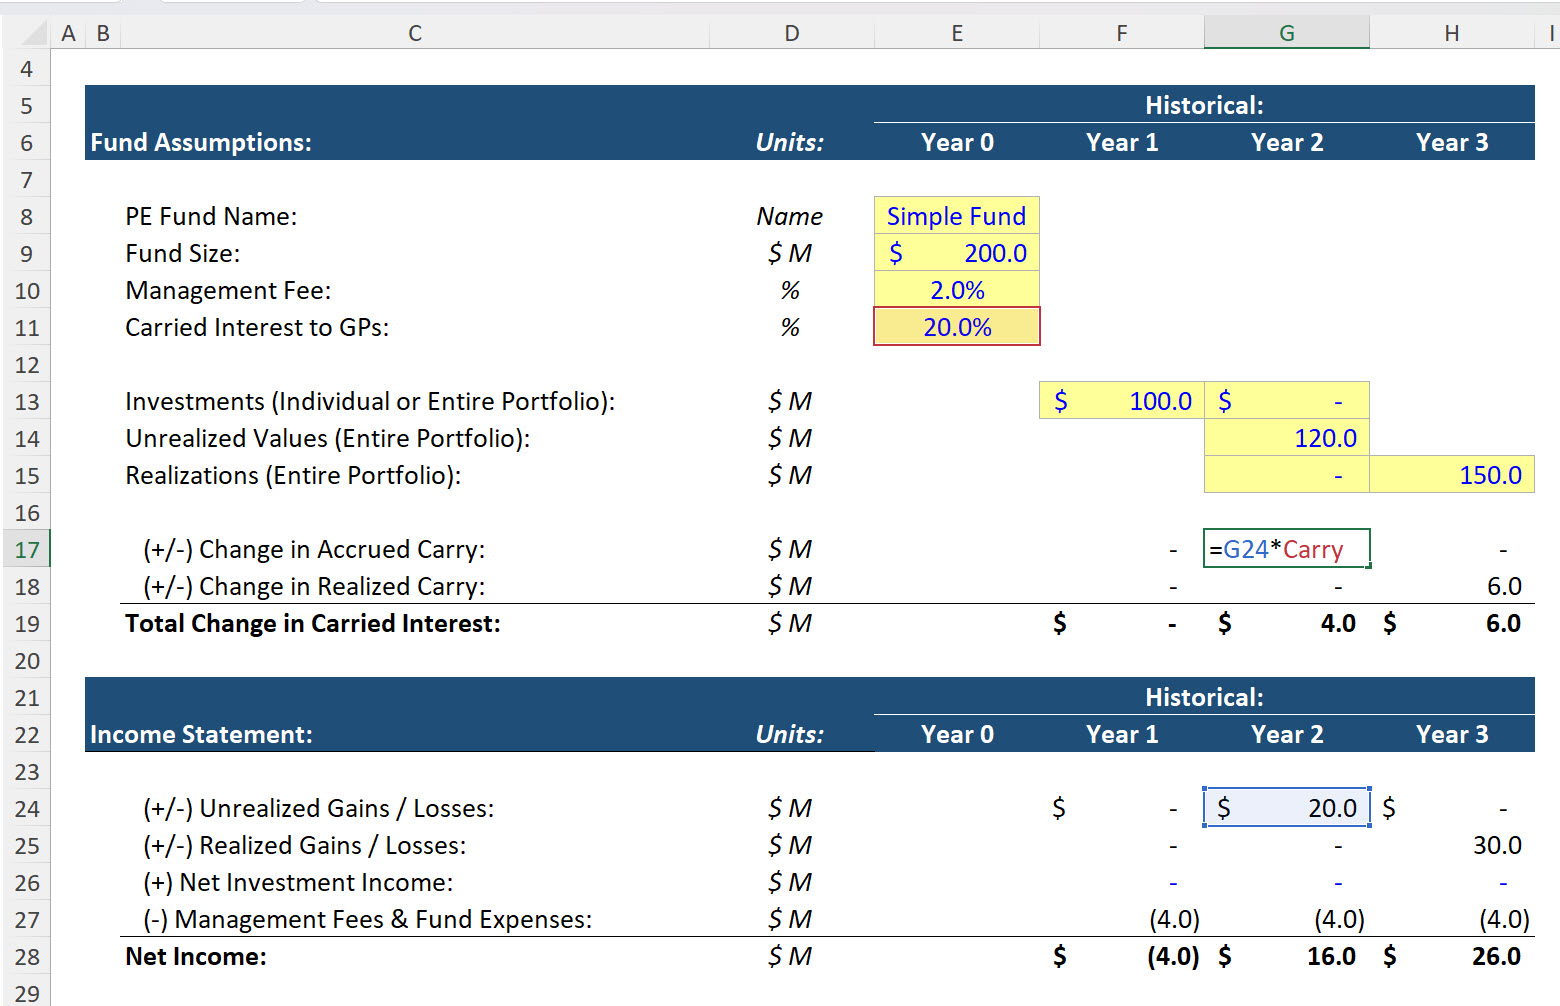
The hardest parts of the Income Statement are the Unrealized and Realized Gain/Loss calculations, but we already got these in the previous step.
Beyond these lines, there may also be Interest and Investment Income from the fund’s portfolio companies and securities, and if it uses fund-level borrowing facilities, there may be Interest Expense as well.
Note that this “Interest Expense” is only for fund-level borrowing, not the Debt of individual portfolio companies acquired in leveraged buyouts.
PE funds often use borrowing facilities to fulfill short-term funding needs, such as paying for administrative expenses, without calling on their LPs for capital.
Finally, Management Fees and other Fund Expenses are also significant line items on the Income Statement.
They are typically projected as percentages of the fund’s Committed Capital, its NAV, or its Remaining Cost Basis:
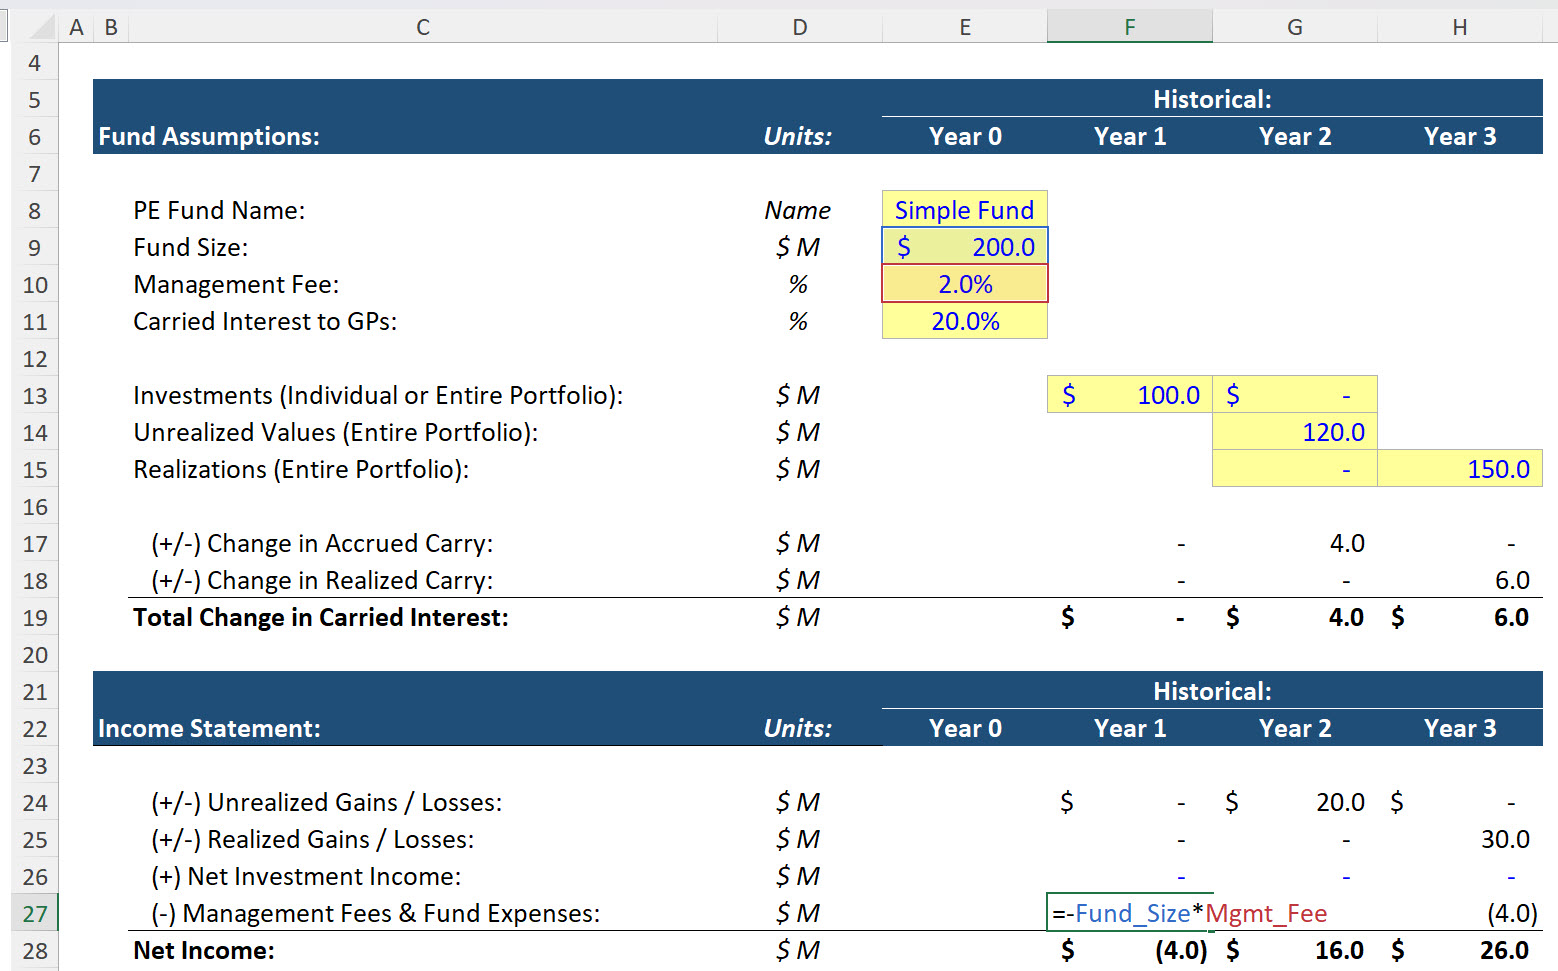
Note that neither Accrued Carry nor Distributed Carry appear on the Income Statement.
Accrued Carry does not appear as an explicit line item anywhere on the statements.
The “bottom line” of the Income Statement is still labeled “Net Income,” but unlike with normal companies, this is a pre-tax number because most PE funds are pass-through entities.
A private equity fund’s Balance Sheet is surprisingly simple: The Fair Market Value of Investments (portfolio companies and any other assets), Cash, and Receivables on the Assets side, and Debt, Payables, and the LPs’ and GPs’ Capital on the L&E side.
The Working Capital lines are not that important for PE funds, but they often come up because of timing differences between agreeing to investments or sales and paying/receiving the cash proceeds.
The more interesting part is how the links to the Cash Flow Statement work.
The Cash Flow Statement starts with Net Income and then includes items for the “Funding of Investments,” i.e., investments in portfolio companies, and “Proceeds from the Sale of Investments,” i.e., portfolio company exits.
Then, it reverses Realized and Unrealized Gains and Losses below these lines (standard lines, even for normal companies) and records something for the Change in Working Capital:
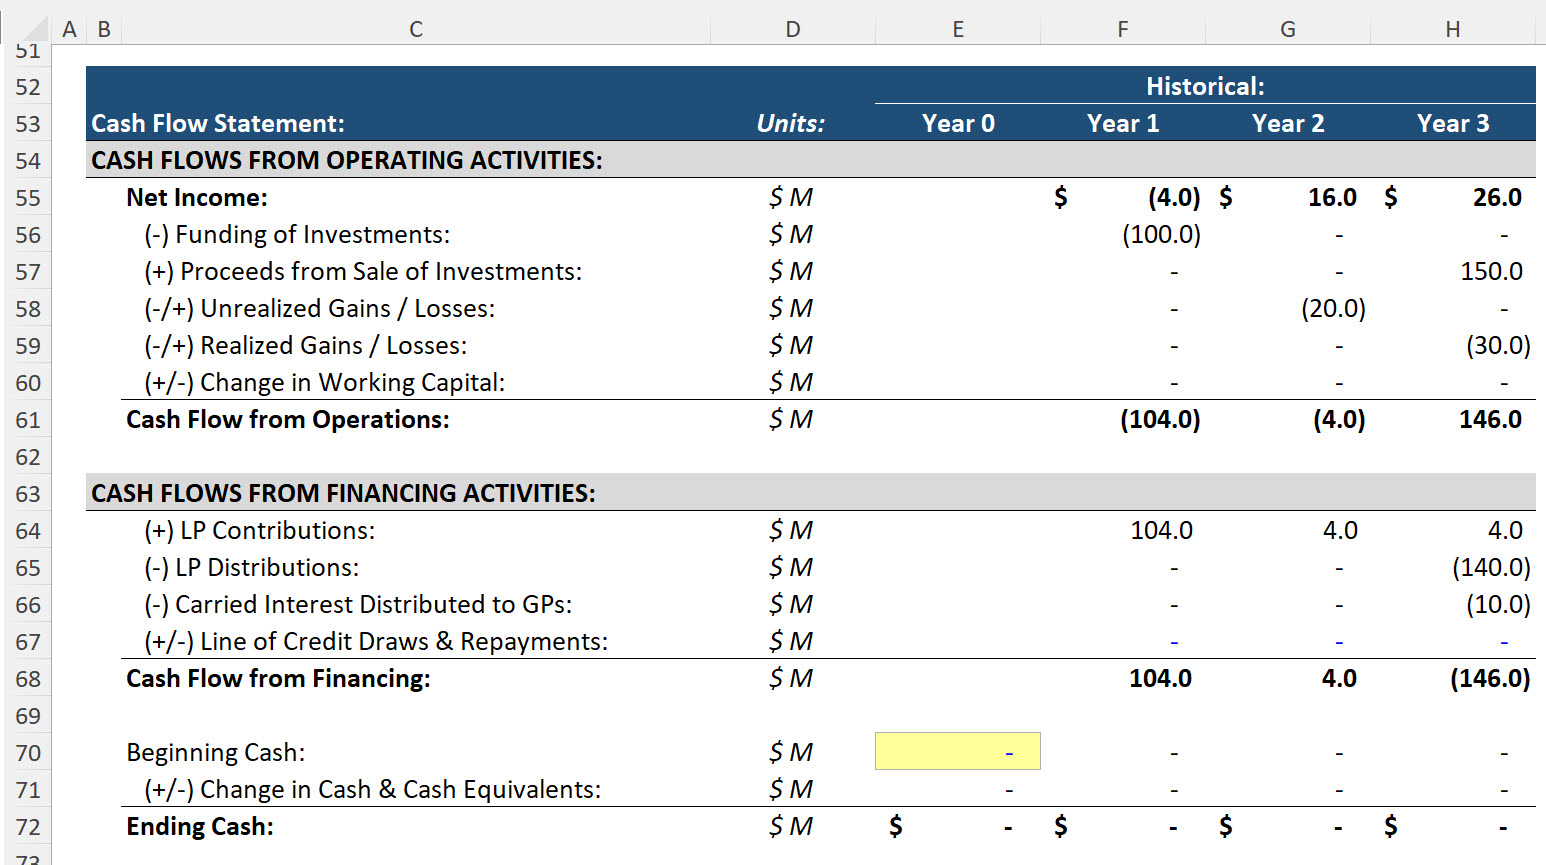
For a normal company, “Funding of Investments” and “Proceeds from the Sale of Investments” show up in Cash Flow from Investing, but for a private equity fund, these are considered operational activities.
In Cash Flow from Financing, there are lines for Investor Contributions and Distributions, a line for the Realized Carried Interest that is distributed to the GPs, and lines related to the fund’s use of credit-facilities, such as borrowing and repayments.
Most of these line items come from the previously built schedules, but the “LP Distributions” one is based on the Realizations in the Period minus the Carried Interest paid to the GPs.
“LP Contributions” are linked to the investments in portfolio companies, plus any funds needed for Management Fees and other Fund Expenses (assuming no borrowing facility).
On the Balance Sheet, most of the line items follow the standard links: For example, Cash flows in from the bottom of the Cash Flow Statement, and Debt is based on the old number plus the Changes in Debt on the Cash Flow Statement.
The “new/interesting” links are:
This one follows the standard rules for links on the Assets side of the Balance Sheet: Take the old item and subtract all the corresponding CFS lines.
Since the Funding line is always a negative on the CFS, subtracting it increases the FMV of Investments, and since the Proceeds line is always a positive, subtracting it reduces the FMV.
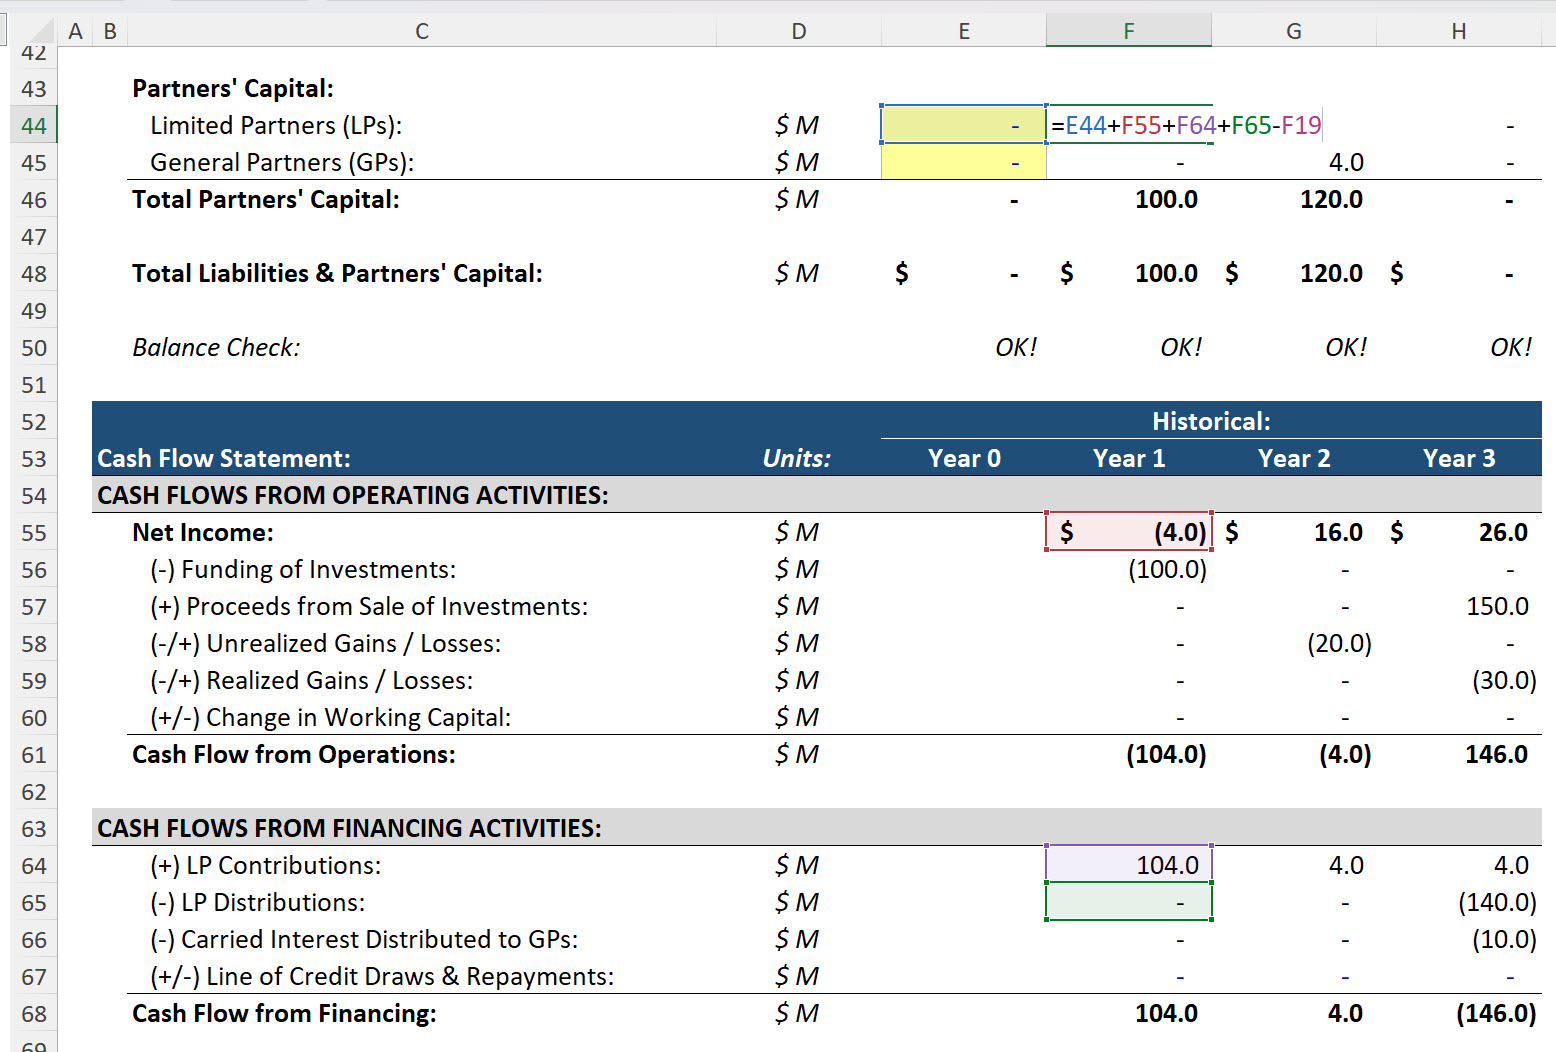
The counterintuitive part is that the Accrued Carry line does not appear directly on the statements, but changes in it affect the LPs’ and GPs’ Capital.
If the GPs make a successful investment whose value increases, they will earn a percentage of the investment profits, and that should be reflected in higher “GP Capital.”
But since the Accrued Carry is not shown directly on the statements and does not affect the Cash balance, this setup technically violates one of our “financial modeling best practices.”
The Distributed Carried Interest is added because it always has a negative sign on the CFS, so it’s like the Dividend setup for a normal company (it reduces Equity since it represents a payment to shareholders).
The example above is an extremely simplified view of private equity fund financial statements, intended to introduce you to the main concepts.
In our Funds of Funds course, we cover a more complex version with added nuance for the following points:
You can see a few examples of these added nuances below:
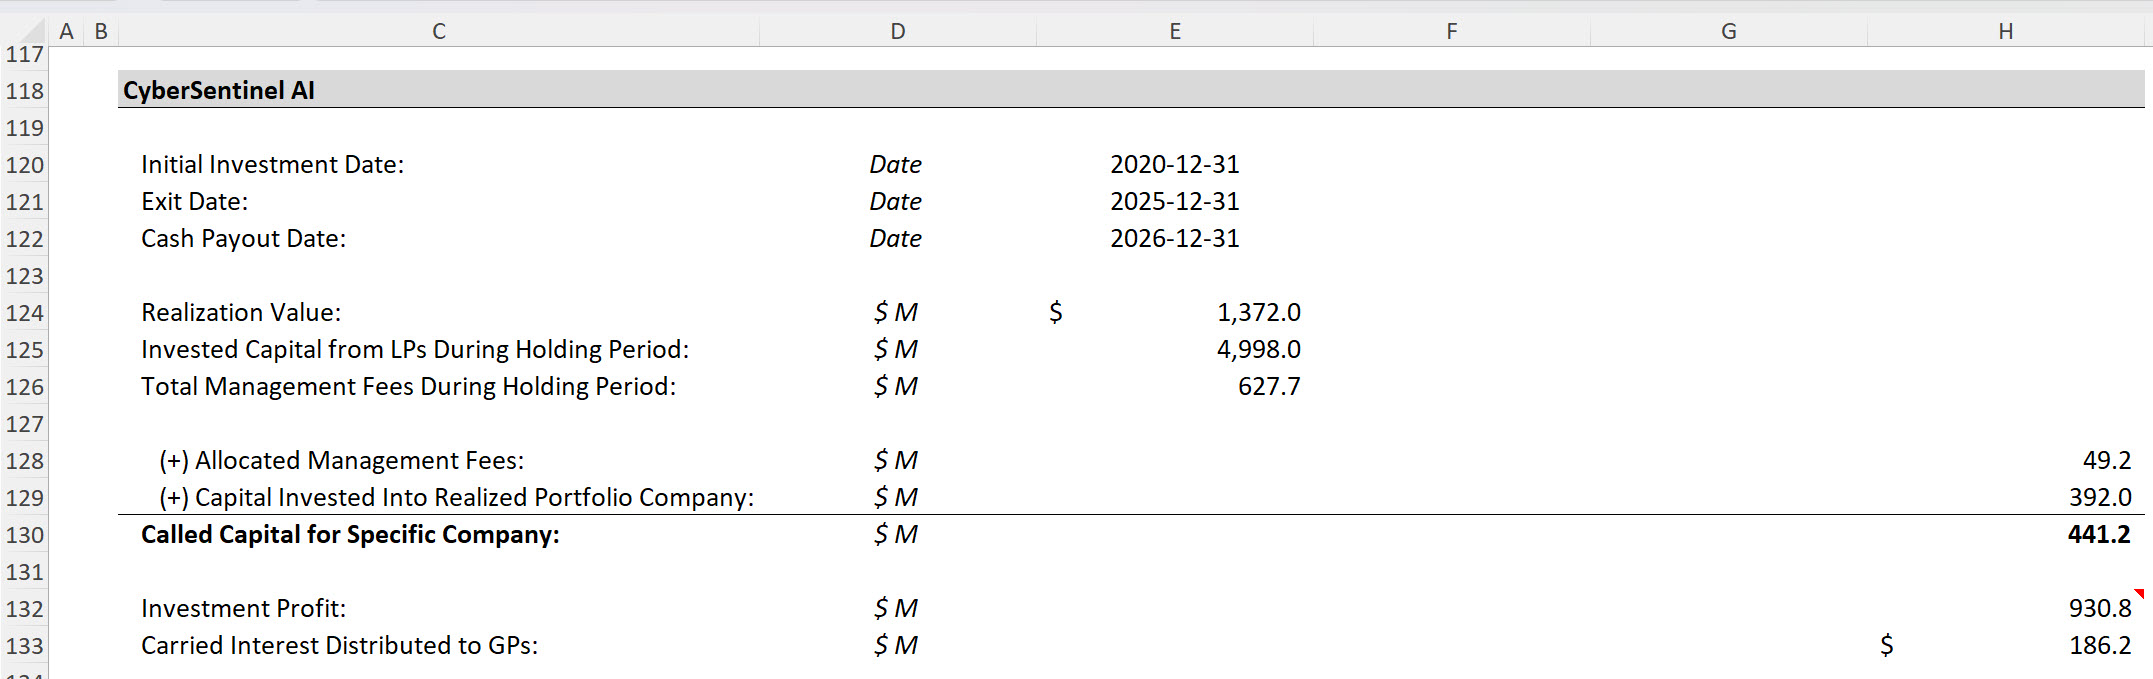
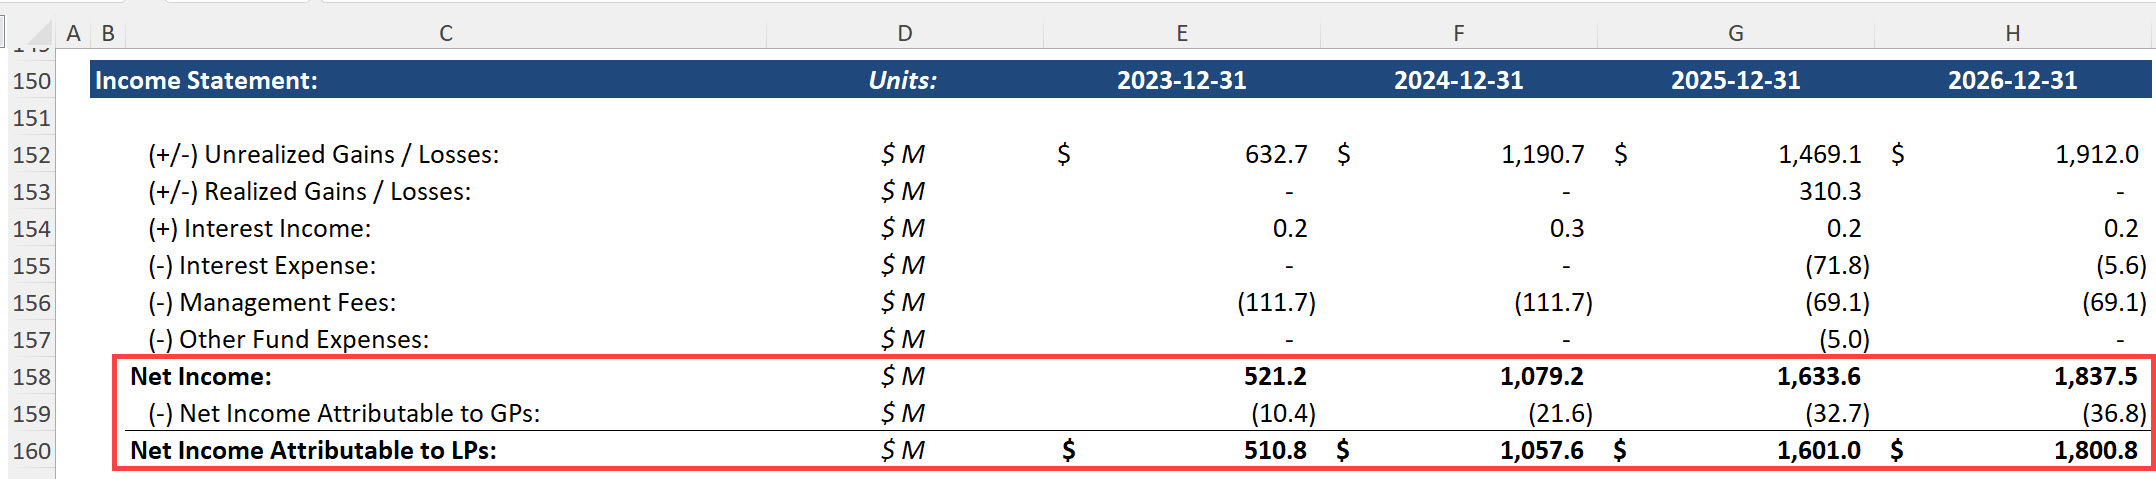
And the complexity keeps extending beyond this.
For example, in real life, you would need a separate waterfall schedule for each portfolio company to model Carry correctly and allow for the exit of any company at any time.
The goal of this model is to explain the main concepts, so the investment and exit dates are intentionally more constrained here.
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.

