


About Brian DeChesare
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.
Trading Securities or “Fair Value Through Profit & Loss” (FVPL) Securities are used to record a company’s short-term buying and selling of investments; Unrealized and Realized Gains/Losses on these securities appear on the Income Statement, as do the associated Dividends and Interest Income. Accounting rules created in 2016 mean that U.S.-based companies must use this category for *all* small equity stakes in other companies now, which has created huge Unrealized Gains and Losses for many firms.
Trading Securities Tutorial
Trading Securities Definition: Trading Securities or “Fair Value Through Profit & Loss” (FVPL) Securities are used to record a company’s short-term buying and selling of investments; Unrealized and Realized Gains/Losses on these securities appear on the Income Statement, as do the associated Dividends and Interest Income. Accounting rules created in 2016 mean that U.S.-based companies must use this category for *all* small equity stakes in other companies now, which has created huge Unrealized Gains and Losses for many firms.
As background information, accounting rules under IFRS and U.S. GAAP describe different types of “securities” to reflect companies’ investments in other entities.
The rules and names under IFRS differ slightly (but the concepts are the same), so we’ll focus on the U.S. GAAP categories here:
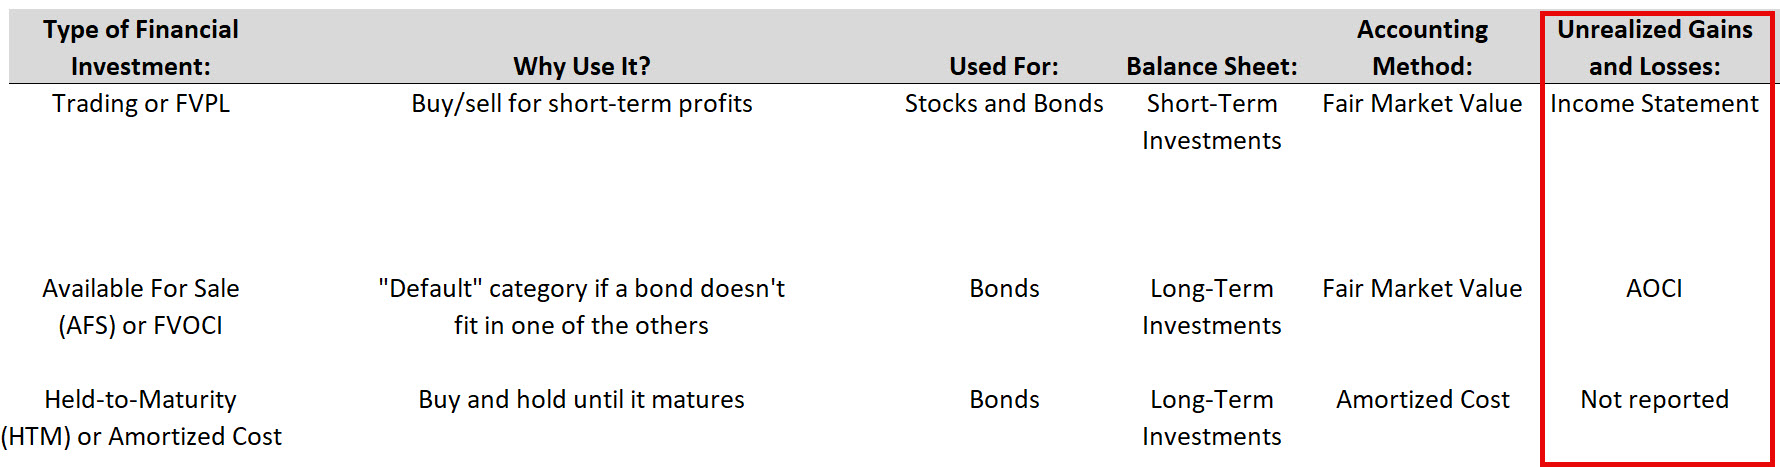
Back in 2018 – 2019, ASU 2016-01 went into effect, which eliminated the Trading vs. AFS vs. HTM categories shown above for Equity Securities, or small positions in other companies’ shares.
Debt Investments can still be put in any of these categories, depending on the company’s intended holding period.
Therefore, if a company like Google purchased SpaceX shares in the past, it must now classify them as “Trading Securities,” even if it has no plans to sell in the short term:

This ends up greatly distorting Google’s Net Income because now it includes the results of massive valuation increases in SpaceX’s stock:
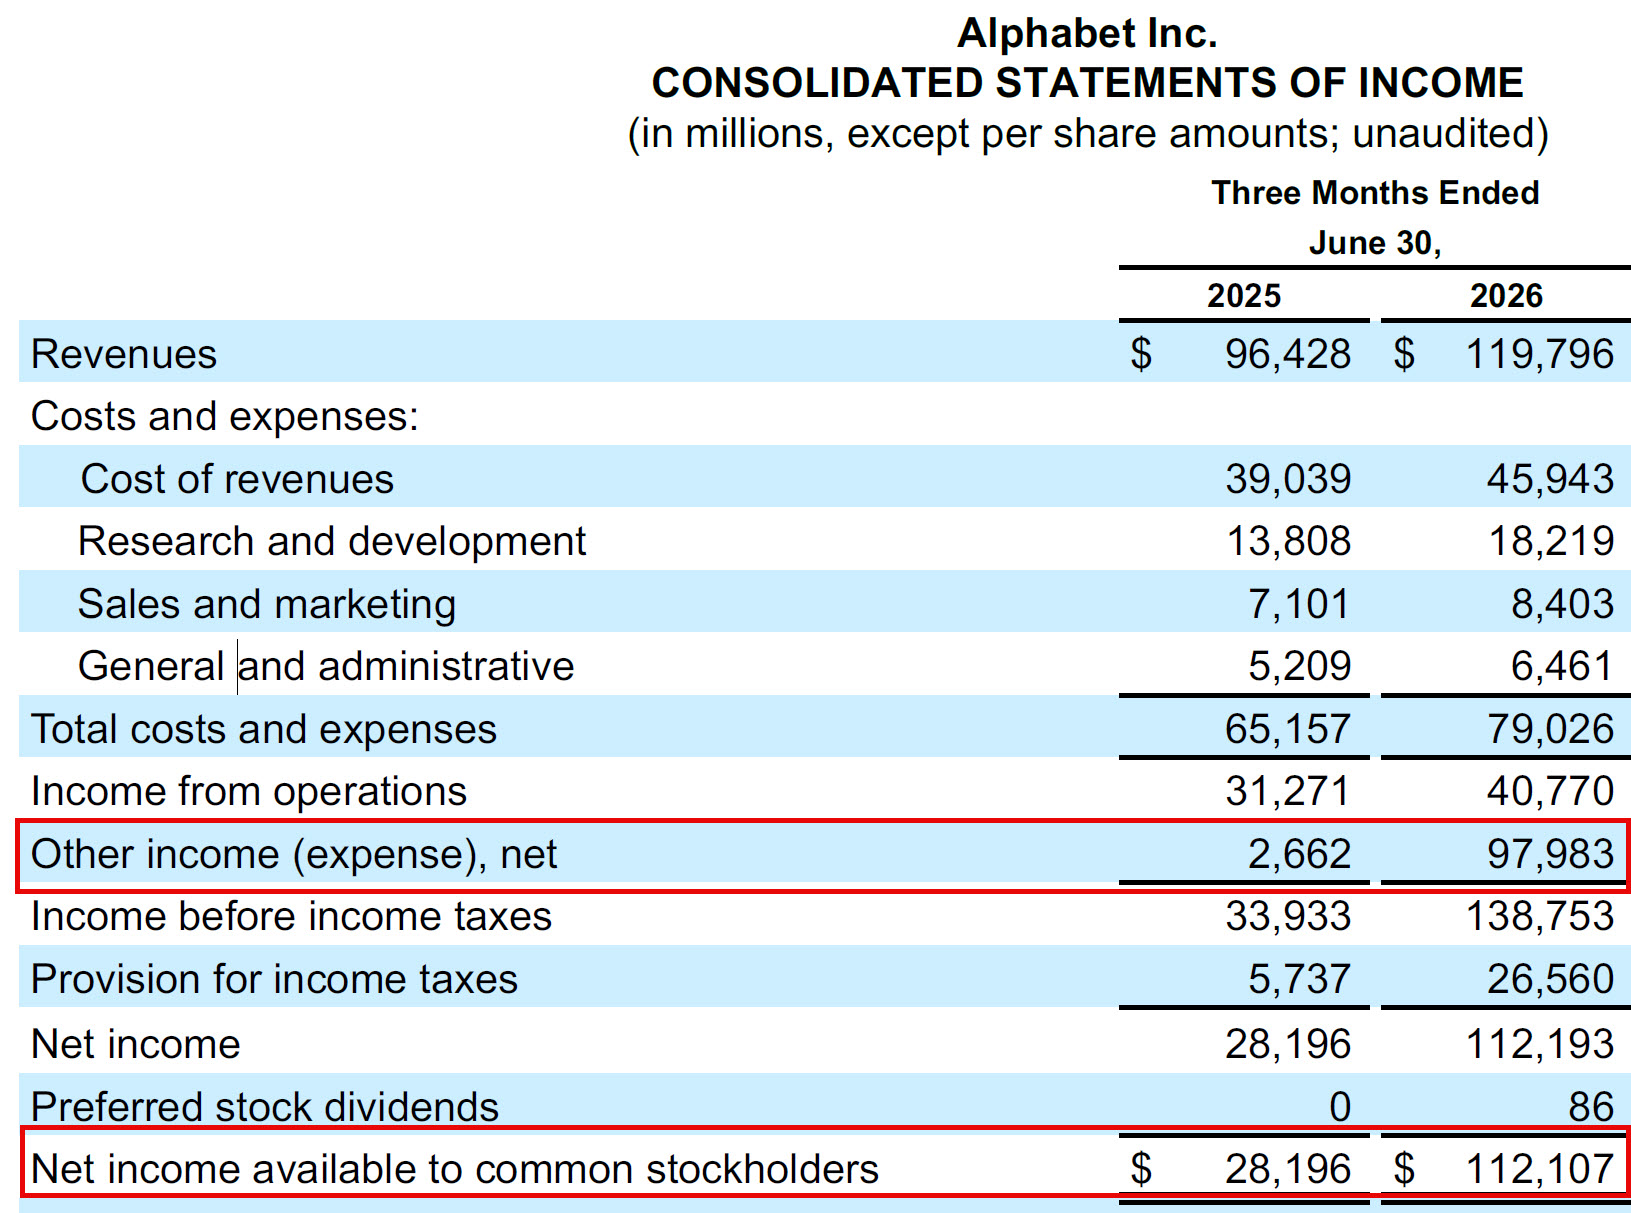
Google is not alone: Companies like Amazon and Microsoft have done the same thing for their investments in Anthropic, OpenAI, and various other AI startups.
To be clear, Google’s accounting here is not “fraudulent” – it is following the rules.
The issue is that the rules were created before these circular financing deals for AI companies became popular, and they were intended to deal with a previous emergency (the 2008 financial crisis), not the current bubble.
The main takeaway is that you should be very skeptical of Net Income as a metric and P / E (Equity Value / Net Income) as a valuation multiple because it is frequently distorted.
Rely on metrics such as EBIT, EBITDA, and Unlevered Free Cash Flow that remove or reverse these Gains and Losses.
Even something like Free Cash Flow, despite its flaws, is a better way to evaluate Big Tech companies than Net Income, EPS, or anything else that fails to reverse Gains and Losses.
In Q2 of 2026, Google (OK, “Alphabet”) announced Net Income growth of nearly 300%, which sounds amazing until you examine the “Other Income” component:
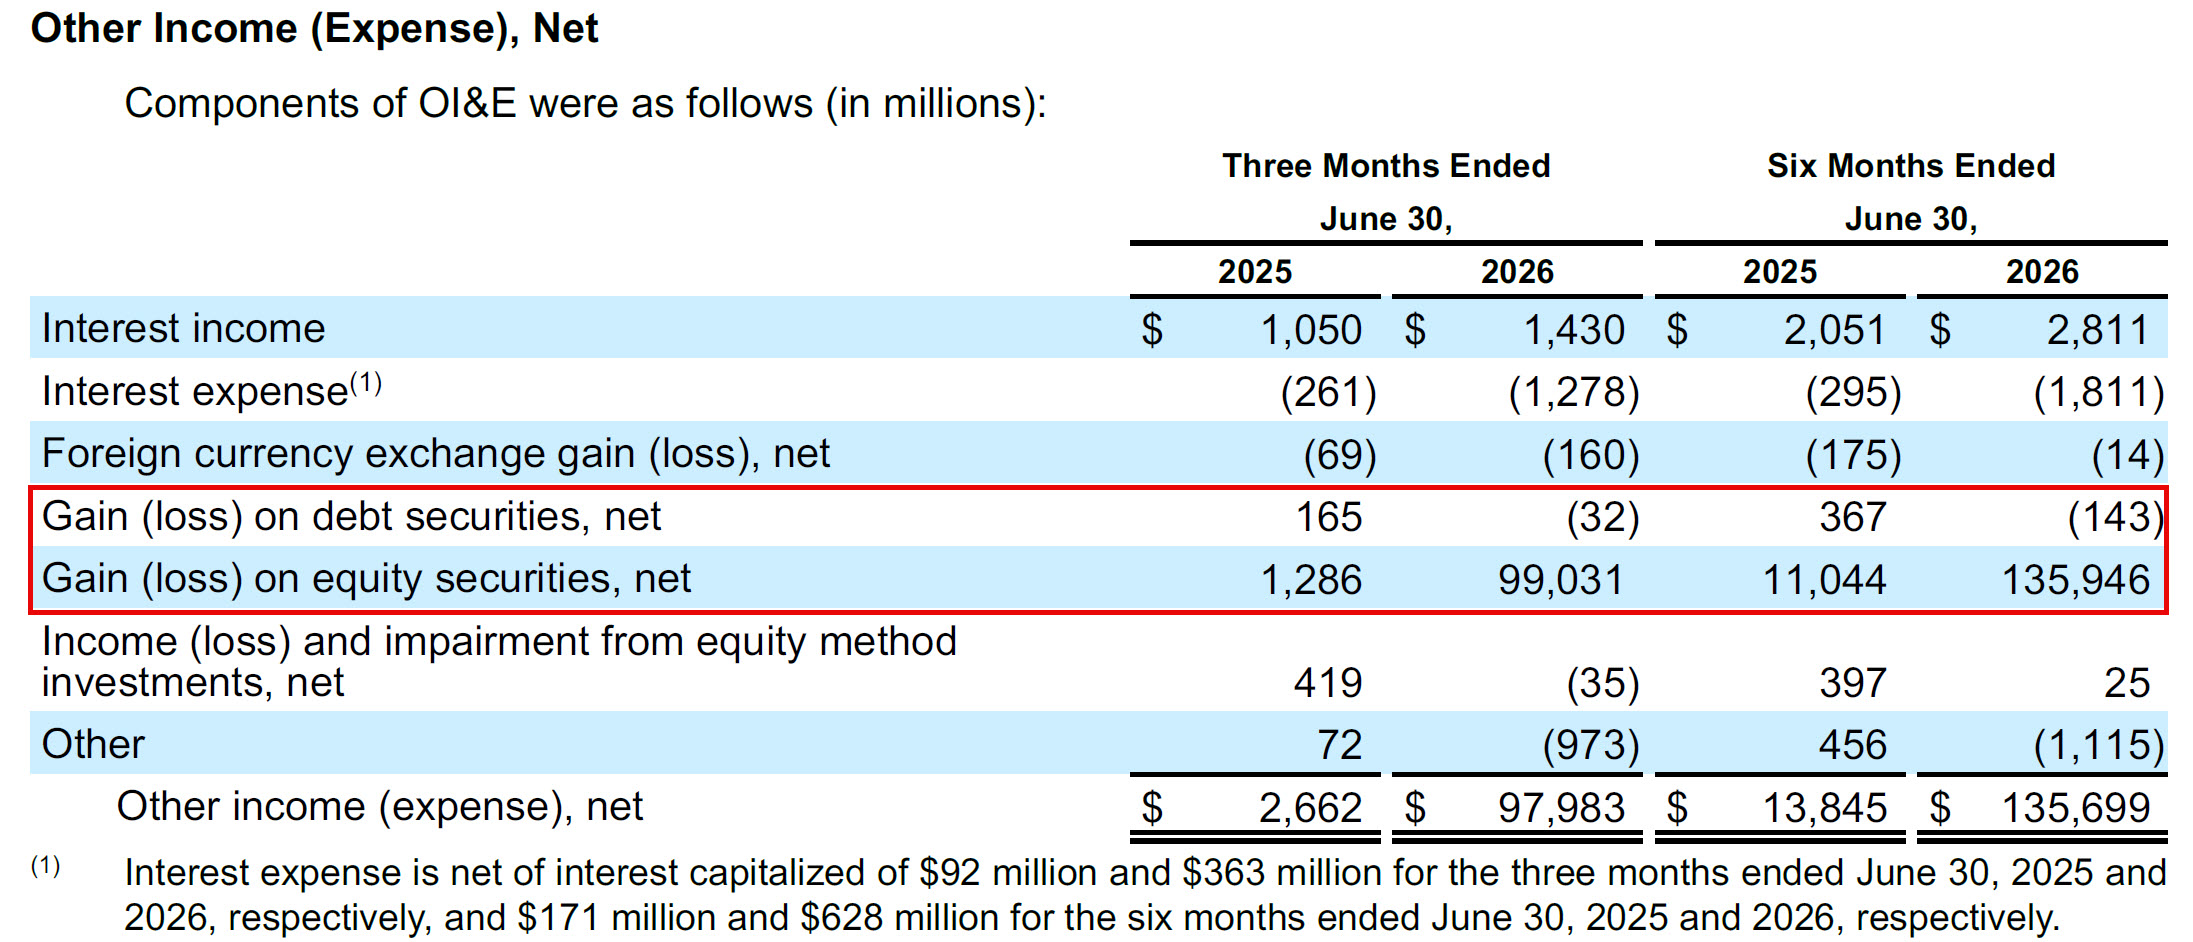
You can tell that most of these Gains and Losses were Unrealized and related to the SpaceX IPO by reviewing the Cash Flow Statement or continuing to read through the footnotes:

So, you can easily conclude that Google’s Net Income was deceptively high in this past quarter and the past 6 months because of SpaceX’s massive rise in value and absurdly inflated IPO.
But this works in both directions: As we predicted, SpaceX’s share price has plummeted since the IPO, so Google will also get to record a fun “Unrealized Loss” in its Q3 earnings.
Many people believe that since Big Tech companies trade at reasonable P/E multiples, such as 16.0x for Google, we are “not in an AI Bubble.”
However, if you remove these Unrealized Gains, the picture changes quite a bit.
Here are the GAAP vs. “Pro-Forma” versions of Google’s LTM Net Income as of June 30, 2026, with Gains and Losses removed in the Pro-Forma version:
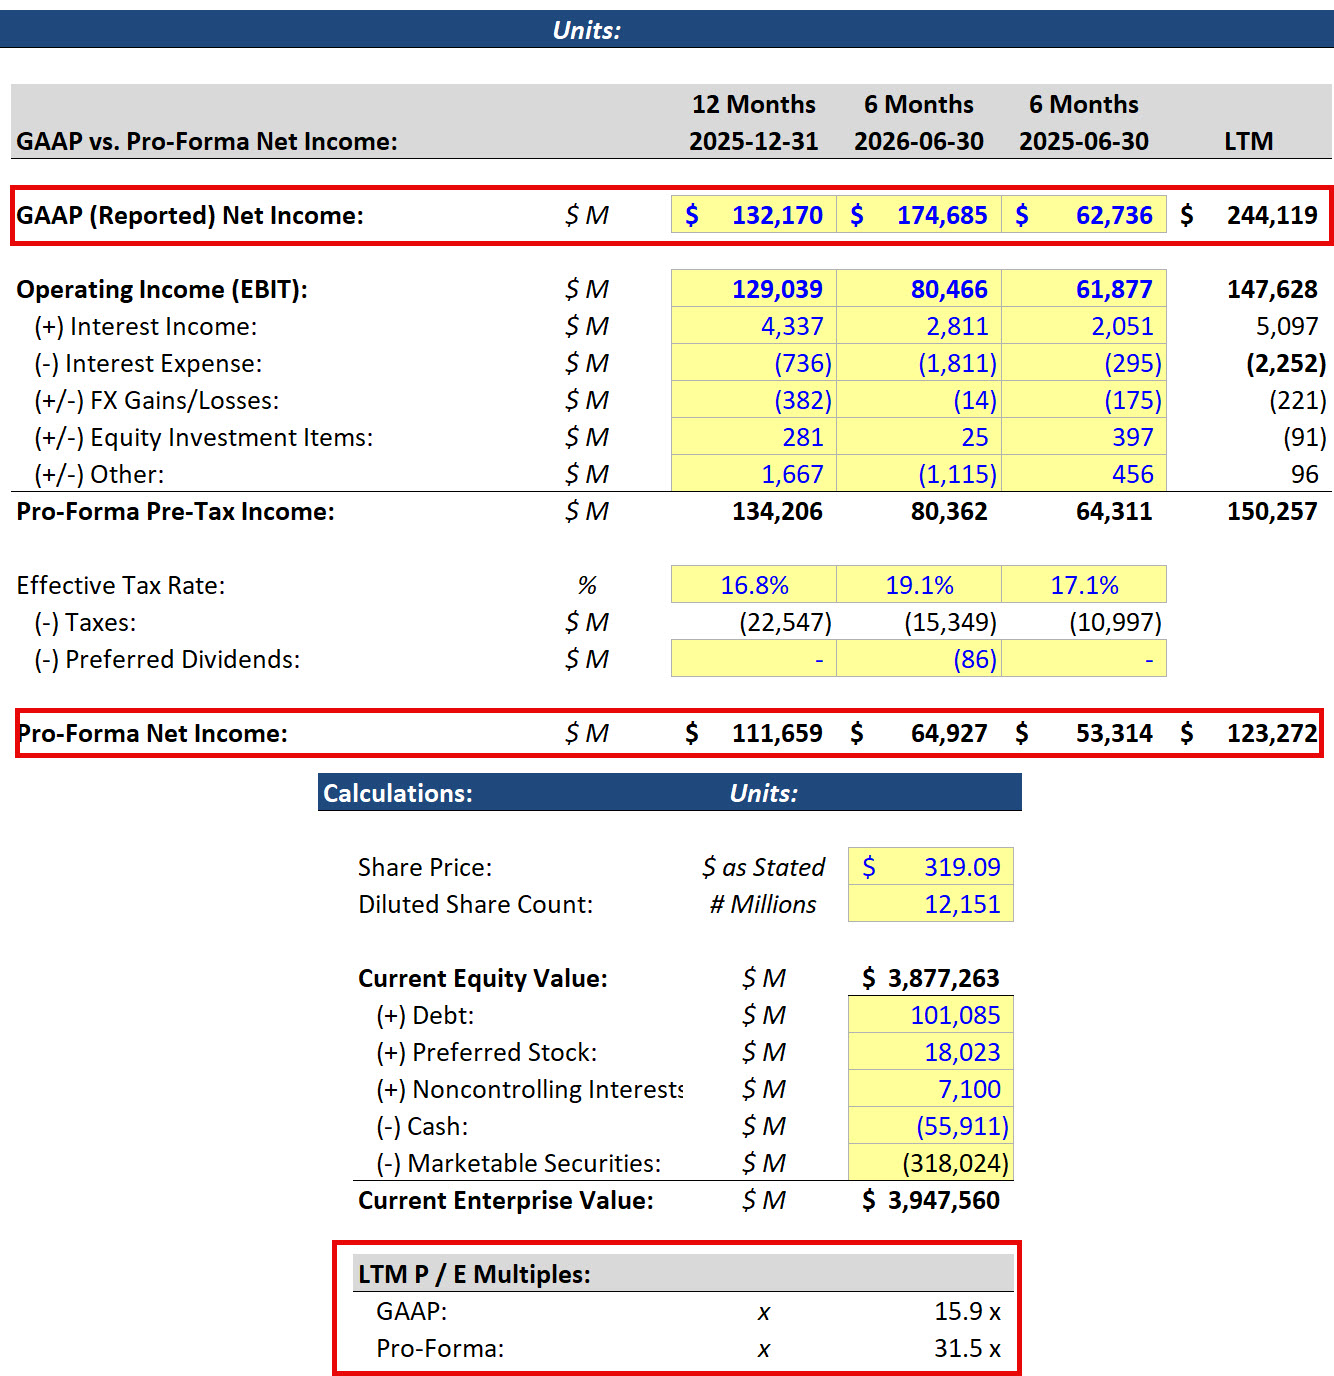
Google’s P/E LTM multiple nearly doubles, increasing from 15.9x to 31.5x.
You could certainly argue that 32x P / E is still “cheap” for a company with Google’s scale, growth, and profitability, but it’s clearly a lot more expensive than 16x (16x is close to the historical average for the S&P 500).
Metrics such as EBITDA and UFCF that remove or reverse Gains and Losses are much better for evaluating all companies, but especially these Big Tech firms with complex webs of circular investments.
When a company records a Realized Gain or Loss because it bought a stock or bond at one price and sold it at a different price, the accounting treatment is the same for all security types.
Record the Gain or Loss on the Income Statement, reverse it on the CFS, show the total amount of proceeds received in Cash Flow from Investing, and link both these items to the corresponding Asset on the Balance Sheet.
When there’s an Unrealized Gain or Loss, the accounting treatment gets more complex.
“Unrealized” means that the market value of the stock or bond changes, but the company does not sell anything (as in the Google / SpaceX example above – Google literally cannot sell any SpaceX stock because of the lock-up period following the IPO).
If the investment is classified as a Trading Security, Unrealized Gains and Losses appear directly on the Income Statement but do not affect Cash Taxes, so the Deferred Tax Asset (DTA) changes and then reverses when the Gain or Loss is realized.
Here’s what happens on the statements for an Unrealized Gain on this type of Google / SpaceX stake, using the simple “accounting interview question” Excel file above.
If a company owns $100 of Equity Securities, the market value of the Securities increases to $120, and the company does not sell anything, it records a $20 Gain on the Income Statement:
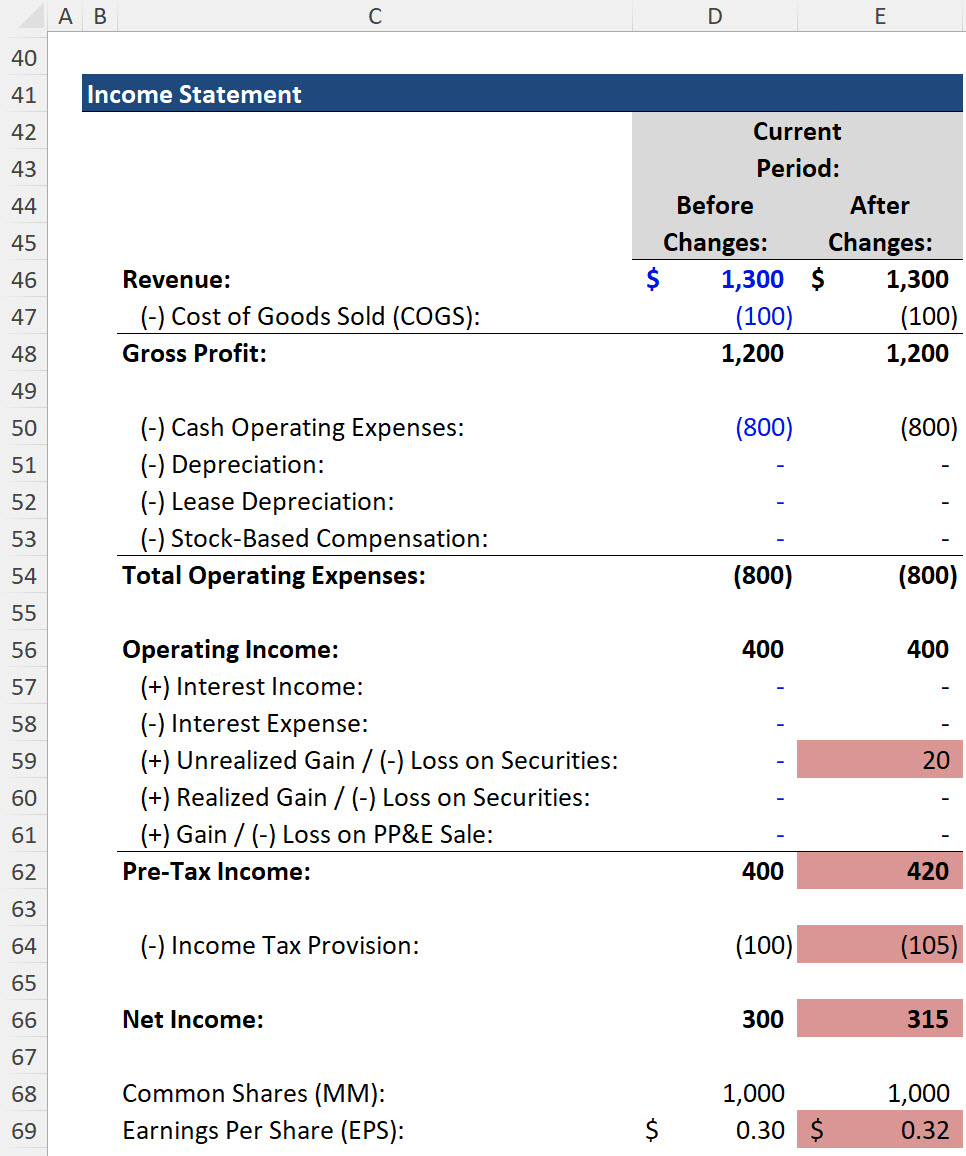
The company’s Book Taxes increase by $5, but it does not pay anything in Cash Taxes since the Gain is unrealized.
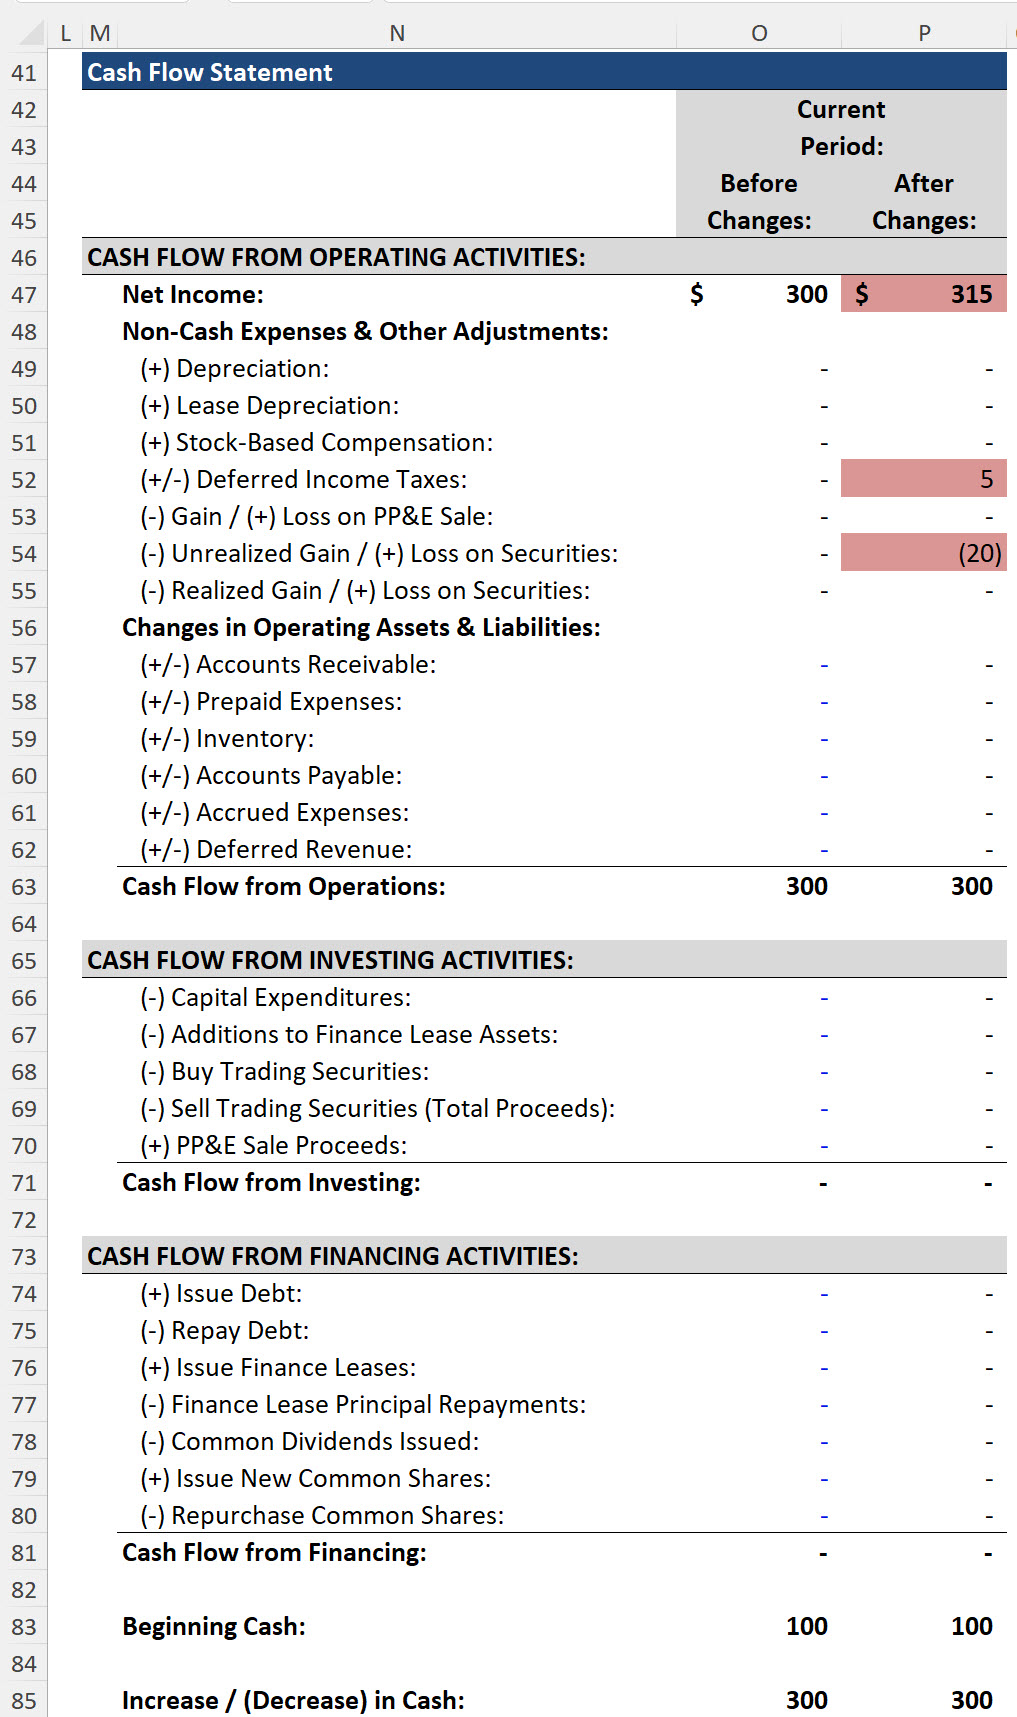
So, on the Cash Flow Statement, Net Income is up by $15, the Gain is reversed for ($20), and there’s an adjustment of +$5 for Deferred Income Taxes.
Nothing else changes, and Cash stays the same:
On the L&E side of the Balance Sheet, Common Shareholders’ Equity is up by $15 due to the increased Net Income, so both sides balance:
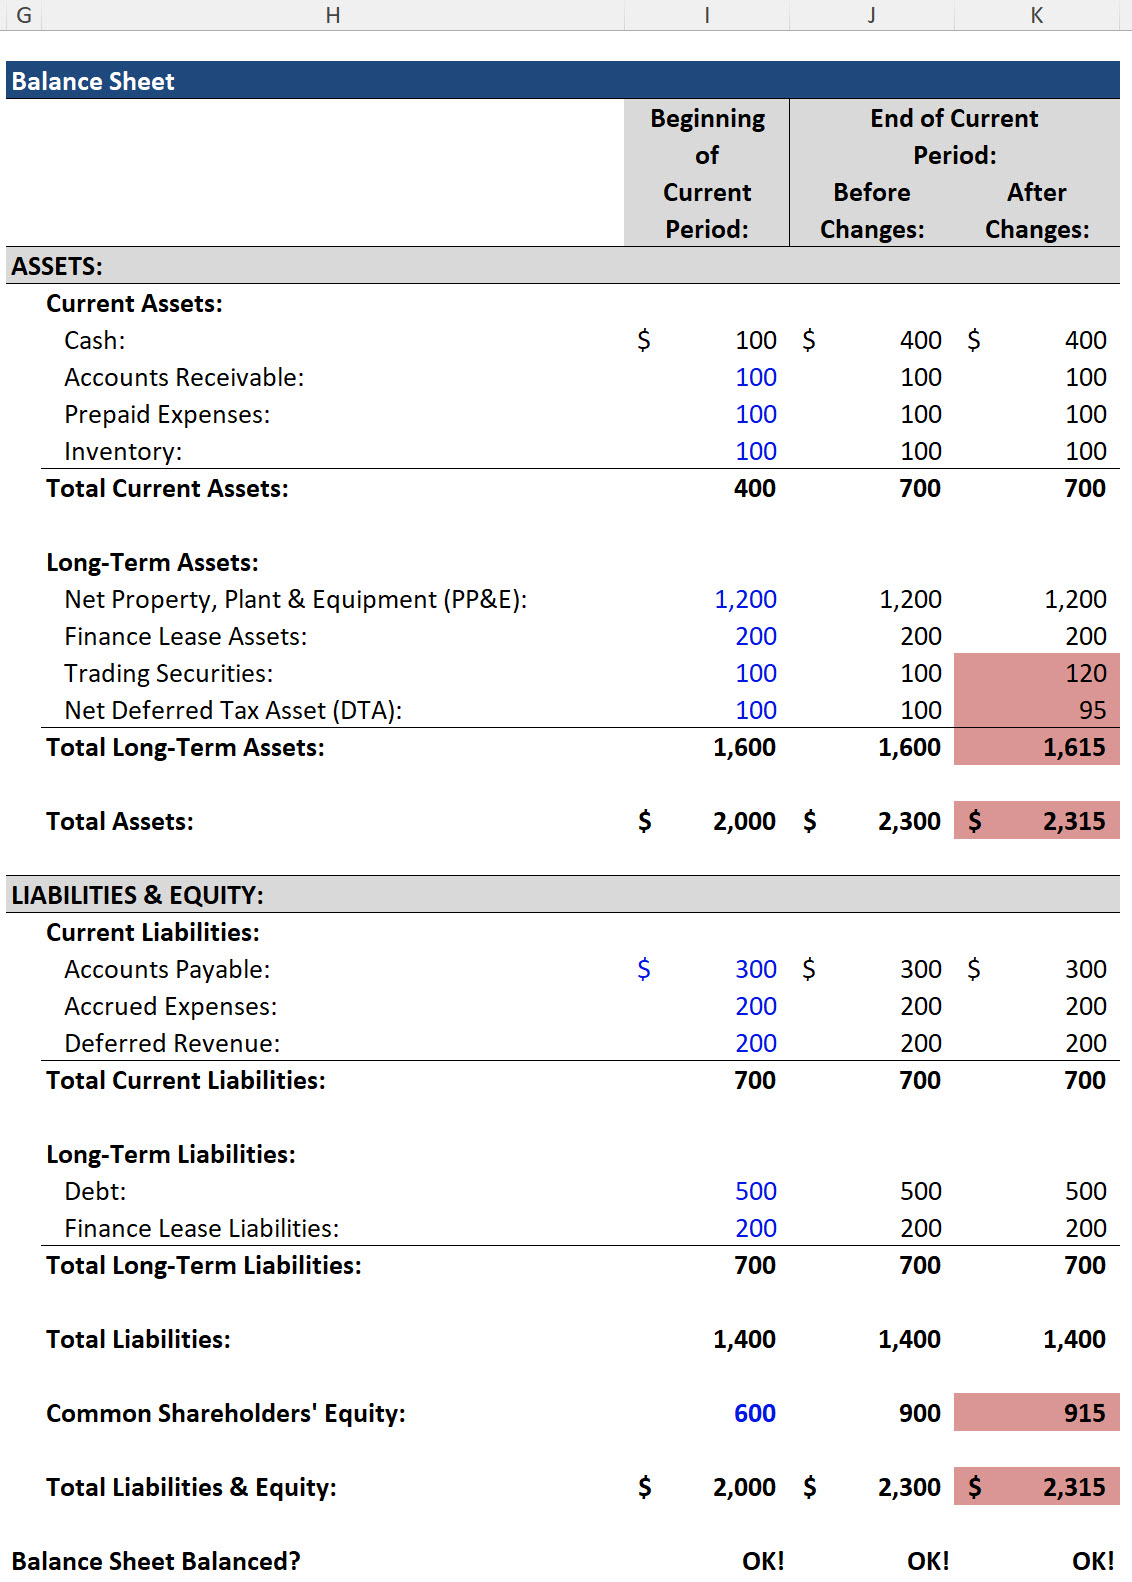
The DTA decreases because the company does not pay additional Cash Taxes right away.
Once the company sells these Trading Securities, it will have to pay the taxes, so its Cash Taxes will exceed its Book Taxes by $5, and the Net DTA will return to its original $100.
Other types of securities, such as Available for Sale (AFS) and Held-to-Maturity (HTM) Investments, are outside the scope of this tutorial.
But to summarize: With Unrealized Gains and Losses, there will be an entry in Accumulated Other Comprehensive Income (AOCI) for AFS Securities, and the corresponding Securities on the Assets side of the Balance Sheet will also change as its market value changes.
However, nothing will appear on the Income Statement.
For HTM Securities, Unrealized Gains and Losses are not reported anywhere on the statements, so you will never see their impact until the company sells the investments.
So, these investment practices and accounting rules create deceptive metrics and headlines, but what’s the big deal?
After all, you can just use alternative metrics and valuation methodologies to get a more accurate view of companies’ valuations.
One issue is that even if *you* use different metrics, many indices, ETFs, and investment managers still focus heavily on the Net Income and EPS numbers.
So, you may end up with an overvalued portfolio even if you are just a “passive investor.”
Also, Big Tech companies can keep inflating their Net Income by “investing in” AI startups and buying products/services from the startups (i.e., GPU rentals) or selling the startups services (i.e., cloud services). The Big Tech company gets to record Revenue from the product/service sales and Unrealized Gains by claiming the startups are now more valuable.
While this is not illegal, we believe this type of relationship should be disclosed in a separate line item on the statements.
For a company like Berkshire Hathaway, it’s reasonable to record Unrealized Gains and Losses without additional disclosures because it does not have business relationships with companies in which it owns minority stakes.
For example, if Berkshire buys 3% of Apple’s shares, it does not then sell a product or service to Apple, have Apple buy it using the funds it just invested, record Revenue from it, and then record an additional Unrealized Gain on Apple.
But companies like Google are doing this for AI-related companies like SpaceX:
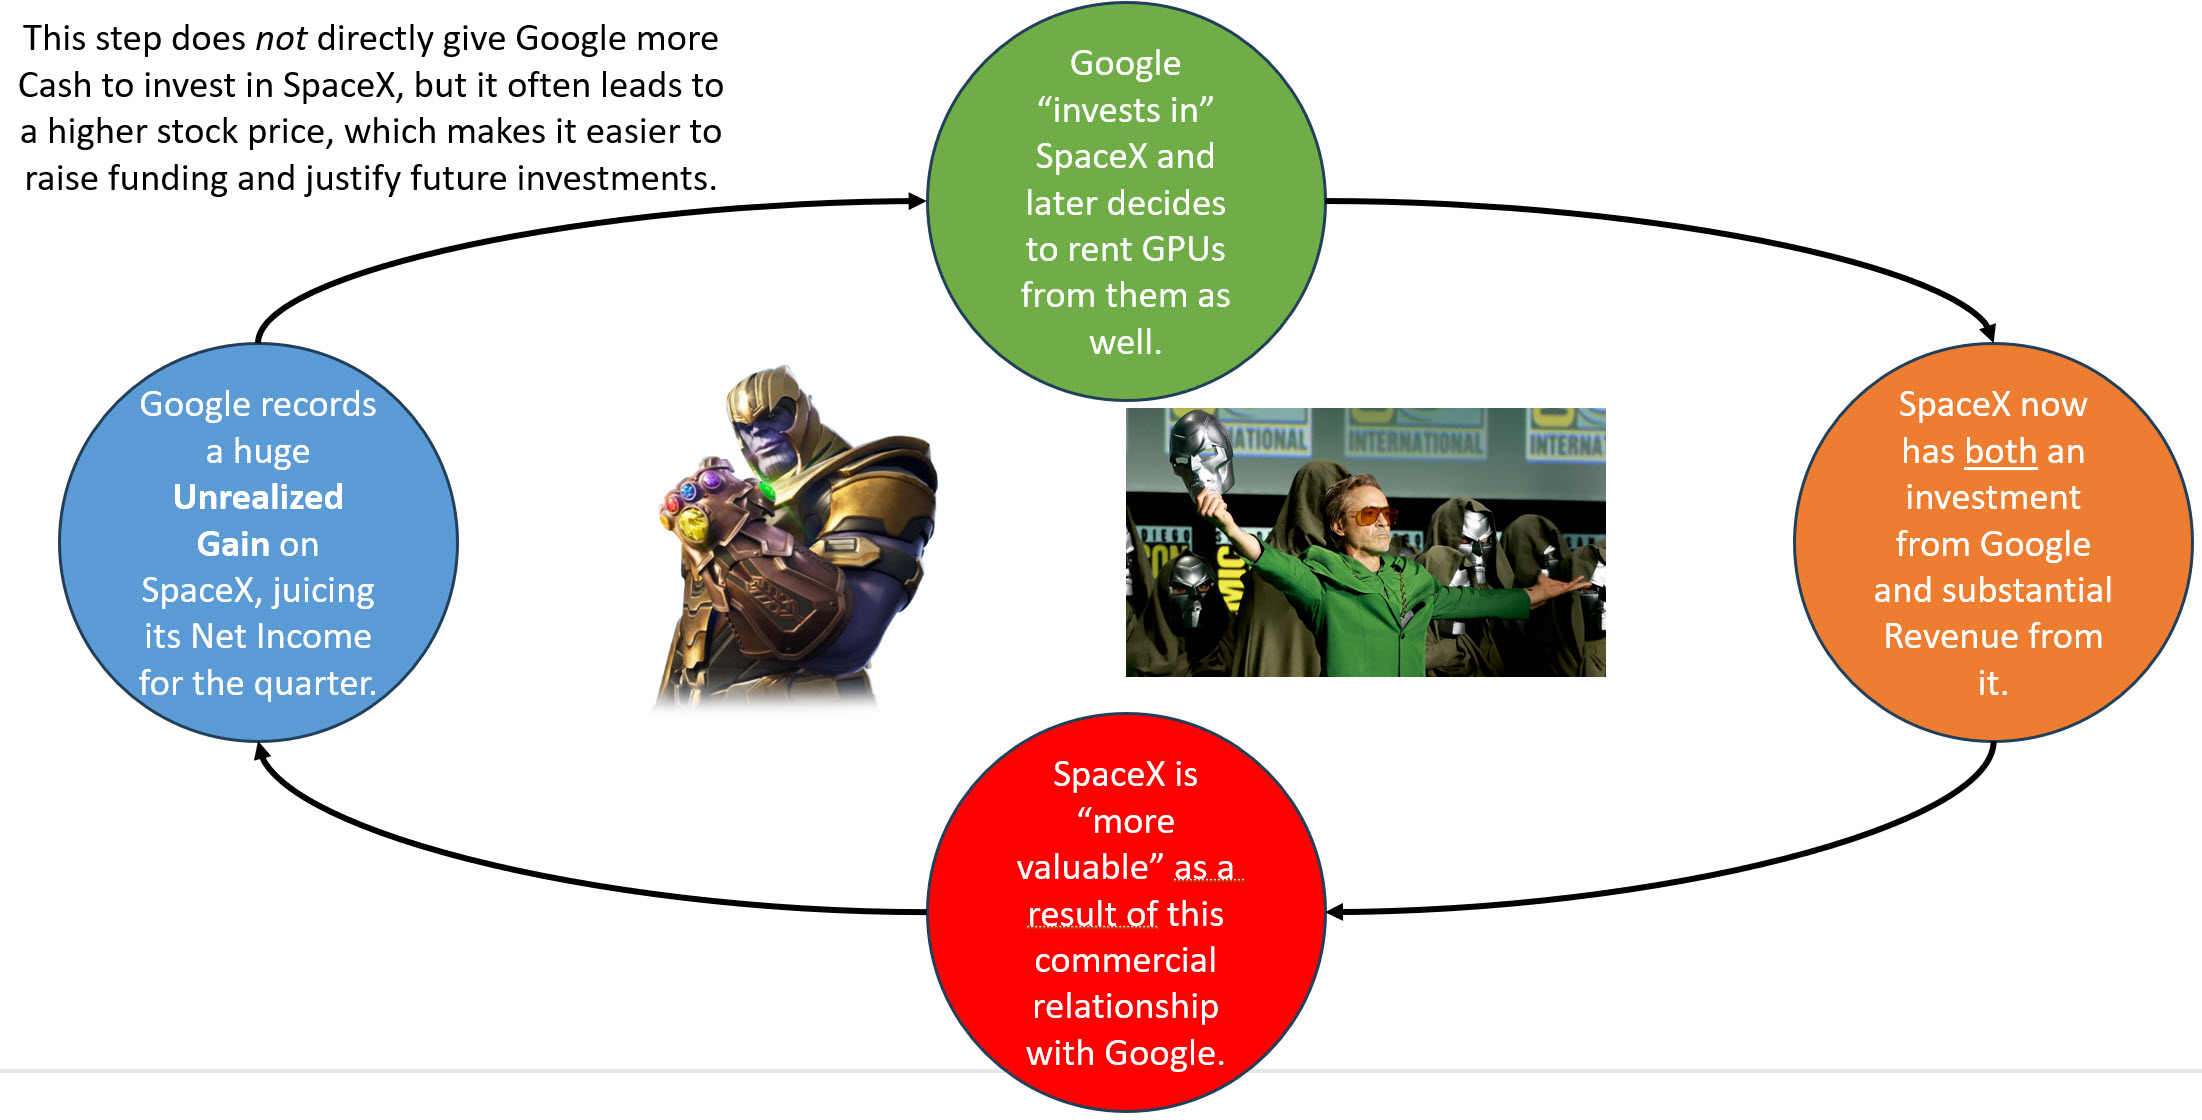
It’s not violating accounting rules or government regulations, but it would be far more transparent to disclose the financials related to these entities in separate categories.
At the very least, Realized and Unrealized Gains/Losses should be disclosed separately, and there should also be a separate line like the following for these relationships:
This name is too long, but you get the idea: If a huge company is set to record massive Unrealized Gains (or Losses!) on its investments in commercially related entities, the nature of these relationships should be clear.
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.

