


About Brian DeChesare
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.
CARR vs. ARR Definition: Annualized recurring revenue takes a company’s contractual subscription revenue over a month or quarter and multiplies it by 12 or 4 to get a yearly estimate for it; Contracted Annualized Recurring Revenue (CARR) also adds future bookings, expansions, and downgrades that have been *agreed to* in this period but have not yet been recorded in revenue.
CARR vs. ARR Definition: Annualized recurring revenue takes a company’s contractual subscription revenue over a month or quarter and multiplies it by 12 or 4 to get a yearly estimate for it; Contracted Annualized Recurring Revenue (CARR) also adds future bookings, expansions, and downgrades that have been *agreed to* in this period but have not yet been recorded in revenue.
When AI chatbots first entered the mainstream with the release of ChatGPT in 2022, many people noticed that “hallucinations” were a problem.
In other words, the AI frequently fabricated “facts” when it did not know the answer or have access to the required data.
While hallucinations are still a problem, AI tools have become more reliable for research purposes over time.
However, many AI startups and growth companies seem to be “hallucinating” their revenue – and this issue has gotten worse.
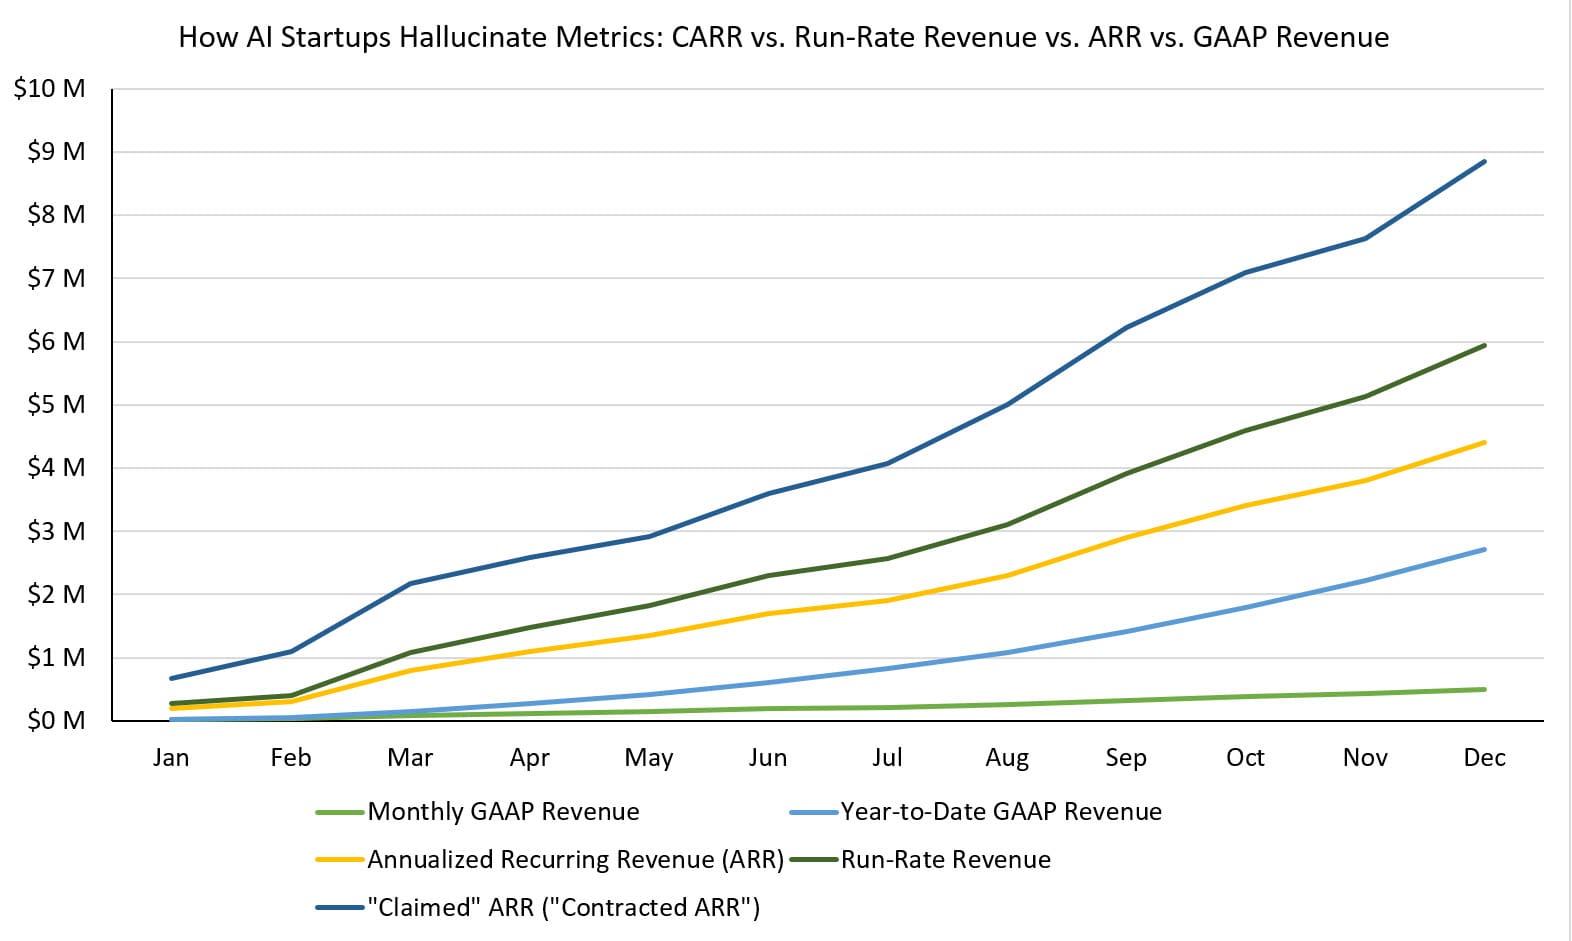
There seems to be confusion about the differences between Revenue, Recurring Revenue, Run-Rate Revenue, Annualized Recurring Revenue, and Contracted Annualized Recurring Revenue, which means that many companies use these terms incorrectly:
There are also some lingering issues about Bookings vs. Billings vs. Revenue, but we’ve explained those in a separate article.
For a sale to count toward Annualized Recurring Revenue (ARR), it should:
Many AI startups offer heavily discounted subscription plans in which the price scales up from Year 1 to Year 3:
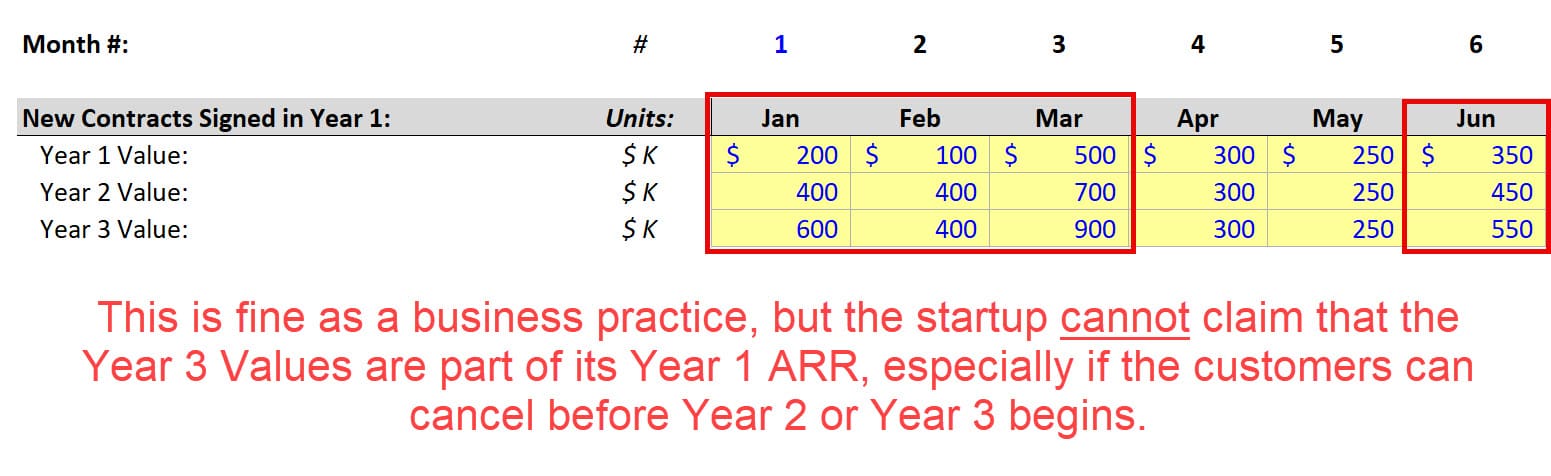
They can’t claim that the Year 3 rates are part of their Year 1 “Annualized Recurring Revenue,” especially if customers can cancel after each year.
In traditional enterprise SaaS, cancellation/churn rates are low, and it takes large companies a long time to make purchasing and integration decisions.
But with many AI products, this has reversed: Companies are curious, they test and trial many different solutions, and they often cancel early when they realize it doesn’t fit their needs, which produces higher churn rates.
Gross Margins also tend to be much lower and are often negative, especially in Year 1!
The bottom line: Beyond these CARR vs. ARR problems, we would argue that the ARR concept itself may not make much sense for AI startups and growth companies. They should be measured based on standard GAAP Revenue, as most will eventually switch to usage-based pricing.
Usage-based revenue is worth something, but it deserves a lower valuation multiple than revenue based on locked-in, annual or multi-year contracts.
Let’s say that we have a startup with 3 revenue sources: Subscriptions, usage-based revenue from tokens, and services revenue for clients who need implementation assistance.
The subscriptions are based on 3-year periods, with rates that escalate over time (e.g., $200K in Year 1, $400K in Year 2, and $600K in Year 3).
The usage revenue is 20% of the Year 1 contract values, and the services revenue is 15% of the monthly subscription revenue:
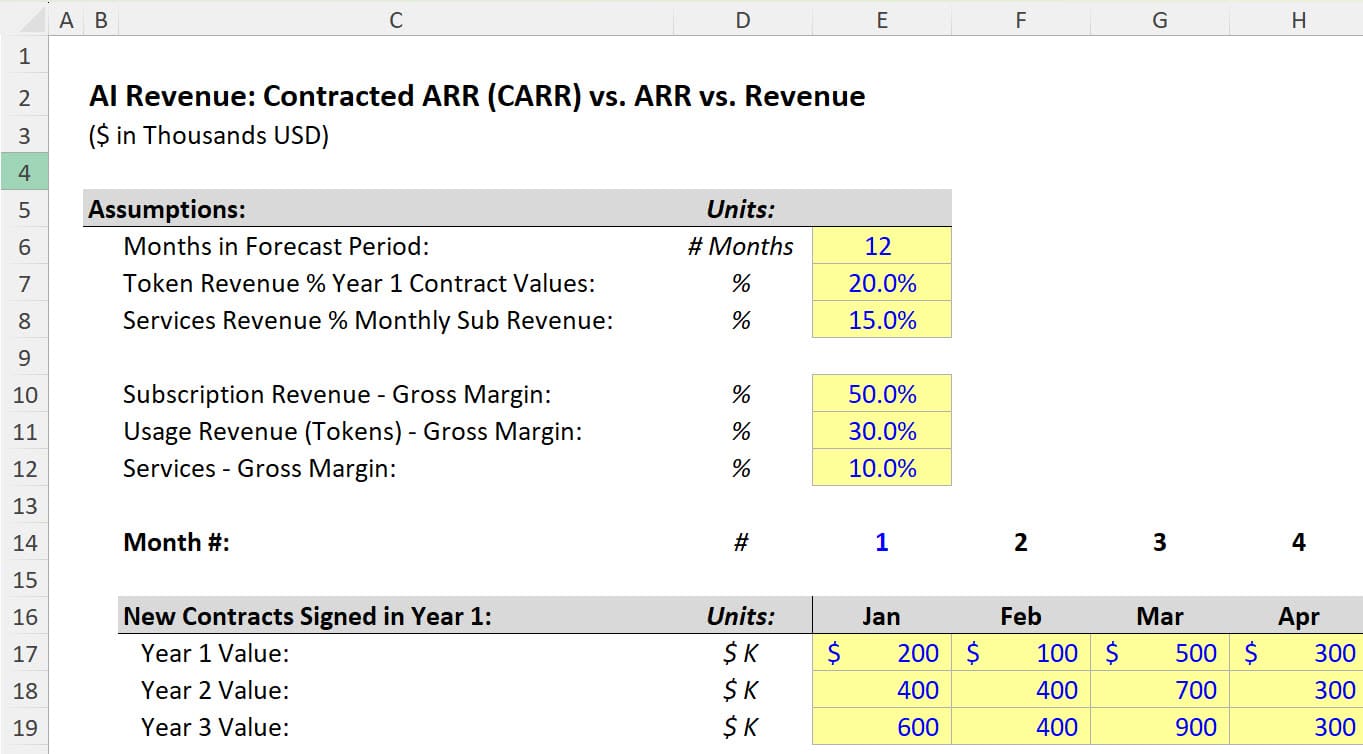
Subscription Revenue has the highest Gross Margins (50%), while the services that require on-site human labor have the lowest margins, at 10%.
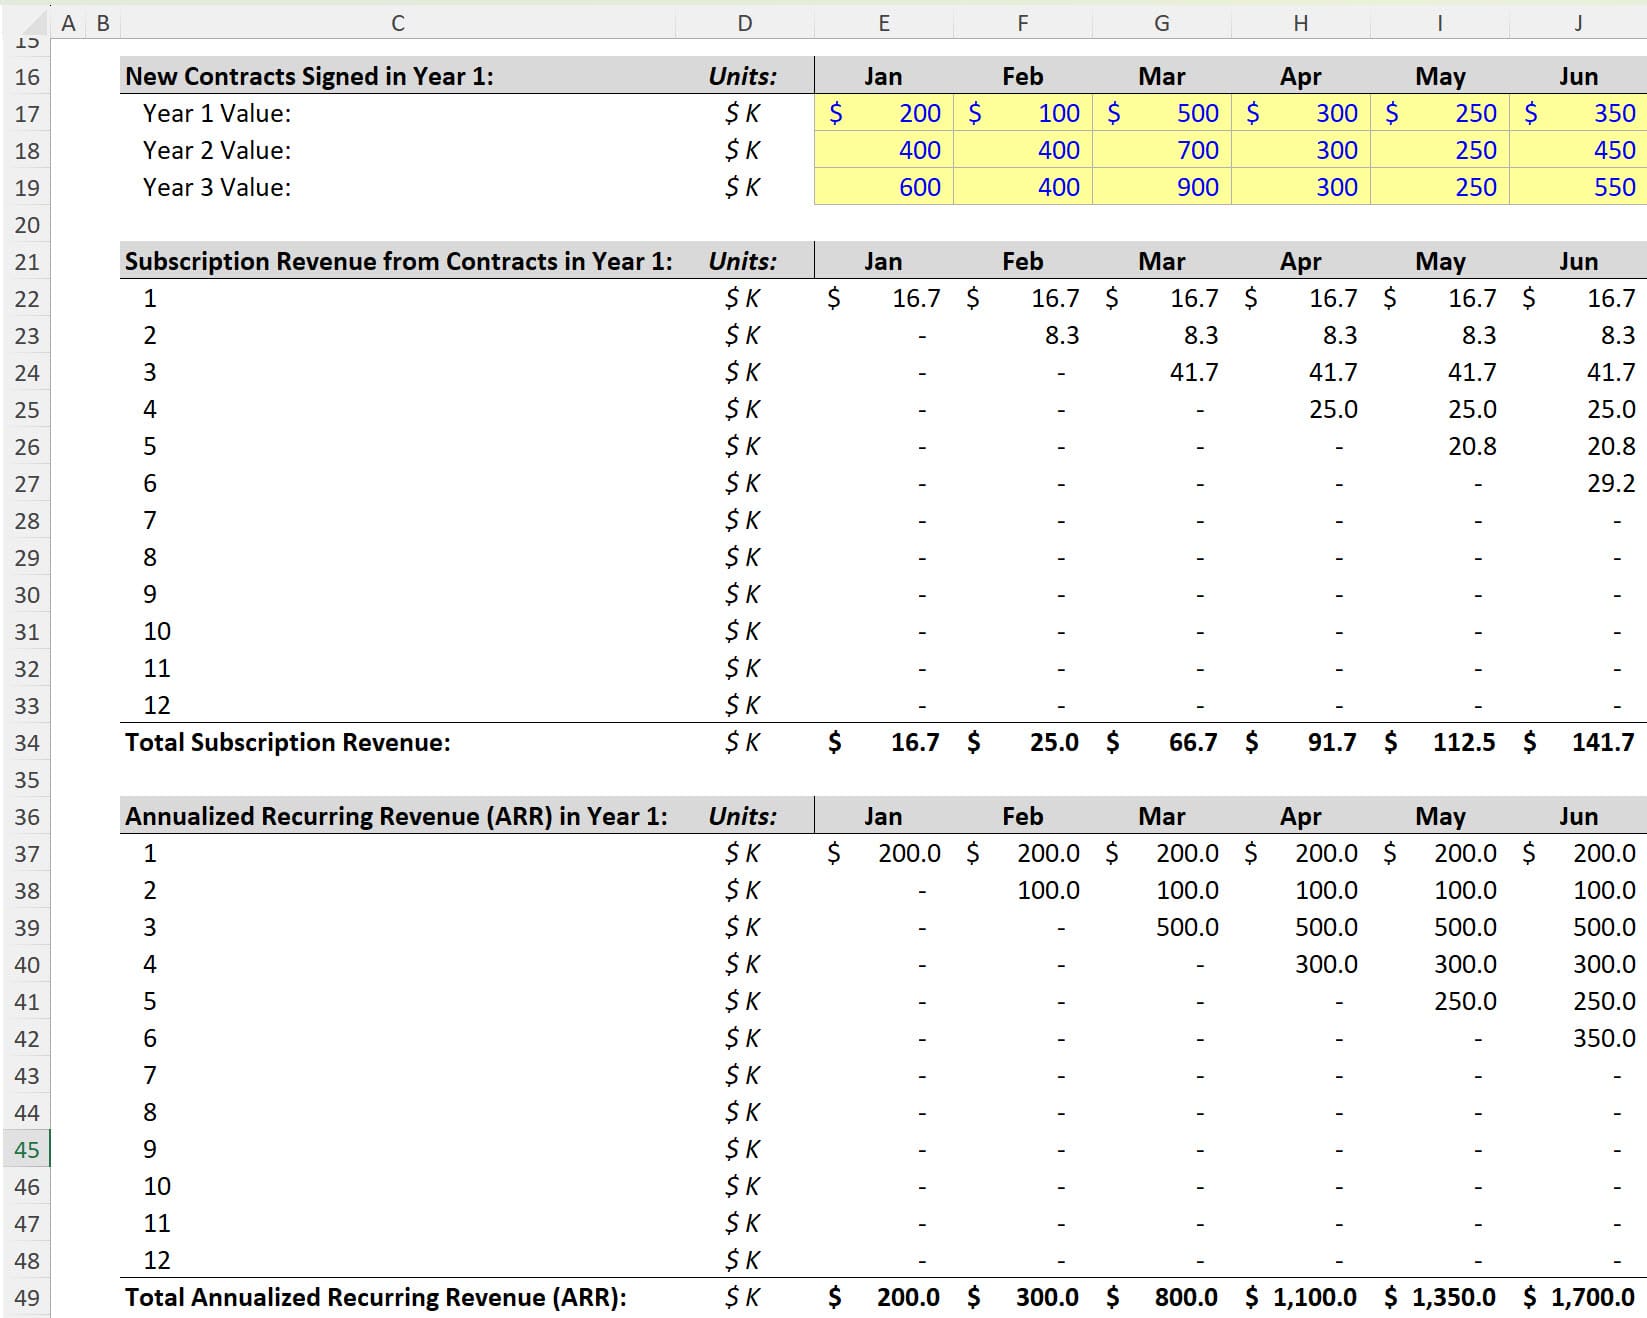
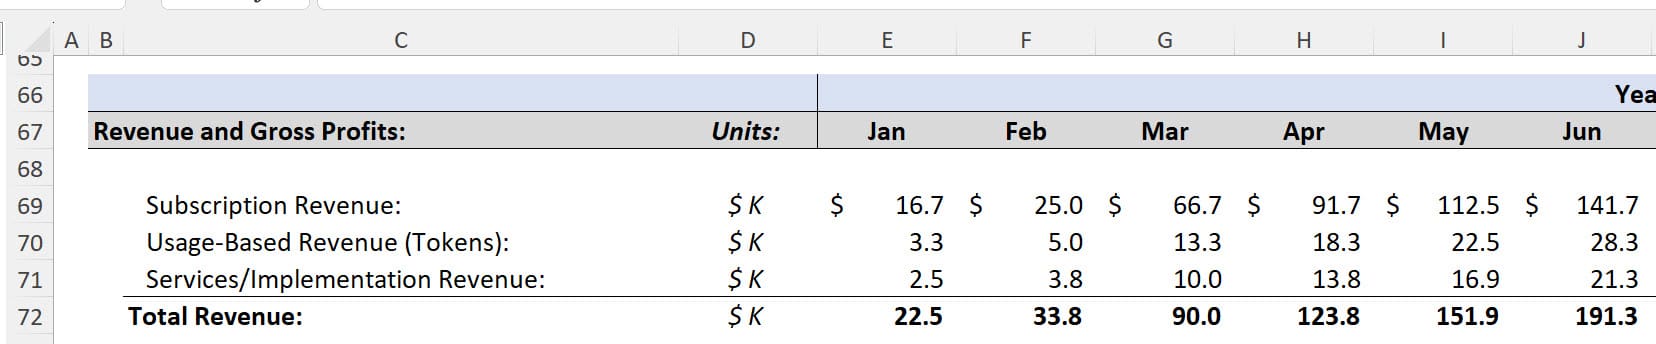
Based on this data, there are three useful metrics: Monthly Subscription Revenue, Annualized Recurring Revenue, and Total Revenue (measured monthly or year-to-date).
Subscription Revenue is based on the Year 1 New Contract Values signed each month, divided by 12, and extended across the entire first year.
ARR takes the entire annual value of each new contract and records it in each month, so it’s effectively Subscription Revenue * 12 in this first year:
Finally, Total Revenue equals the Subscription Revenue + Usage Revenue + Services Revenue (shown monthly here):
The issue is that many AI startups have twisted their way into using a metric called “Contracted Annualized Recurring Revenue” that is based on future upsells and expansions that customers have “agreed to,” even if they have not yet been reflected in revenue:
CARR = ARR + Future Bookings, Expansions, and Downgrades Agreed to in This Period But Not Yet Recorded in Revenue
In some contexts, CARR can be acceptable, especially if it’s for an established company and these “future events” are for just the next month or quarter.
However, many AI startups have assumed that customers paying at heavily discounted “Year 1” contract rates will keep paying without canceling and agree to the much higher Year 3 rates.
Then, they base their “ARR” numbers on these Year 3 contract values, even if the contracts are cancellable well before Year 3:
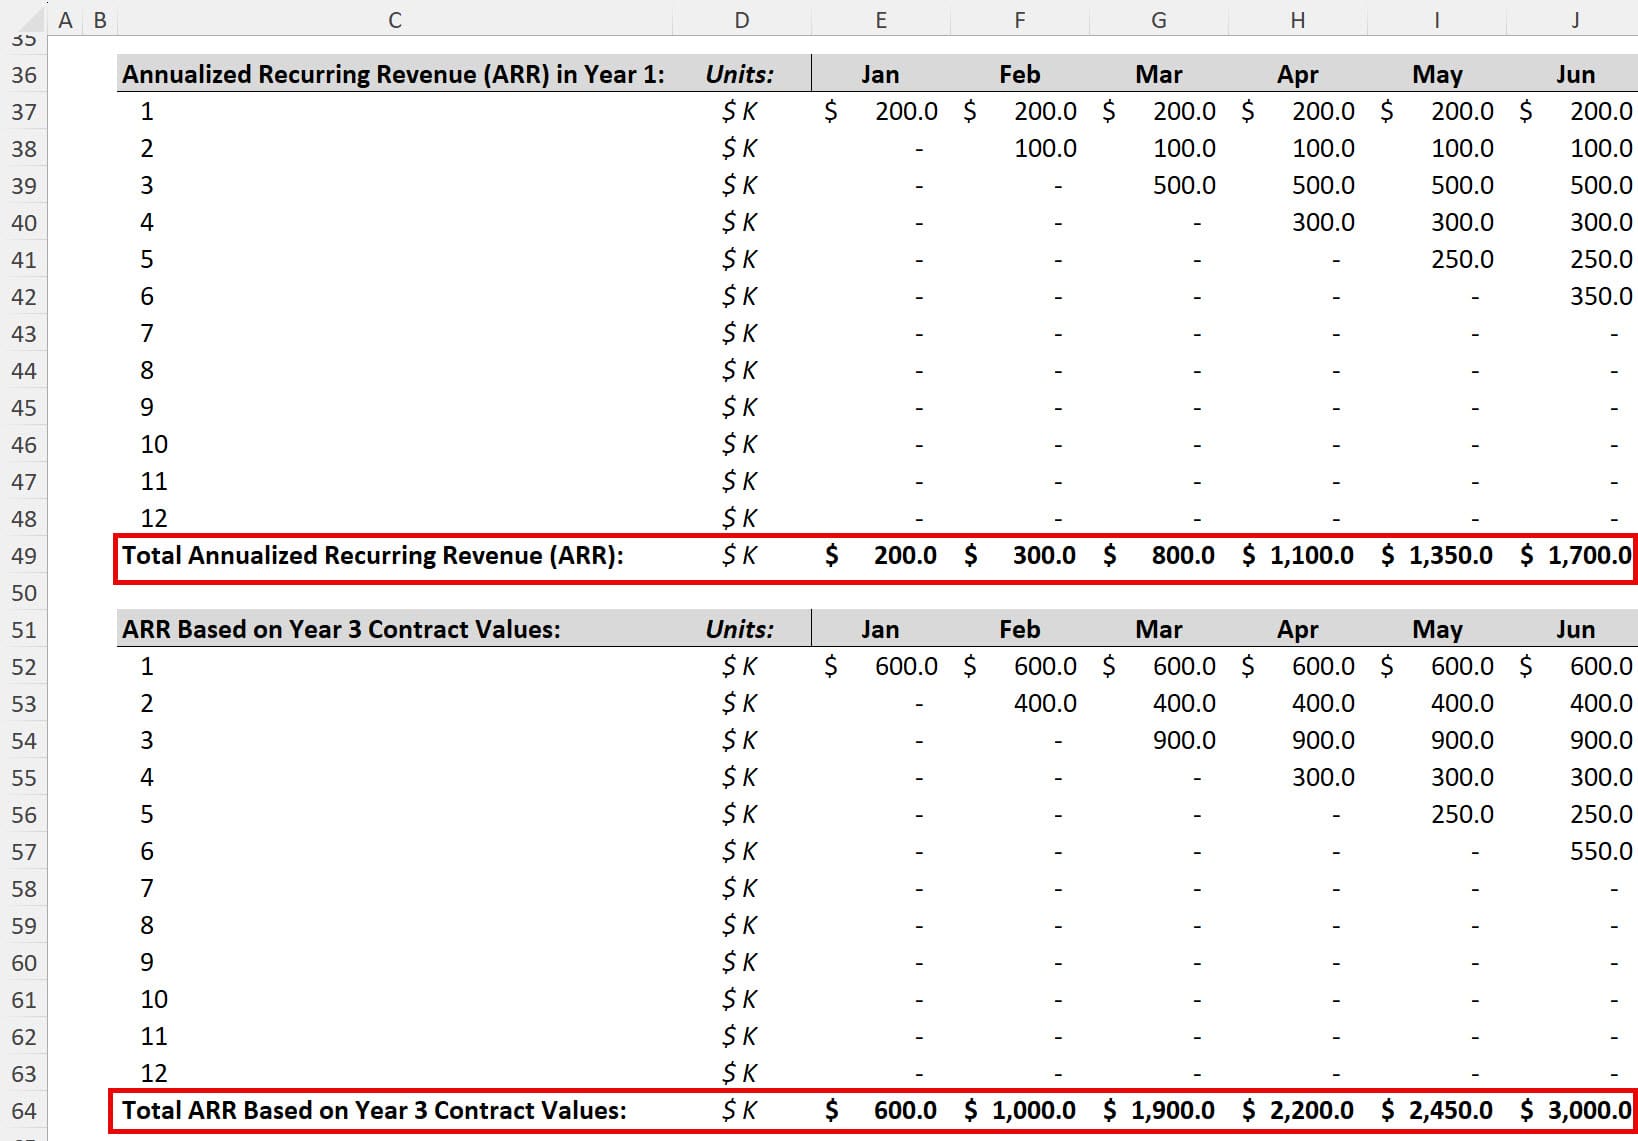
Some startups also claim that their ARR includes not just these Year 3 subscription values, but also their usage and services-based revenue, which creates a massive spread between these numbers:
The point of ARR is to annualize something that will happen with ~100% certainty over the next year, but which can only be recognized incrementally each month.
If there’s a decent chance that certain revenue sources will not persist over the next 12 months, they should not count toward ARR.
This is why it’s questionable to annualize revenue from monthly contracts and call it “ARR.”
Technically, it’s “allowed,” and many companies do it, but if customers can cancel in any month, and the cancellation rates are moderately high, it doesn’t provide much visibility.
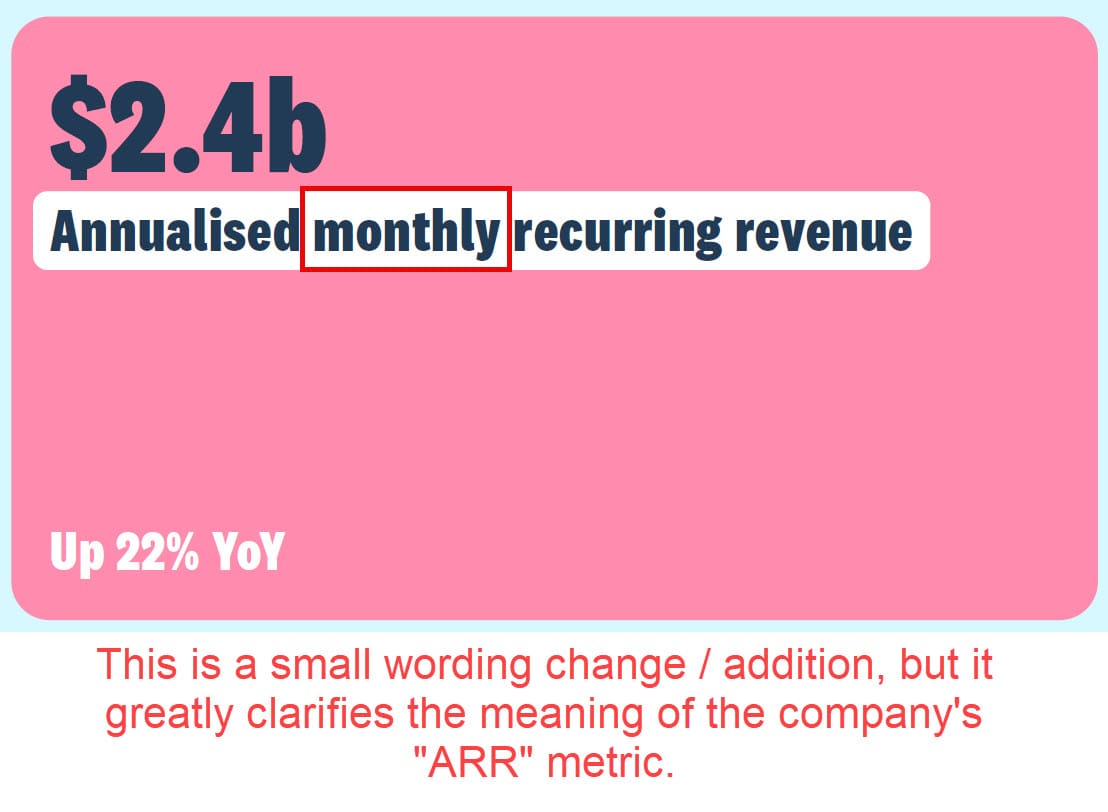
If a company does this, however, it’s best to be clear about the labeling and call it something like “Annualized Monthly Recurring Revenue,” as Xero does:
You might think this confusion is limited to startups riding the AI hype bandwagon, but even publicly traded companies make these mistakes.
For example, in its investor presentation, SoundHound AI defines its “Subscription Revenue” as follows:
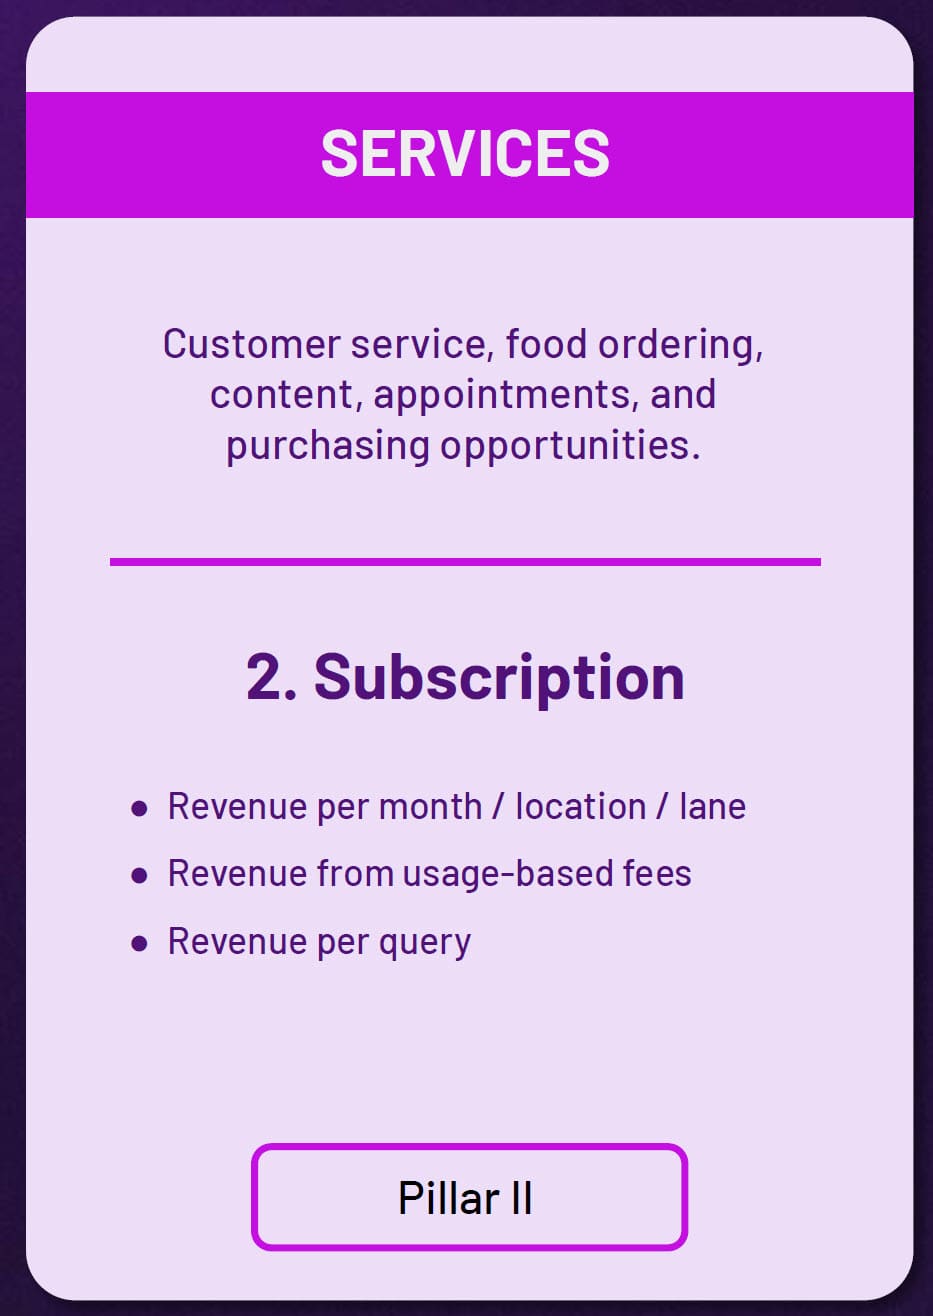
This is obviously wrong because “Revenue from usage-based fees” and “Revenue per query” are not recurring and are therefore not subscriptions.
If we wanted to value SoundHound by applying a different revenue multiple to each income stream, we would not feel confident doing so because it seems the company’s data may not be properly classified.
It’s not a CARR vs. ARR issue here; it’s a simple misunderstanding of “subscriptions.”
Revenue from usage fees and queries is still worth something, but it is worth less than revenue from locked-in subscriptions that will take at least a year to deliver.
The textbook-defined purpose of ARR is to approximate a SaaS company’s subscription revenue over the next year based on its most recent month or quarter.
This gives you a better sense of its business momentum and current growth rates.
But there are also a few implicit assumptions baked into this:
An AI startup can have higher Gross Margins and Retention Rates, but if it does not, ARR makes less sense as a key metric.
First, if you are analyzing a company that sells primarily AI-based products/services, focus on GAAP revenue or run-rate revenue rather than ARR and apply lower multiples to them because of the issues outlined above.
“Run-rate revenue” is useful for approximating growth for startups, but it’s not reasonable to say that Monthly Revenue * 12 represents the company’s revenue over the next year, especially if customers can easily cancel.
If the company only sells subscriptions and does so at healthy margins and churn rates, ARR might be appropriate, but you need to dig in and assess this for yourself.
Second, always ask for the Gross Revenue Retention, Net Revenue Retention, and Gross Margin numbers because these determine how “sticky” the product is, how much new customer acquisition will be required for growth, and what the eventual cash flows might be.
Finally, if a company seems to be using the incorrect definitions or misclassifying usage-based revenue as “subscriptions,” ask for a breakout of the revenue and gross profits by source.
You may not be able to fix all the hallucinations, but you can figure out the companies that are worth paying attention to.
Brian DeChesare is the Founder of Mergers & Inquisitions and Breaking Into Wall Street. In his spare time, he enjoys lifting weights, running, traveling, obsessively watching TV shows, and defeating Sauron.

